France’s factory sector is losing momentum again, with September’s HCOB manufacturing PMI declining amid mounting cost pressure, softer demand and a broader slowdown in industrial activity that is already filtering through to production expectations.
France Manufacturing PMI Falls on Higher Diesel Costs
The reading matters because manufacturing is one of the first parts of the economy to feel a squeeze from higher energy and transport costs, and France is now facing record diesel prices that are raising input costs for factories, logistics firms and farms. That makes it harder for producers to protect margins, even before any hit from weaker domestic or export orders.
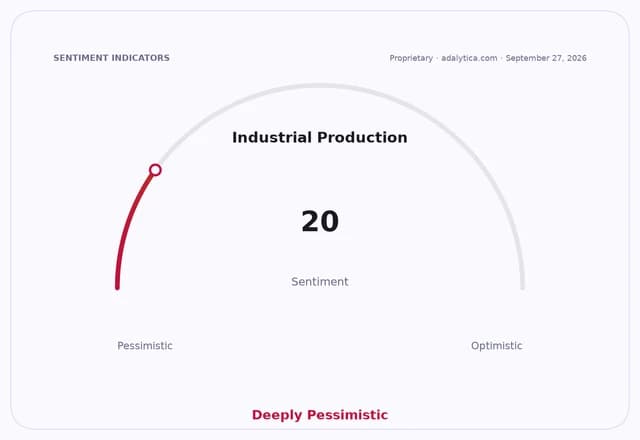
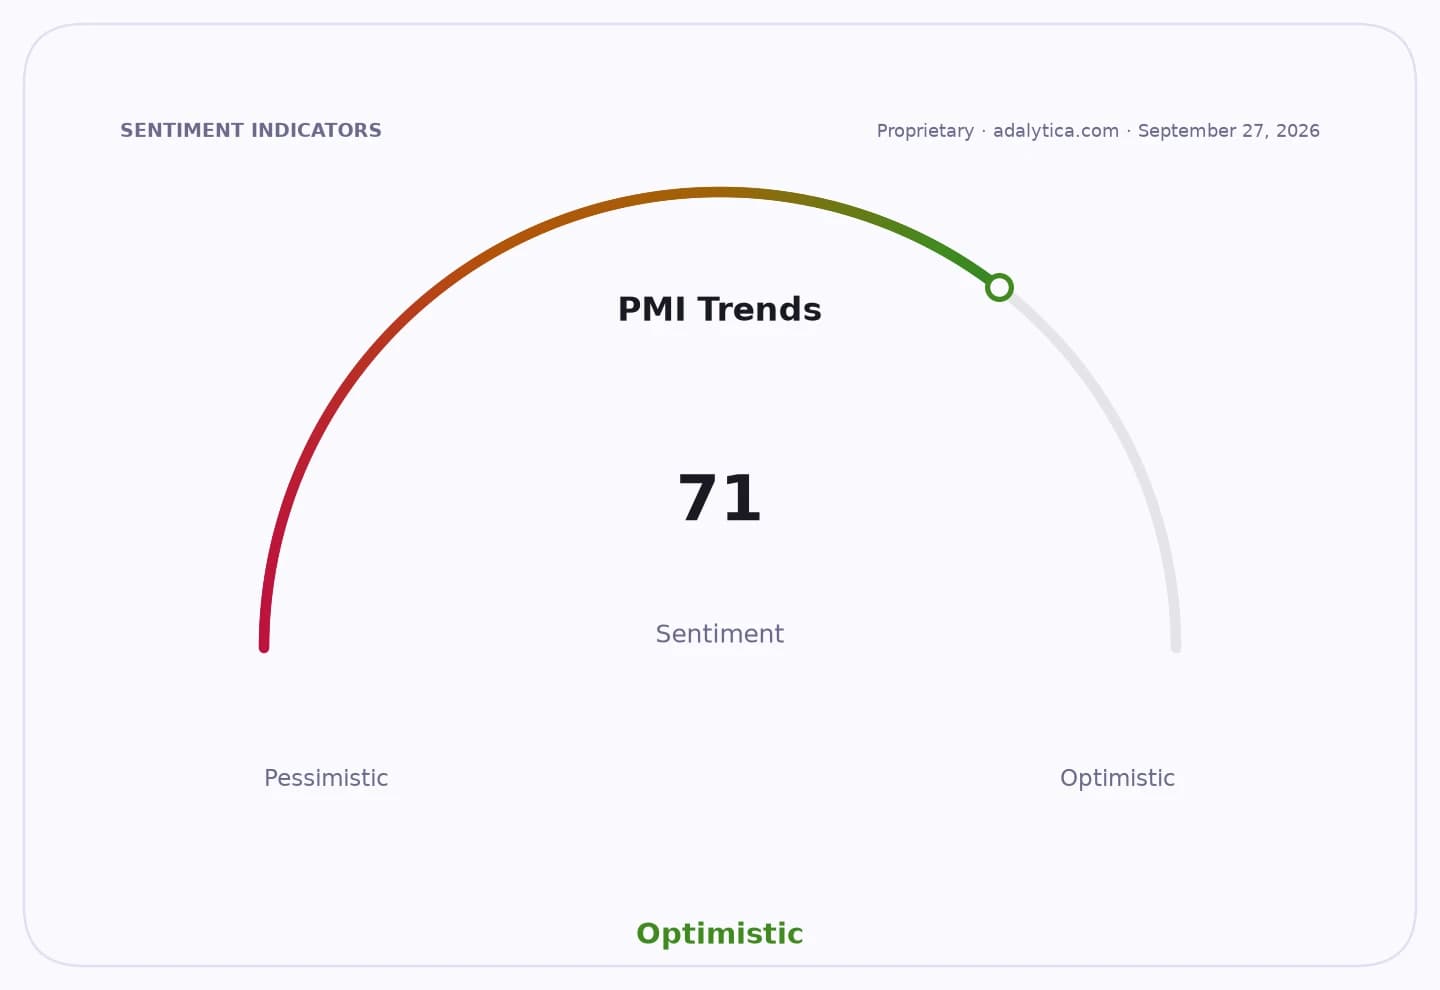
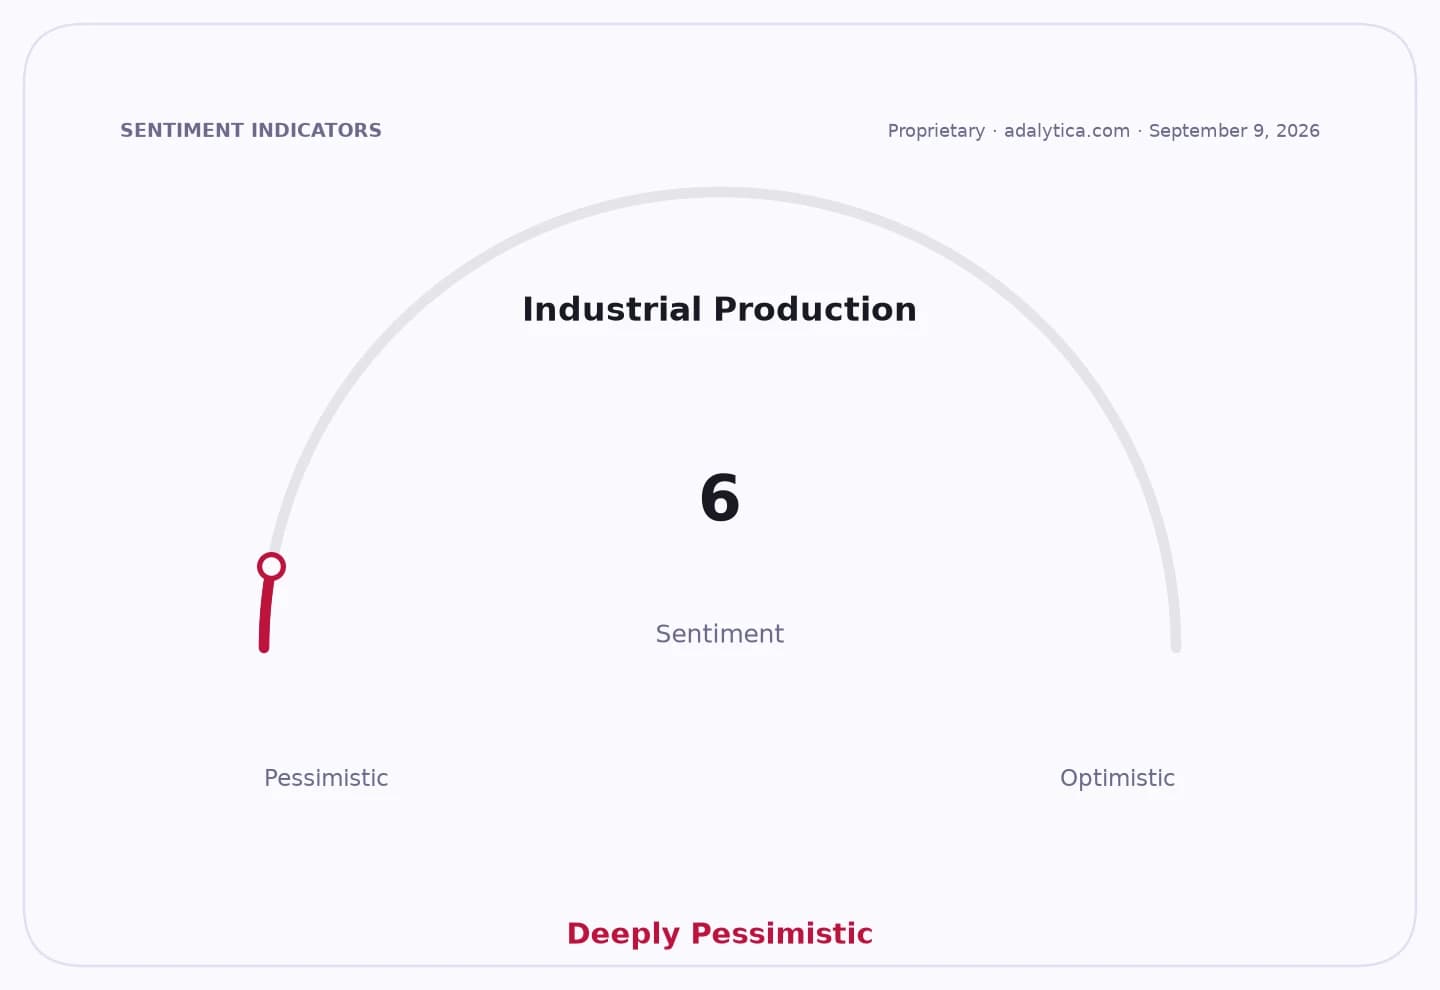
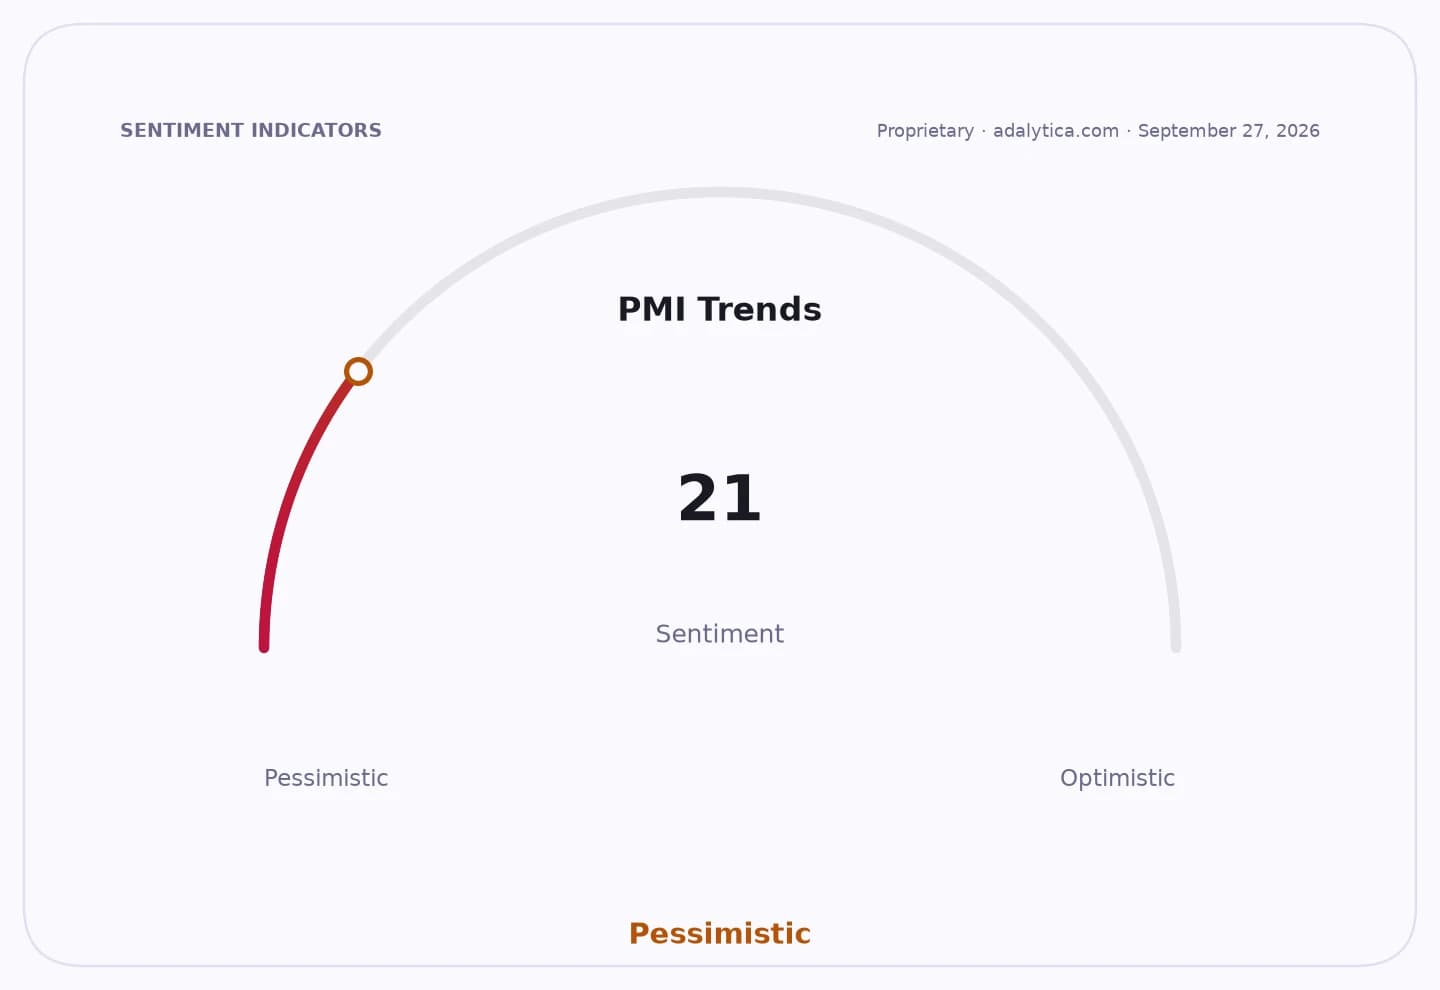
The pullback adds to signs that France’s industrial base is struggling to sustain the modest stabilization seen earlier in the year. Adalytica’s PMI Trend Recession sentiment gauge shows “Fear” at 21, down sharply over the past month, while its industrial production sentiment is also in fear territory at 20, suggesting the market is increasingly pricing in downside risk for factory output.
Economic pain is not limited to manufacturing alone. Diesel averaging 2.41 euros a liter is lifting freight and distribution costs, and the strain is spilling into agriculture as well, with French wine output already at a 70-year low and the government subsidizing growers to cut production. Those pressures feed back into broader inflation dynamics and can crimp consumer spending if businesses pass on more of the bill.
For investors, the PMI decline reinforces a cautious view on French cyclicals, industrial suppliers and transport-heavy businesses, while supporting demand for defensive names and firms with stronger pricing power. It also keeps pressure on policymakers, who may face calls for relief measures if elevated fuel costs continue to weigh on output and employment.
The next test is whether weaker manufacturing is a one-month setback or the start of a more persistent downturn, with upcoming industrial production data and any government response to energy costs likely to determine whether the slowdown deepens.
| Entity | Gains | Losses |
|---|---|---|
| Energy suppliers | ▲Higher fuel revenues | ▼Political pressure |
| French manufacturers | ▲Possible pricing leverage | ▼Margin compression |
| Logistics and transport firms | ▲None | ▼Higher operating costs |
| Defensive equities | ▲Relative capital inflows | ▼Cyclical exposure |