Granite REIT is telling investors the same thing in two ways: it is growing, and it can afford to share more of that growth with unitholders.
Granite REIT raises distribution after $270.5M acquisitions
The industrial landlord’s third-quarter update pairs $270.5 million of new acquisitions with a 4.2% increase in its distribution starting in December 2026, a combination that points to expanding cash flow rather than financial engineering. For income investors, that matters because REITs live and die by the durability of their payouts. When a company can buy assets and still raise its distribution, it usually means management sees room for earnings growth ahead.
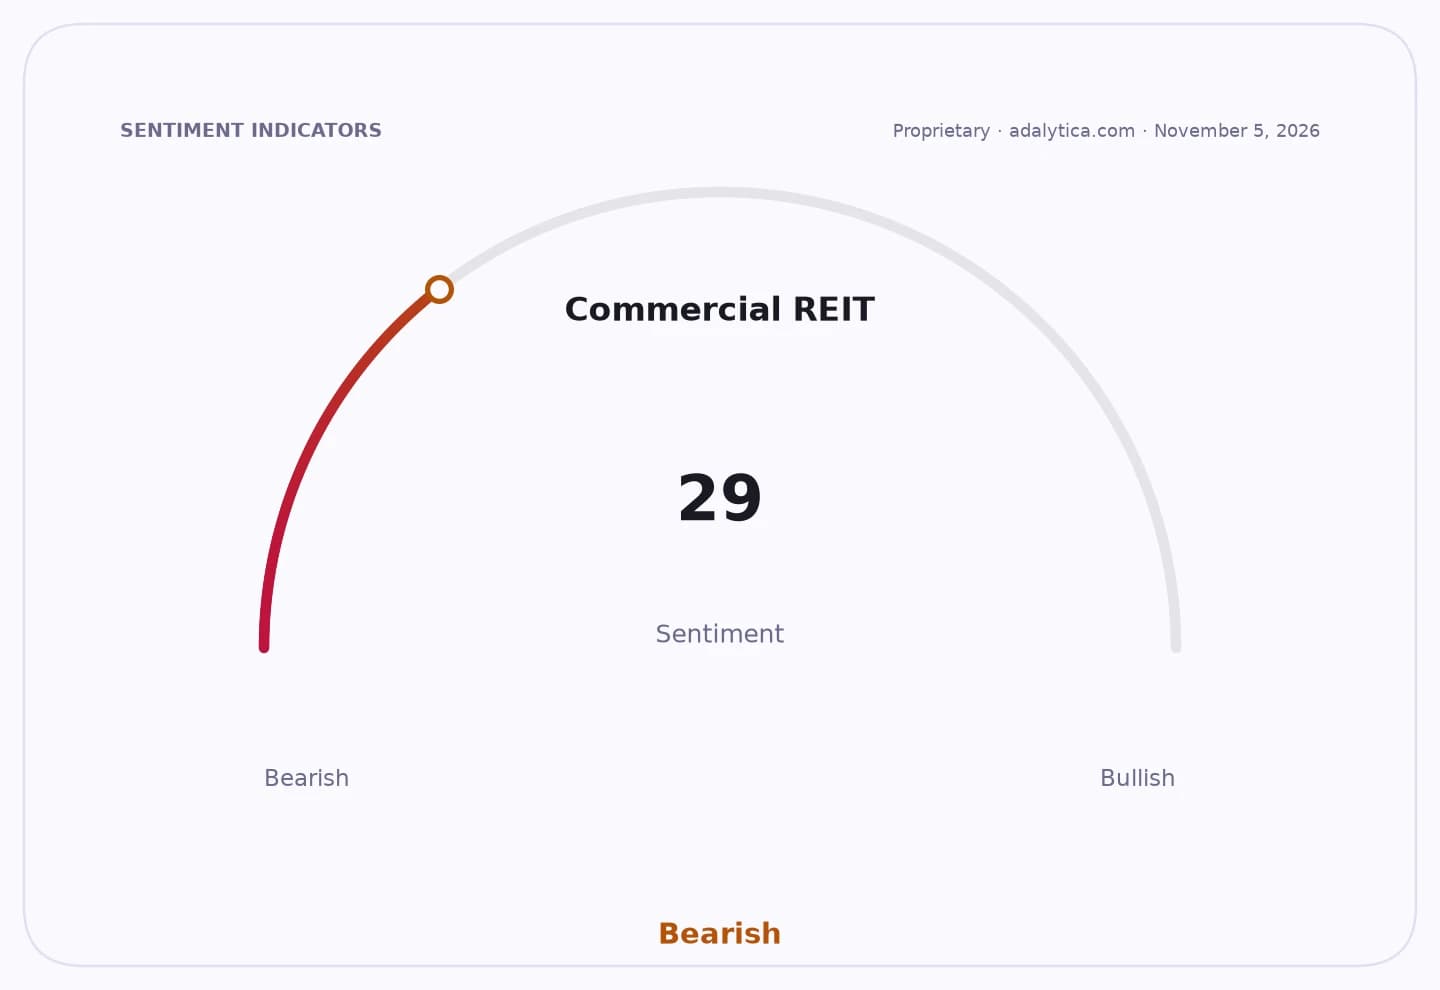
Sentiment Indicators
That is especially relevant in a market where commercial property investors have been starved for confidence. REIT sentiment remains deeply cautious, even as broader equity markets have recovered, and rates are still a central variable for property valuations. In that backdrop, Granite’s decision to step up its payout suggests it believes its portfolio and acquisition pipeline can keep generating enough funds from operations to support both growth and income.
The acquisition total also matters because industrial real estate remains one of the more resilient corners of property investing. Demand tied to logistics, manufacturing, and supply-chain reconfiguration has kept high-quality warehouse and distribution assets in focus, even as parts of the REIT sector have struggled with slower leasing and higher financing costs. Granite’s move to add assets now suggests management wants to keep compounding while pricing may still be attractive relative to recent years.
For investors, the message is less about a one-quarter pop and more about the kind of business Granite wants to be over the next several years. A growing distribution can support valuation, attract income-oriented capital, and reinforce confidence that acquisition-led growth is translating into shareholder returns. That is the kind of setup long-term investors tend to prefer: a visible payout stream backed by hard assets and a management team still willing to deploy capital.
The stock’s recent trading around its 50-day moving average also suggests the market is reassessing the story rather than euphorically chasing it. That can be healthy. REITs often reward patience more than excitement, and Granite’s latest update gives income investors a reason to keep it on the watchlist, especially if management can keep buying disciplined assets and protecting cash generation through 2027.
| Entity | Gains | Losses |
|---|---|---|
| Granite REIT unitholders | ▲Higher cash distribution | ▼Some capital withheld for growth |
| Granite REIT | ▲More assets, stronger cash flow base | ▼Integration and financing risk |
| Income-focused investors | ▲Rising payout visibility | ▼Missed upside if they stay on sidelines |
| Competing REITs | ▲— | ▼Higher bar for distribution growth |