Alexandros Exarchou’s expanding energy role matters less for the public controversy around it than for the commercial map it is redrawing: long-term LNG contracts, regional offtake deals and government backing are turning Greece into a transit and trading hub for Southeast Europe.
Greece Vertical Corridor Gains LNG Contracts
The most important development is that the Vertical Corridor has moved from political concept to bankable business. A framework that was publicly discussed in September 2025, before Kimberly Guilfoyle arrived in Athens, has since produced a 20-year LNG sales pact with Venture Global, an expansion of contracted volumes to 1 million tonnes a year, a U.S.-backed ministerial statement, and separate supply agreements reaching Albania and Ukraine. For investors, that is the difference between a geopolitical narrative and a revenue-generating platform.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 21, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
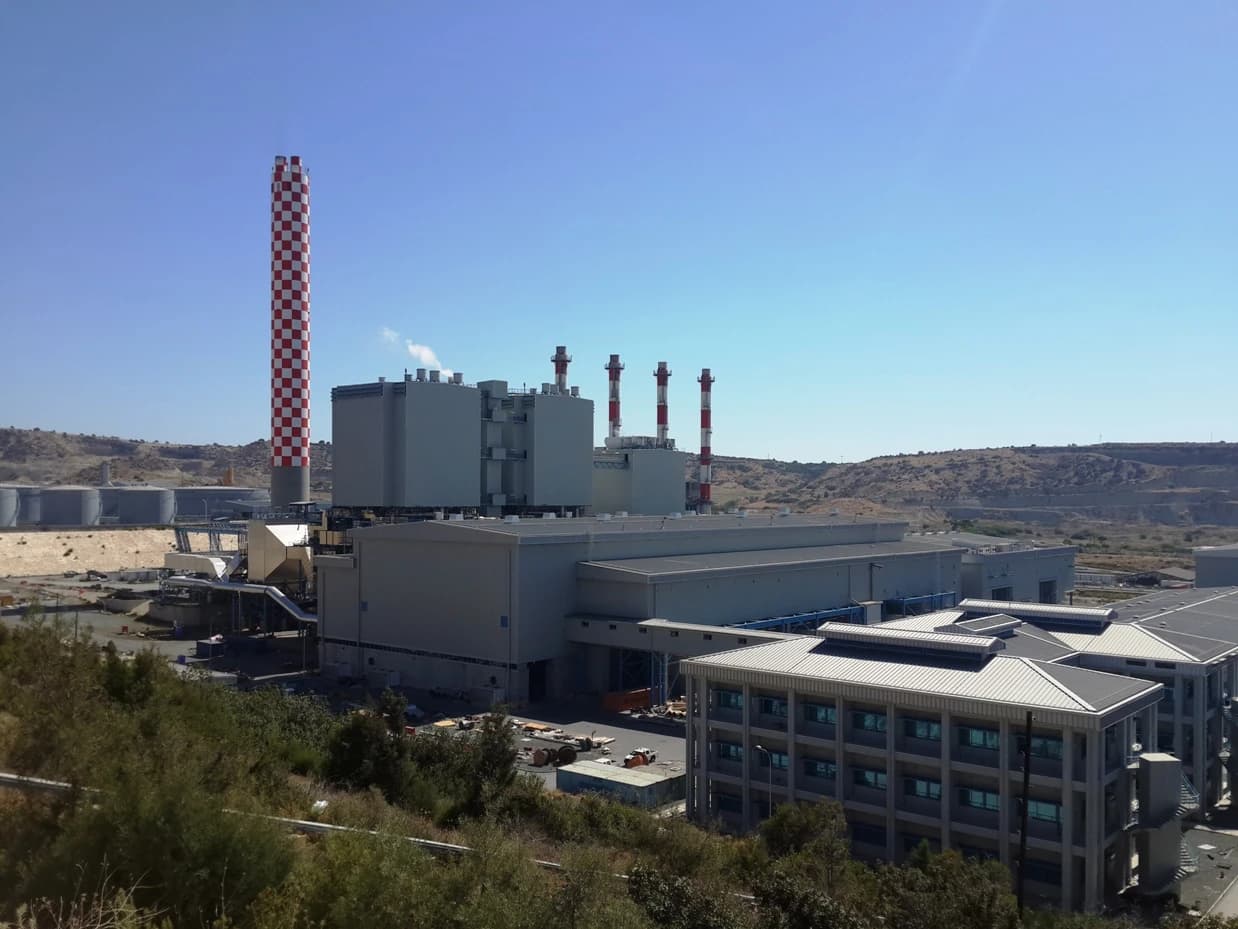
The economics are straightforward. Long-dated LNG contracts are the foundation for infrastructure financing because they lock in volumes, counterparties and cash flow visibility. Atlantic SEE LNG’s initial agreement with Venture Global in November 2025 covered at least 500,000 tonnes annually from 2030; by June 2026 that had doubled, a sign that demand is material enough to support scale. In Albania, AKTOR LNG USA said a 20-year contract would supply 1 billion cubic metres a year from 2030, with expected lifetime revenue of about €6 billion. The Ukraine deal, by contrast, shows the corridor can be used before the long-term contracts start flowing, giving the route immediate commercial relevance.
That combination matters because Europe’s gas system still depends on replacing Russian molecules with contracted alternatives, not slogans. The joint statement from the United States, Greece, Bulgaria, Romania, Moldova and Ukraine explicitly endorsed the Vertical Corridor and Washington said it was ready to facilitate American LNG deliveries to Greek terminals. In other words, the initiative has moved into the intersection of energy security policy and private capital allocation. That support lowers political risk, improves the odds of downstream investment and strengthens the case for associated infrastructure such as terminals, pipelines and storage.
The strategic logic is also shifting the balance of power in the region. Greece benefits if it can monetize geography through transit fees, trading margins and greater leverage over cross-border flows. Albania gains supply security and infrastructure development. U.S. LNG exporters gain another outlet into Europe. By contrast, competitors that would prefer different transit routes, or suppliers that benefit from fragmented Balkan gas markets, stand to lose optionality. Turkey remains an important rival in the broader energy geography, even if Greece’s EU status gives the corridor a different regulatory and political profile.
The market backdrop supports the thesis. LNG remains tight enough that suppliers value binding long-term commitments, while buyers need route diversification to hedge supply disruptions and geopolitical shocks. That is why Exarchou’s emphasis on public documentation, contracted volumes and named counterparties matters. It reduces execution uncertainty. It also explains why the story is not just about one executive’s contacts but about whether a Greek-led corridor can be scaled into a durable trade lane.
For investors, the bull case is that the agreements become self-reinforcing: more contracted supply brings more buyers, which in turn justifies more infrastructure and more volumes. The bear case is execution risk — permitting, financing, construction, cross-border coordination and the possibility that political attention outruns the physical build-out. But the sequence already visible in the record suggests this is no longer a speculative plan. It is a staged commercial program with signed contracts, public government support and a defined 2030 revenue base.
What happens next will hinge on how quickly those agreements move from paper to throughput. If the corridor can keep adding counterparties in the Balkans and the Black Sea region, Greece’s role in Europe’s gas architecture could expand materially, with implications for AKTOR, Atlantic SEE LNG, regional utilities and U.S. LNG exporters alike.
| Entity | Gains | Losses |
|---|---|---|
| Greece / AKTOR / Atlantic SEE LNG | ▲transit revenues; strategic leverage | ▼execution burden; project risk |
| Albania and Ukraine | ▲supply diversification; energy security | ▼dependence on corridor build-out |
| Venture Global / U.S. LNG exporters | ▲long-term export outlet | ▼rivals seeking alternate routes |
| Turkey and competing suppliers | ▲— | ▼lost route influence; weaker bargaining power |