Helping a partner with heavy debt starts with understanding why the debt exists, because the right fix for $20,000 in credit cards and more than $100,000 in student loans depends on whether the problem is spending, income or both.
High Debt Help Starts With Cause, Not Cash
That distinction matters economically because credit card borrowing at 20% to 29% interest is a fast-moving drain on household cash flow, while student debt can carry federal repayment options, forgiveness pathways or lower-rate structures that change the urgency of repayment. For couples, the wrong strategy can keep debt servicing costs elevated even if payments are being made.
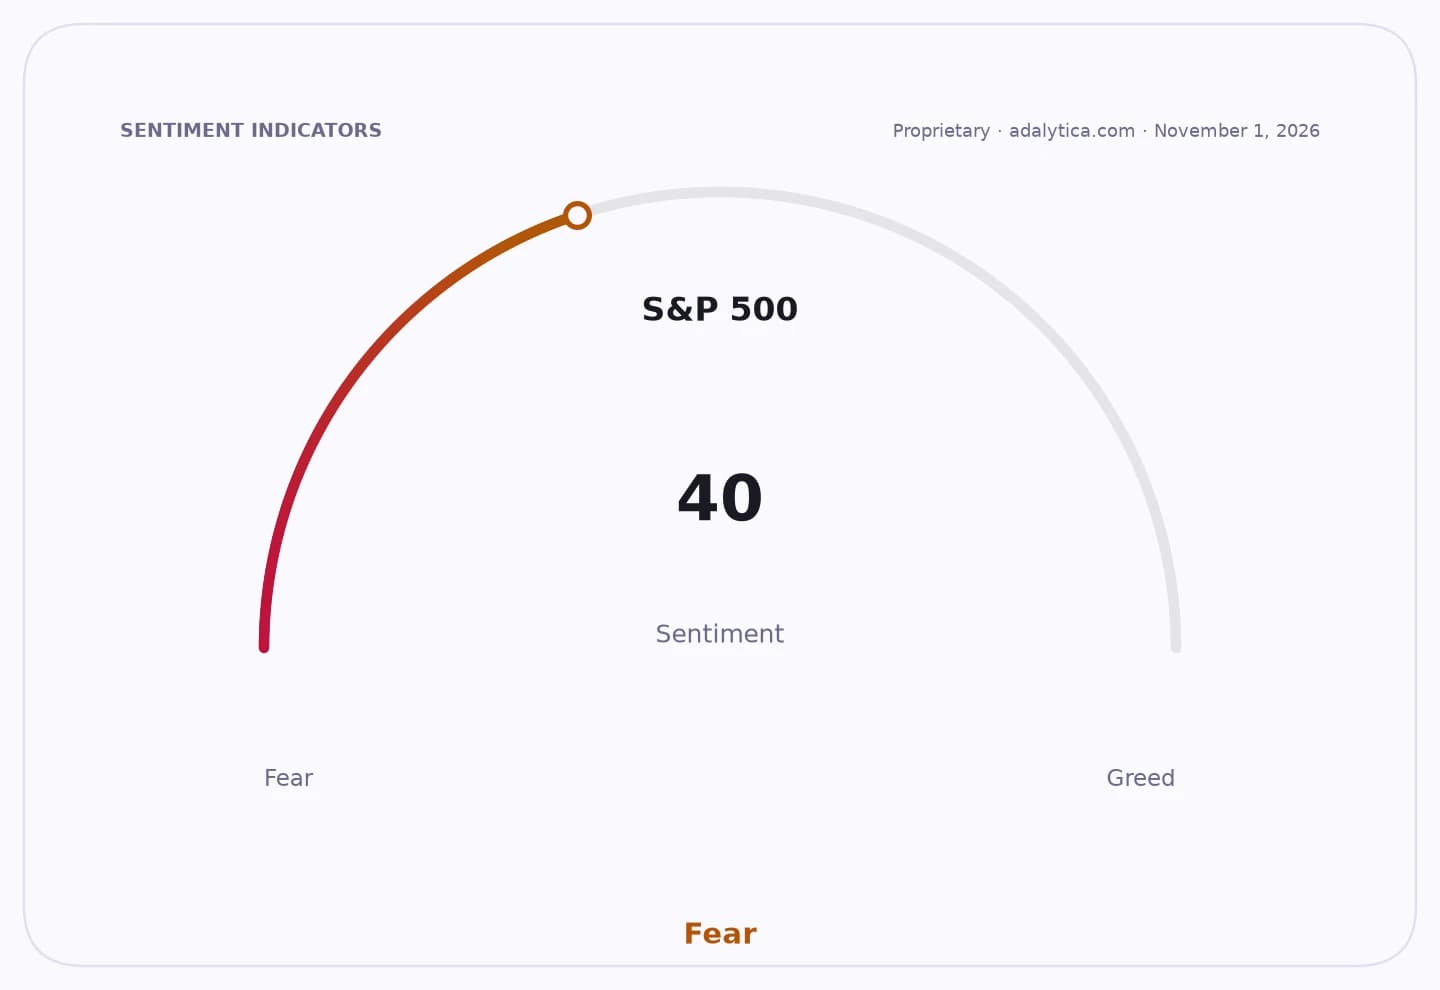
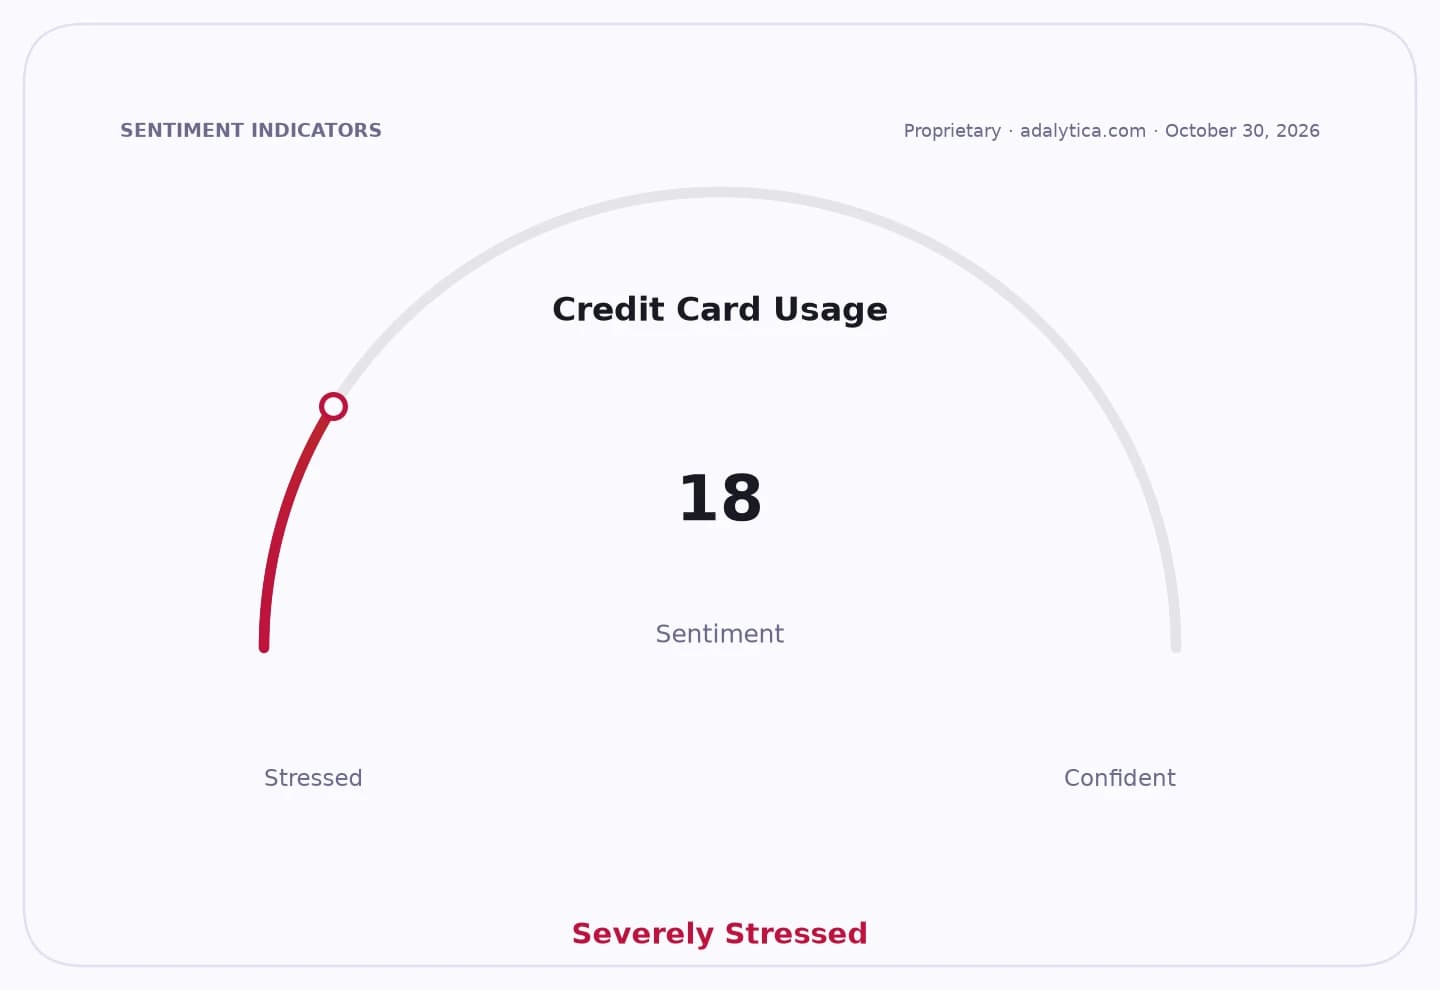
Sentiment Indicators
Douglas Boneparth, a certified financial planner and founder of Bone Fide Wealth, says the first step is to ask whether the debt came from financial anxiety, a lack of money management skills or simply income that was too low to cover essentials. If debt accumulated because living costs outpaced income, he says, no payoff plan will work until the income side improves.
For investors, the backdrop is a consumer still living with high borrowing costs even as the broad labor market remains relatively stable. The unemployment rate stood at 4.2% in September, with a forecast of 4.09% for October, while the federal funds rate was 3.75% in September, after a projected 3.726% in October — levels that still keep financing costs above the near-zero era that fueled easy credit.
Boneparth says the credit card balance should be attacked first because of its higher interest rate. He recommends the avalanche method — minimum payments on all debts, with any extra money going to the highest-rate balance first — as the most efficient approach, though he notes some borrowers stay motivated better with the snowball method, which targets the smallest balance first.
That advice lands as consumers remain sensitive to debt-service pressure and lenders watch repayment behavior closely. Ally Financial’s shares finished at $38.17 on Oct. 30, below its 50-day moving average of $39.78 and 200-day average of $41.6, while Synchrony Financial closed at $75.35, roughly in line with its 50-day average of $75.02. Capital One closed at $204.85, near its 50-day average of $204.69, reflecting a market that is still weighing credit risk and household stress rather than pricing in a clean break from it.
The bigger message is that helping a struggling partner is less about handing over cash than building a repayment plan that matches the real cause of the debt. For households, the next catalyst is whether rates, employment and student-loan rules make that burden easier to refinance, restructure or finally pay down.
| Entity | Gains | Losses |
|---|---|---|
| Borrowers with high-rate cards | ▲Faster principal reduction | ▼Interest expense |
| Student-loan borrowers | ▲Repayment flexibility | ▼Unclear payoff timeline |
| Lenders/credit card issuers | ▲Continued minimum payments | ▼Higher default risk |
| Partners/families | ▲Clearer debt plan | ▼Short-term budget strain |