Hyundai Motor Group is trying to turn its robotics ambition into a profit engine just as Chinese competition is squeezing its core car business and its shares have fallen back to earth.
Hyundai Motor Group Pushes Factory AI Amid Weak Shares
That is the key investment story here: Hyundai is no longer treating physical AI as a branding exercise after Boston Dynamics lit up investor enthusiasm earlier this year. It is moving deeper into AI-powered factories, logistics robots and automated inspection systems because the economics of traditional auto manufacturing are getting tougher, and because the market has begun to doubt how quickly robotics can translate into earnings.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 21, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
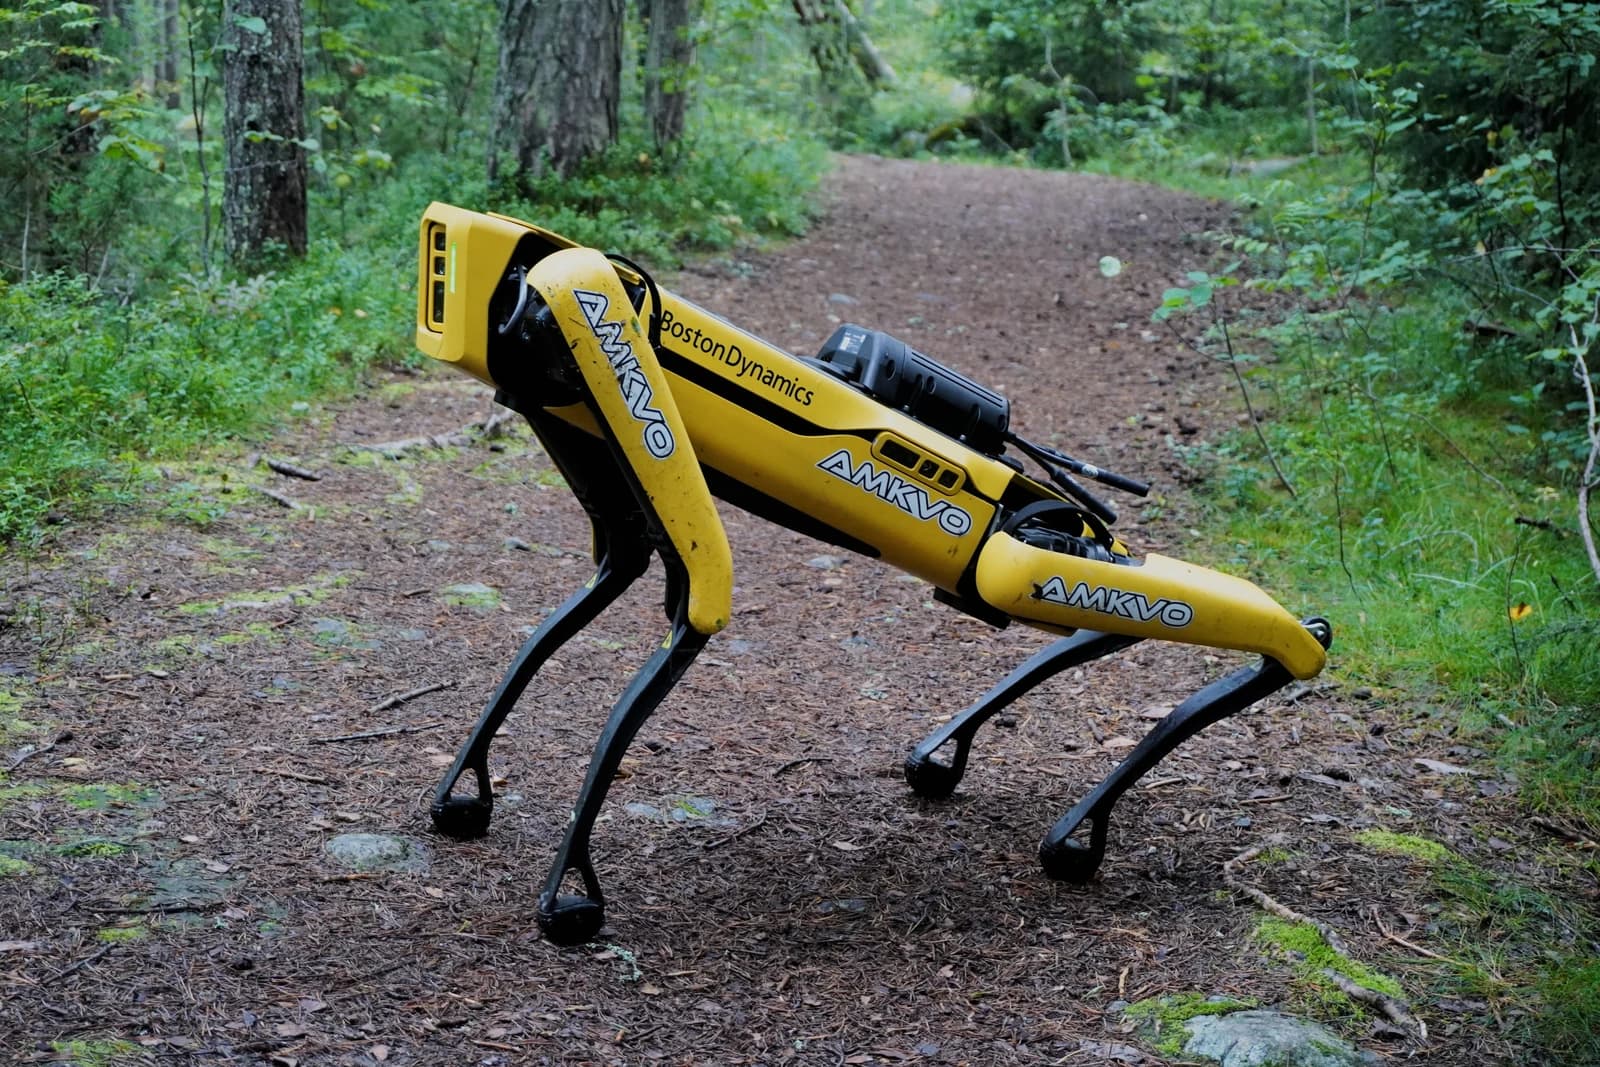
The urgency is easy to see in the stock. Hyundai’s shares more than doubled after Boston Dynamics unveiled its Atlas humanoid robot at CES in January, peaking at 755,000 won in June. They have since slumped to 312,000 won, close to pre-CES levels, as excitement around robotics faded and investors refocused on weak earnings and the lack of a clear profit timeline. The market is effectively asking the same question over and over: when does physical AI stop being capex and start becoming margin expansion?
That question matters because Hyundai’s core auto business is under pressure from a global EV price war led by lower-cost Chinese models. If Hyundai cannot defend profitability in conventional vehicles, it needs productivity gains elsewhere. Physical AI gives it a path to lower labor intensity, reduce defects and automate repetitive factory work, which could be more valuable over time than the headline-grabbing robot demos. In other words, this is not just a technology story; it is a manufacturing cost story and a margin defense story.
Hyundai is already pushing those applications inside its own operations. At its Uiwang research and development center south of Seoul, the group is building AI factory systems, logistics robots and automated vehicle inspection tools. It is working with Nvidia on Polaris, an AI-powered manufacturing platform designed to help factory workers access information and analyze production data more efficiently. It is also developing AI inspection systems that can identify exterior defects automatically, a move that could cut reliance on outside suppliers and improve quality control.
The longer-term prize is even bigger. Hyundai is also building software that can automatically generate robot movement paths through computer simulation, reducing the need for manual programming. That project is due to be completed by June 2027 and points to a factory model where AI handles increasingly complex tasks with less human intervention. If it works, the payoff is not just lower costs at Hyundai and Kia plants, but a repeatable industrial platform that could be exported across the manufacturing base.
Investors should still be cautious about the timing. Boston Dynamics has reportedly accumulated about 1.7 trillion won in losses over the past five years, and speculation about a delayed IPO has only added to the uncertainty. That means the market is unlikely to reward Hyundai for promise alone. But the strategic direction is clear: the company is trying to use physical AI as a second growth pillar while defending its industrial moat against China’s manufacturing scale and pricing power.
The trade here is not simply Hyundai versus its own stock chart. It is old-line automakers versus a new industrial order built on AI, automation and factory software. If Hyundai can prove that robotics improves throughput, quality and margins at scale, the market will eventually rerate the story. Until then, the share slump creates the opportunity: investors who believe physical AI will matter economically, not just theatrically, should watch Hyundai’s factory automation rollout as a multiyear catalyst rather than a short-term headline.
| Entity | Gains | Losses |
|---|---|---|
| Hyundai Motor Group | ▲Lower factory costs, new growth avenue | ▼Near-term valuation skepticism |
| Boston Dynamics | ▲Strategic importance, potential monetization | ▼Pressure to prove profitability |
| Chinese EV rivals | ▲Market share gains via lower pricing | ▼Less room for Hyundai to defend margins |
| Hyundai investors | ▲Potential long-term rerating if AI pays off | ▼Short-term earnings uncertainty |