Festive-season ecommerce sales in India are starting weaker than expected, with online dispatches running 10% to 12% below a year ago as higher prices for smartphones, laptops and home appliances cool shopper appetite.
India Ecommerce Festive Sales Run Below Last Year
That matters because the festive window is the most important sales period for Indian ecommerce, when a large share of annual gross merchandise value is generated and discount-led volume growth usually masks weaker underlying demand. This year, that engine is sputtering just as consumers are being asked to pay 30% to 40% more for premium electronics than they did a few months ago.
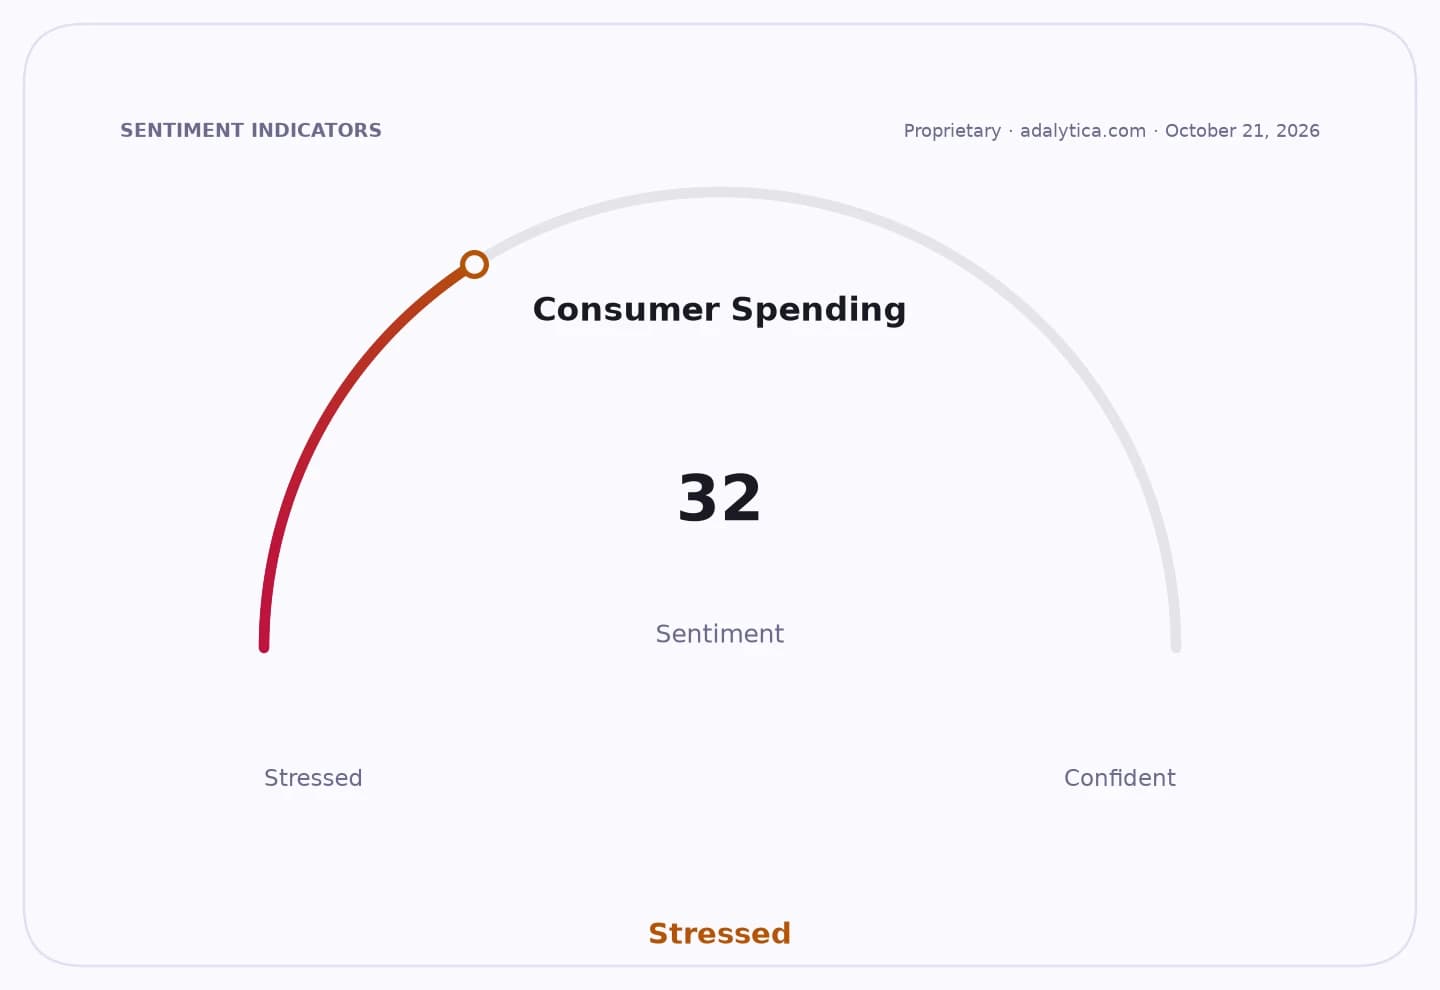
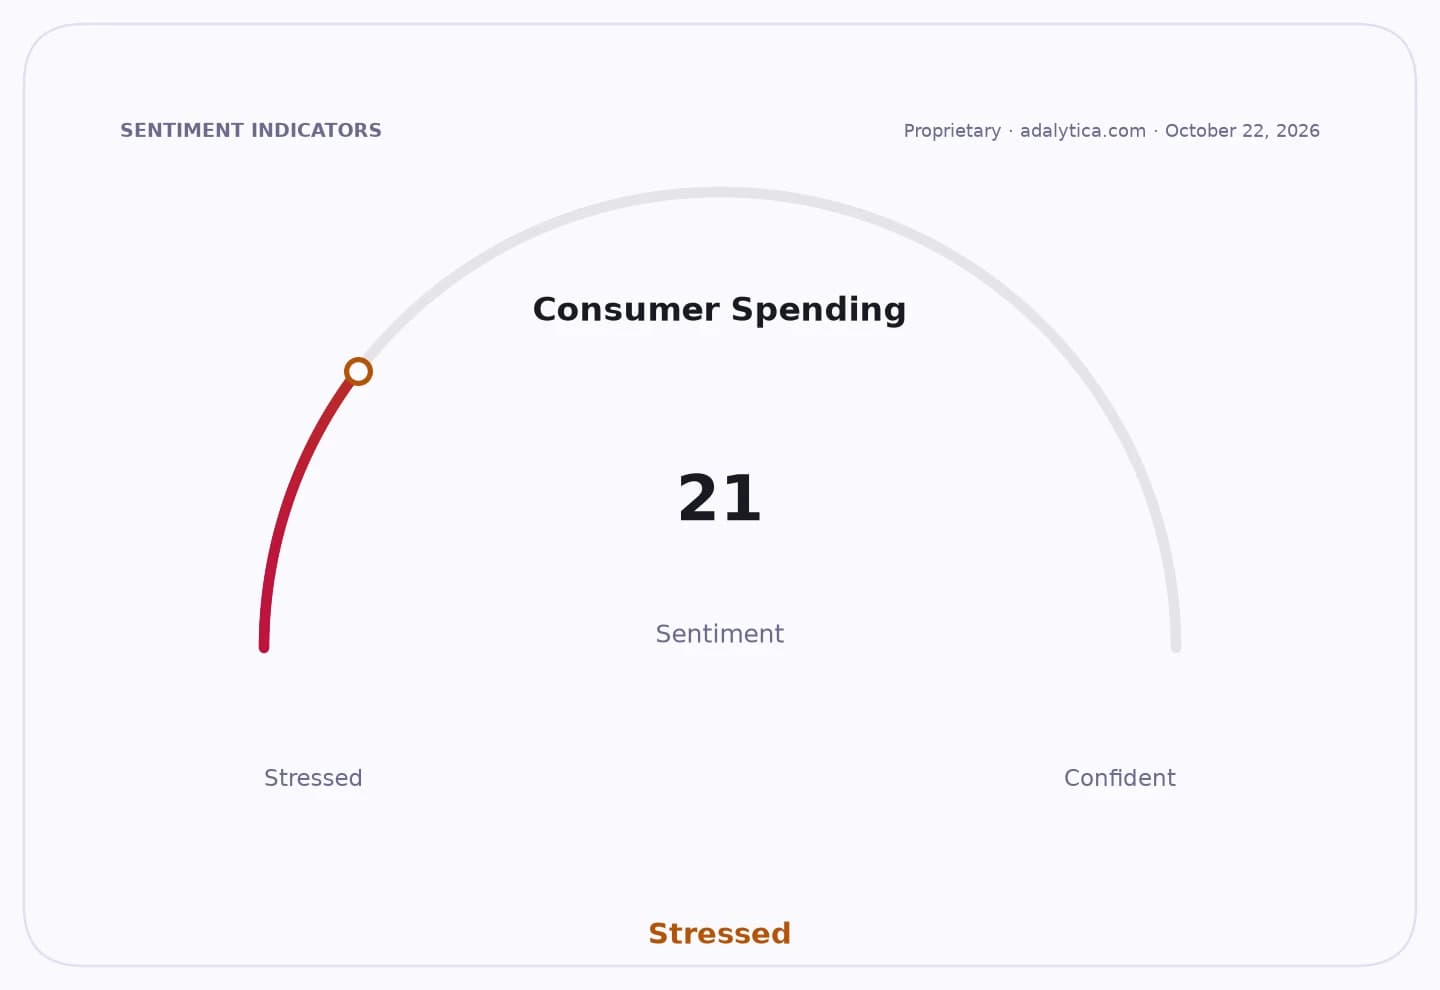
Sentiment IndicatorsⓘProprietary · adalytica.com · October 22, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The slowdown is showing up early in Amazon’s Great Indian Festival and Flipkart’s Big Billion Days, the two marquee sales events that set the tone for the sector. Executives and direct-to-consumer brands told reporters that premium electronics are lagging, a worrying sign because smartphones and electronics can account for more than half of festive GMV on some platforms.
The price shock is doing the damage. Shoppers willing to upgrade are facing a much steeper bill, and that is forcing them to delay purchases, trade down or wait for deeper discounts. In a market where ecommerce growth depends heavily on big-ticket items, even a modest drop in dispatches can quickly flow through to weaker order volumes, slower marketplace take rates and softer logistics demand.
For investors, the message is more important than one weak sales week. It suggests India’s online retail growth is becoming more sensitive to price elasticity just as consumer budgets are being squeezed. That is a direct headwind for platforms such as Amazon and Flipkart, but it also threatens the ecosystem around them — from logistics providers to device makers that were counting on festive demand to clear inventory and keep the premium upgrade cycle intact.
The broader setup is consistent with a consumer that remains selective rather than exuberant. With discretionary spending under pressure, the market should expect more uneven demand across categories, stronger performance in essentials and value-led goods, and a tougher path for premium electronics to reaccelerate without fresh discounting.
The trade from here is straightforward: watch for sharper promotions, lower-margin sales mixes and a possible ripple effect into logistics and marketplace monetization. If price-sensitive festive demand is fading this early, the biggest upside may not be in chasing gross sales growth, but in identifying the winners from a more value-conscious consumer and the losers from a delayed upgrade cycle.
| Entity | Gains | Losses |
|---|---|---|
| Value retailers | ▲Higher traffic for cheaper goods | ▼Less premium mix |
| Amazon India, Flipkart | ▲Festive traffic share | ▼GMV growth, margins |
| Device makers | ▲Deeper discount-led sell-through | ▼Premium pricing power |
| Logistics firms | ▲Parcel volumes if promos lift orders | ▼Dispatch growth if demand stays soft |