Gold in your home is not the problem; proving where it came from is. For Indian households, that distinction matters far more than any headline number, because the tax department’s search-and-seizure rules are designed to target unexplained wealth, not family jewellery that can be traced to savings, inheritance or gifts.
India gold tax rules for home jewellery explained
There is no legal ceiling on how much gold or silver an individual can keep at home, tax experts say. But the Central Board of Direct Taxes has an internal guideline telling officers what jewellery they should ordinarily not seize during a raid: up to 500 grams for a married woman, 250 grams for an unmarried woman and 100 grams for each male family member. Those figures are not a tax exemption, and they are not a blanket shield. They are a practical benchmark for search teams deciding whether jewellery should be left alone if the source can be explained.
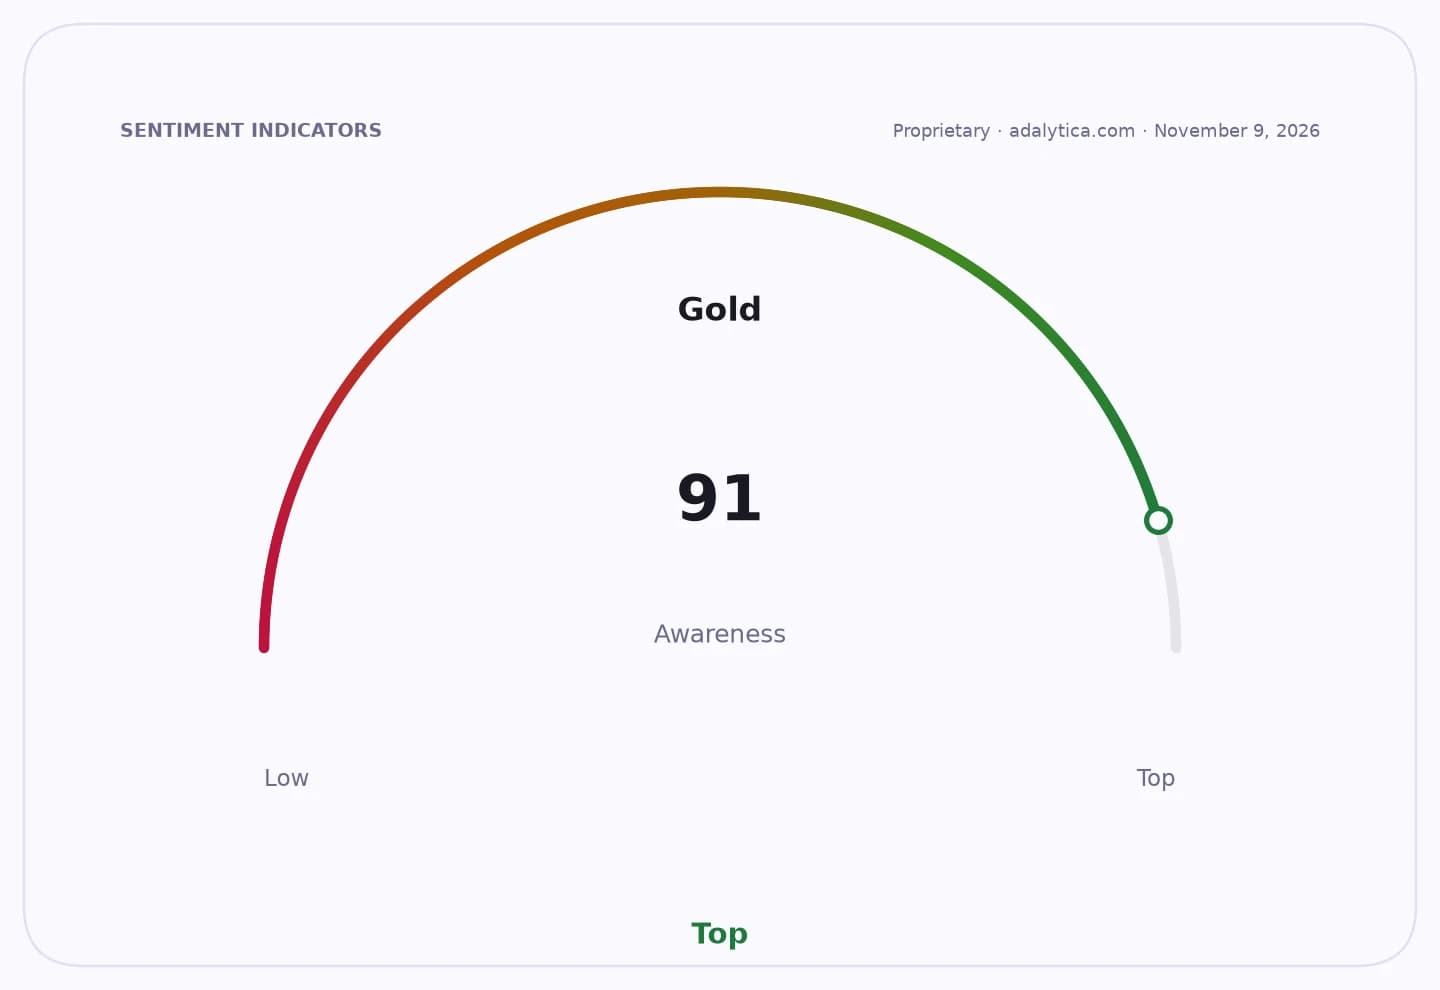
Sentiment Indicators
That is the real economic issue for investors and savers. In a country where gold functions as both cultural asset and emergency liquidity, families need clarity on how the tax net works before they buy more coins, bars or jewellery. The guidance reduces the risk that disclosed household holdings become entangled in disputes during a search, but it also reinforces a simple rule: documentation matters. Bills, inheritance papers, gift records and even evidence of long-standing family customs can make the difference between a temporary seizure and the release of the metal later.
The key point for wealth builders is that these protections are narrower than many people assume. The guideline covers jewellery and ornaments, not necessarily gold bars, bullion or coins. That makes the form of ownership important. A necklace worn at weddings and passed down through generations is treated differently from unexplained bullion sitting in a locker. For tax officers, the question is not just quantity but provenance.
For long-term investors, that distinction also has portfolio implications. Physical gold remains a popular store of value, but it comes with storage, liquidity and compliance questions that exchange-traded gold products do not. That is one reason many savers compare physical gold with gold ETFs: the financial product offers cleaner ownership records, while jewellery carries sentimental and social value but can become harder to defend in a tax inquiry.
The broader lesson is that gold in India is best treated like any other family asset: the better the paperwork, the lower the friction. Households that buy over time, keep receipts and preserve inheritance records are far better positioned than those who rely on memory. For investors, the safest approach is not to panic about the law, but to organise holdings properly and choose the form of gold that matches the purpose. In a market where gold still plays a central role in savings, that is advice worth keeping for years, not days.
| Entity | Gains | Losses |
|---|---|---|
| Households with documented gold | ▲Lower seizure risk | ▼Little downside |
| Taxpayers with unexplained bullion | ▲Potentially spared disputes | ▼Higher scrutiny |
| Gold jewellery holders | ▲Search protection within limits | ▼No automatic exemption |
| Gold ETF investors | ▲Cleaner ownership trail | ▼Less physical possession |