Passenger vehicle retail sales in India are expected to jump 15%-16% in September, a sign that consumer demand is strengthening ahead of the festive season and that the auto market is entering a better stretch after a patchy summer.
India passenger vehicle sales seen rising in September
The estimate, cited by brokerage and research firm Yes Securities, matters because passenger vehicles are one of the clearest gauges of discretionary spending in India. A sustained increase in showroom demand would support automakers’ wholesale shipments, help dealers clear inventory and feed through to parts suppliers, financing companies and insurers. It also suggests that tax relief and seasonal buying are outweighing broader caution in the economy.
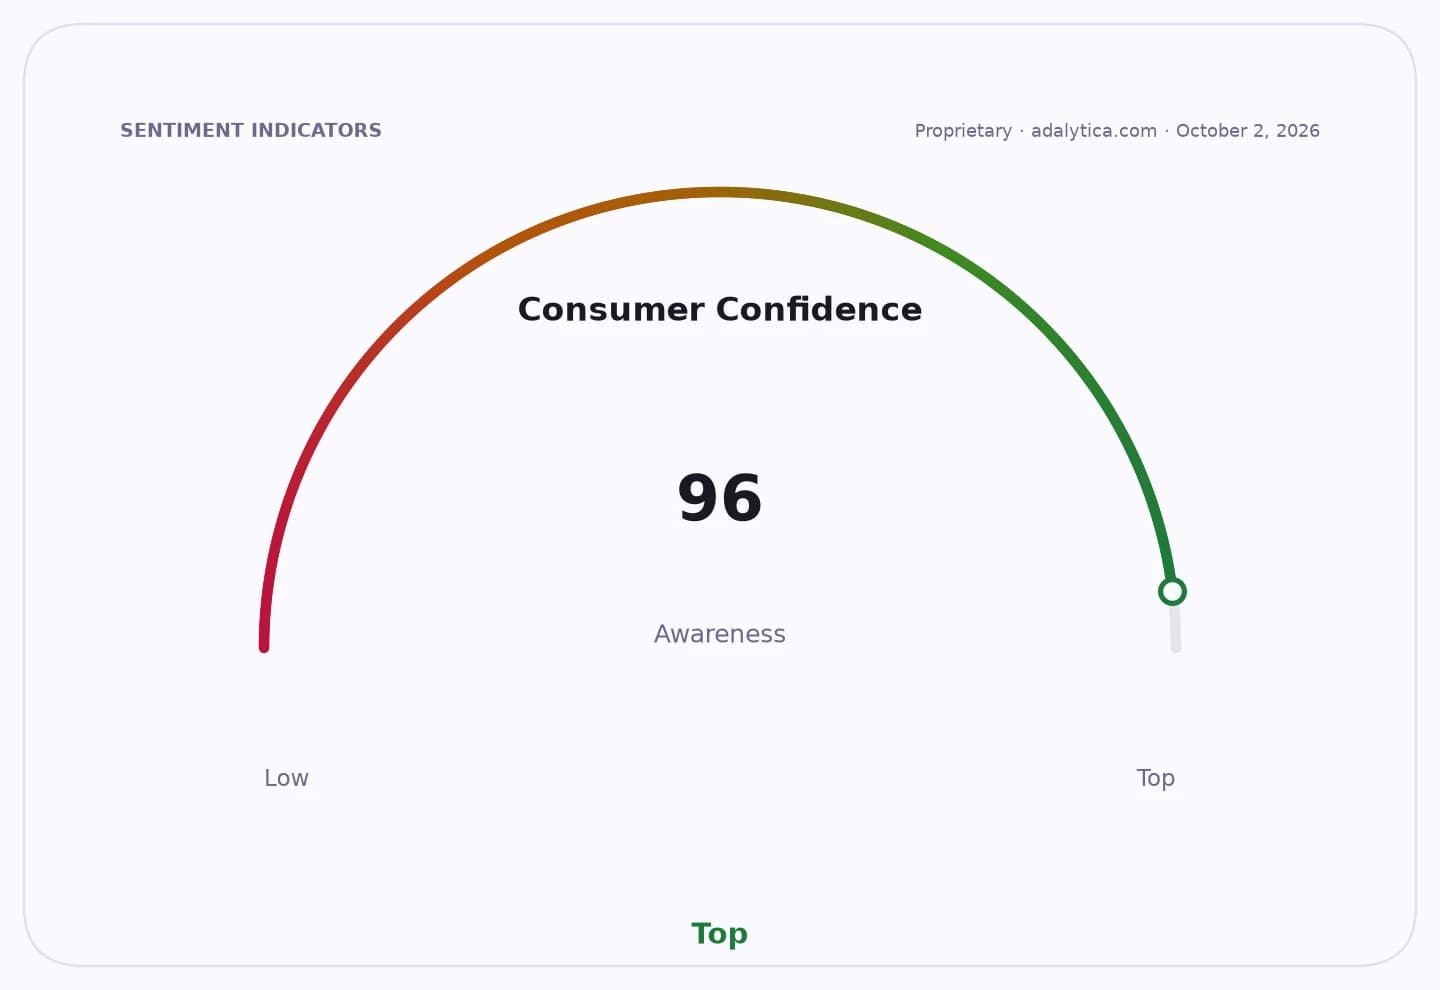
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse

The report points to a market that is already recovering from a softer patch. Industry retail sales have been running in the mid-600,000 unit range in recent months, with August at 646,347 units in the context provided. A September gain of 15%-16% would imply a sharp year-on-year improvement, underscoring that the pickup is not just a one-off monthly bounce but part of a broader restocking and demand cycle tied to festivals.
That backdrop is important for investors because India’s auto sector has been one of the more closely watched consumer themes this year. Strong passenger vehicle demand typically benefits market leaders such as Maruti Suzuki and Hyundai, while stronger showroom traffic also tends to support downstream players in tires, batteries, financing and dealer networks. The flip side is that higher vehicle demand can expose which manufacturers have the right product mix and inventory discipline to convert bookings into deliveries without resorting to heavy incentives.

The market’s reaction has already reflected that divergence. Auto stocks have been mixed, with passenger vehicle names better placed than two-wheeler makers after September sales data in that segment disappointed. In other words, investors are rewarding the parts of the sector linked to urban and higher-income consumers while remaining wary of categories more exposed to rural demand and value-sensitive buyers.
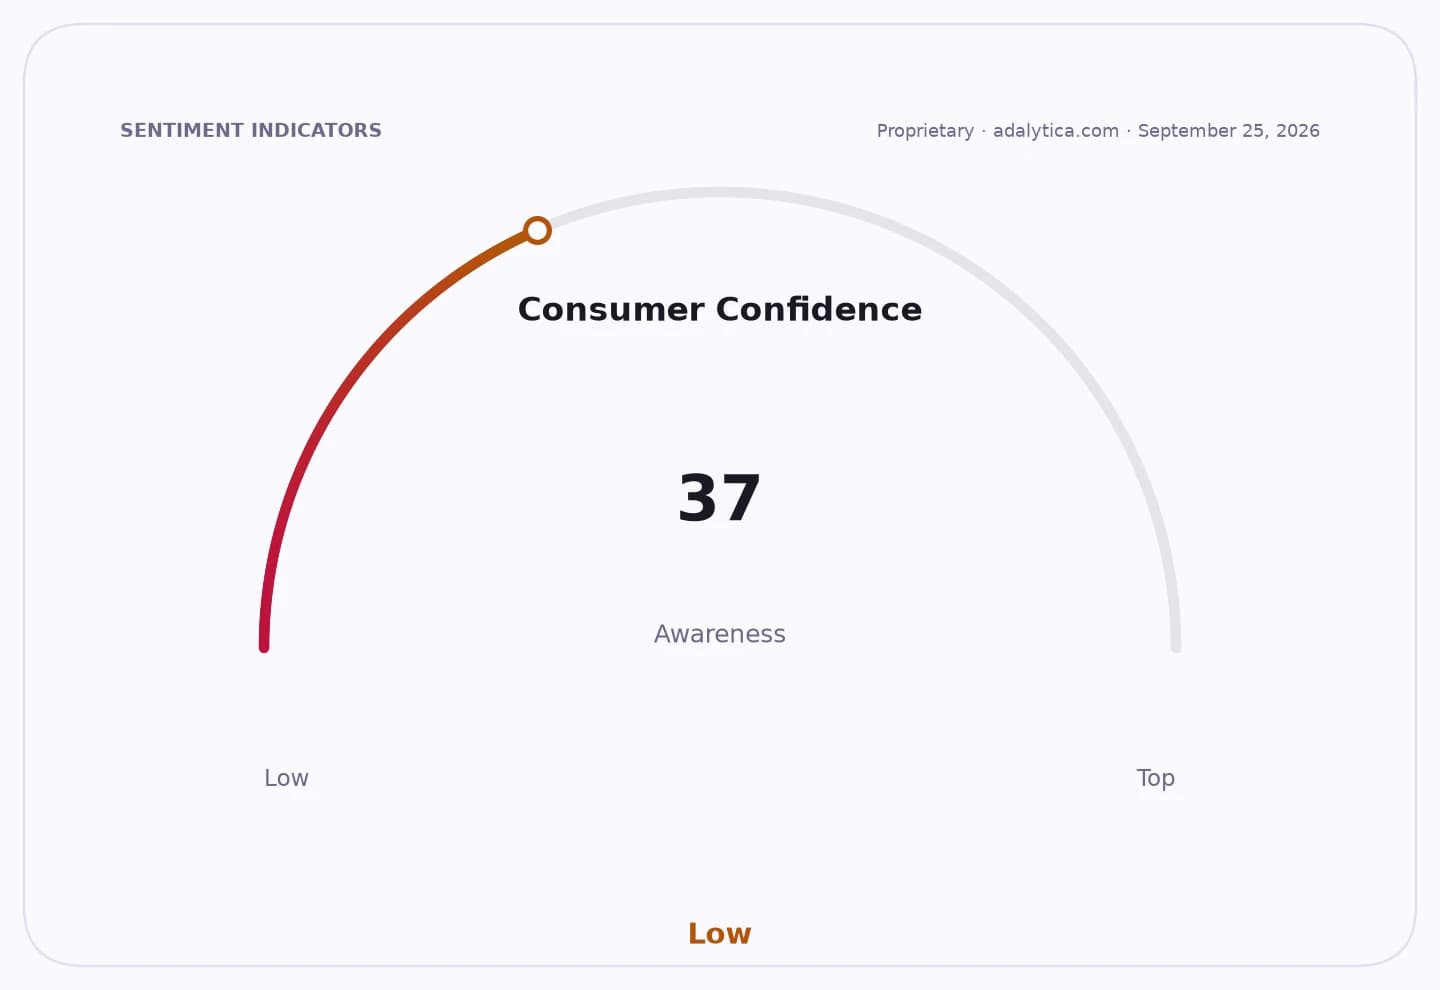
Macro conditions are also helping. Consumer spending sentiment in the Adalytica gauges is neutral but not weak, and the consumer confidence reading sits in positive territory, suggesting households are not pulling back sharply. For automakers, that is enough to support purchases of big-ticket items when combined with festival discounts, easier financing and tax-related tailwinds.
For the sector, the key question is whether September marks a temporary festive-season spike or the start of a more durable upturn. If demand stays elevated into the year-end quarter, manufacturers could see better operating leverage and improved pricing power. If not, the industry may still face pressure from uneven demand across vehicle categories and the risk that buyers simply advance purchases rather than add new volume.
| Entity | Gains | Losses |
|---|---|---|
| Passenger vehicle makers | ▲Higher retail volumes | ▼Inventory overhang risk |
| Dealers | ▲Faster stock turn | ▼Higher working-capital needs |
| Auto suppliers | ▲Better production demand | ▼Weak two-wheeler segment |
| Investors in PV stocks | ▲Stronger earnings outlook | ▼Broader auto cyclicals risk |