Iran’s oil lifeline is running out, and the squeeze is no longer just a geopolitical pressure campaign — it is turning into a broad economic shock that is battering the rial, stoking inflation and eroding Tehran’s ability to fund the state and its security apparatus.
Iran oil exports fall as sanctions tighten

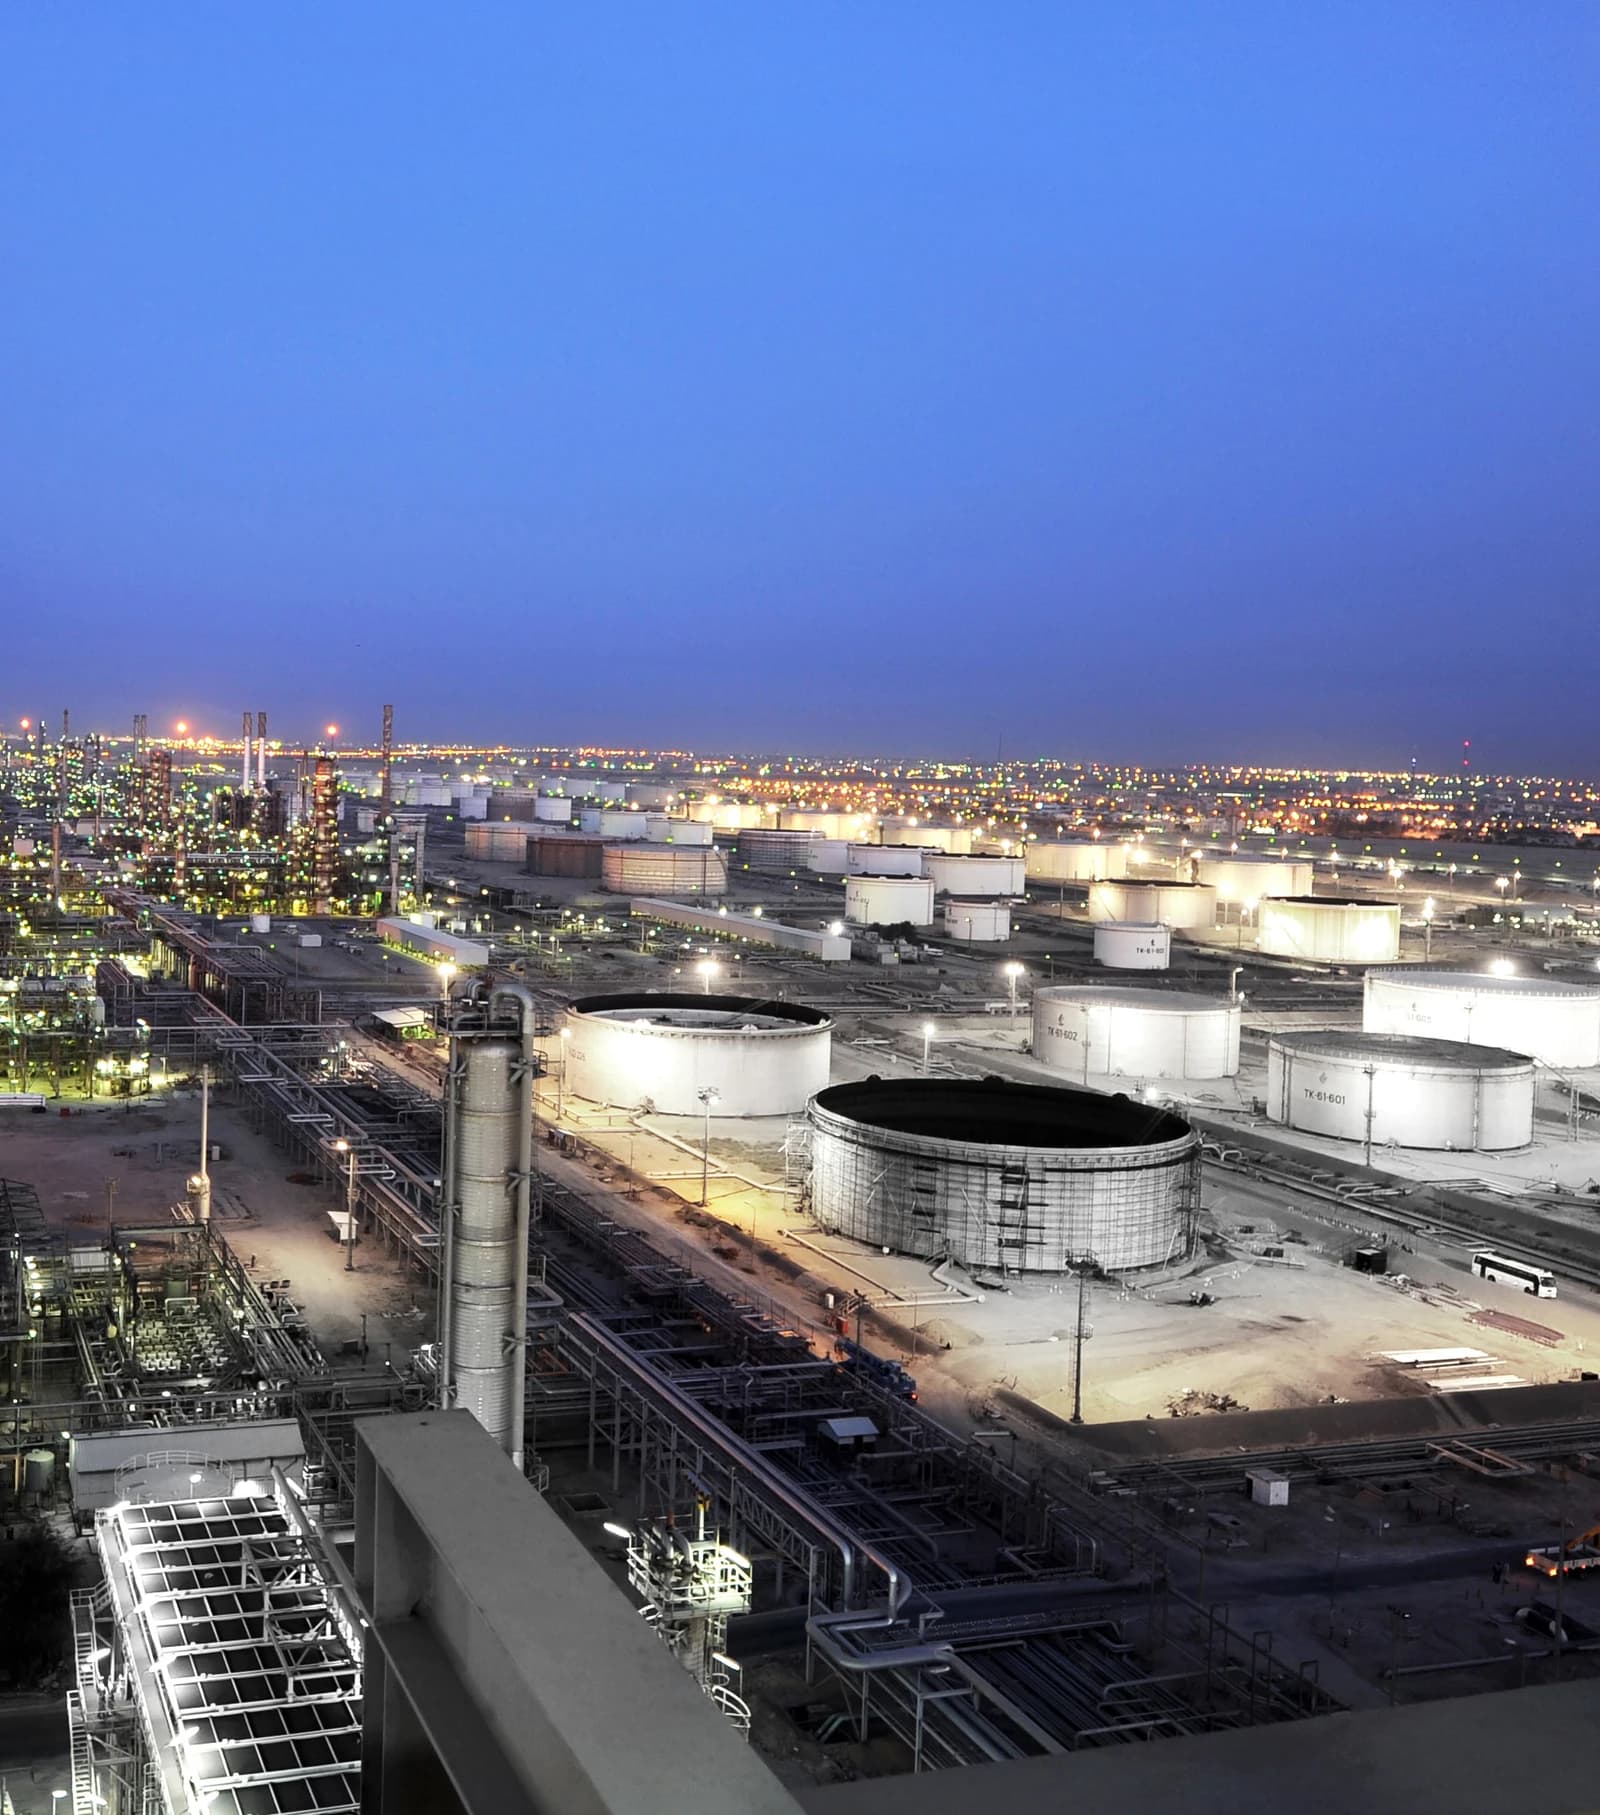
The immediate market significance is simple: Washington’s renewed blockade of Iranian shipping has sharply reduced the barrels Tehran can move to customers, especially China, just as floating storage that had been masking the problem is fast disappearing. Kpler says the volume of Iranian oil held on vessels outside the blockade zone has fallen from about 90 million barrels in mid-July to 29 million barrels, and at an export pace of around 1 million barrels a day, that buffer could be gone by mid-October. Revenue from barrels already delivered may last a little longer, but Kpler expects that cash flow to fade by mid-December as financial sanctions tighten around the banks and intermediaries that still help Iran collect payment.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 10, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse

That matters because oil normally supplies roughly a third of Iran’s government budget and directly supports the armed forces, including the Islamic Revolutionary Guard Corps. When those receipts dry up, the state loses not just foreign exchange but the fiscal grease that keeps imports moving, subsidies paid and security spending intact. The result is already visible in the macro data: official prices are more than 80% above a year ago, the International Monetary Fund sees the economy shrinking 5.4% this year, and the rial has lost nearly 15% against the dollar since President Donald Trump unveiled the latest pressure campaign in August.
For investors, the story cuts two ways. The first is obvious: a tighter Iranian export channel and falling inventories at sea remove barrels from a market that had been counting on stealth supply. That is supportive for crude prices, and the latest moves in oil-related ETFs and benchmarks reflect that tension. WTI has pushed back toward the mid-$90s, with the U.S. Oil Fund at about $150 and technically extended, while Energy Select Sector SPDR has climbed to its highest levels in months. The second effect is less obvious but potentially more durable: if Iran is forced to cut output to avoid filling storage tanks, the market loses not only exports but future production optionality, making any supply disruption in the Gulf more potent.
The blockades are also hitting Iran’s petrochemical industry, its second-biggest hard-currency earner, with Kpler estimating August shipments fell by about two-thirds from the start of 2026. Overland trucking and rail are only partial workarounds, and at roughly 40,000 barrels a day by truck, they are a rounding error versus prewar exports near 2 million barrels a day. That means Tehran is moving from a hidden-export model to an actual supply constraint, a much more painful phase for an economy already starved of dollars.
There is still a geopolitical wild card. Pressure has not yet forced a policy reversal, and Gulf officials warn Tehran may answer by leaning harder on proxies such as the Houthis, raising risks for Red Sea shipping and infrastructure around Bab el-Mandeb. But the investment takeaway is clear: the market underestimates how quickly sanctioned oil systems can break once floating inventories and payment channels are both targeted. For now, the trade is to stay long energy and related infrastructure beneficiaries, while recognizing that Iran’s shrinking export machine may keep adding fuel to crude volatility well into year-end.
| Entity | Gains | Losses |
|---|---|---|
| Brent crude / WTI | ▲tighter supply | ▼sanctions-drained barrels |
| Energy equities / XLE | ▲higher realized prices | ▼policy-driven volatility |
| Iran government / IRGC | ▲none | ▼budget revenue, FX reserves |
| China refiners / buyers | ▲bargain supply risk premium | ▼reliable discounted crude |