IREN’s big story is no longer bitcoin mining. It is becoming an AI infrastructure company, and investors are being forced to decide whether that transformation deserves a premium or whether the stock has already run too far, too fast.
IREN AI cloud pivot and stock pullback
That matters because the market has been rewarding a simple mining story for years, but the economics of AI cloud are very different. Mining revenue rises and falls with bitcoin prices, network difficulty and power costs. AI cloud, by contrast, can create longer-duration, higher-value contracts with customers that care more about reliable compute than daily crypto volatility. If IREN can keep shifting its mix toward AI services, the company’s cash flow profile could become far more durable.
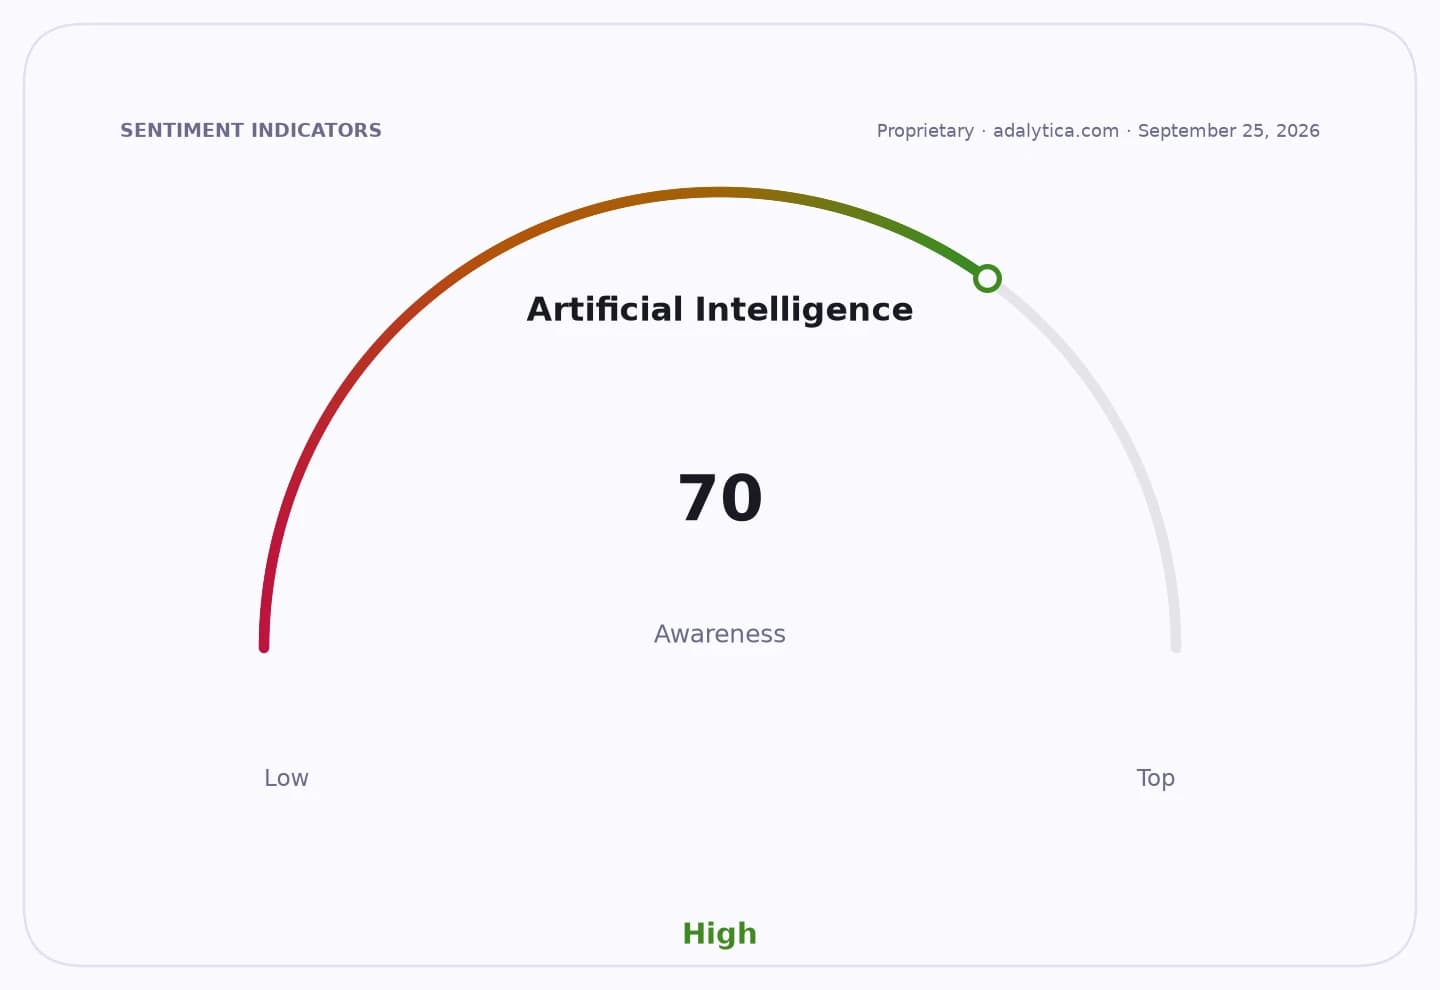
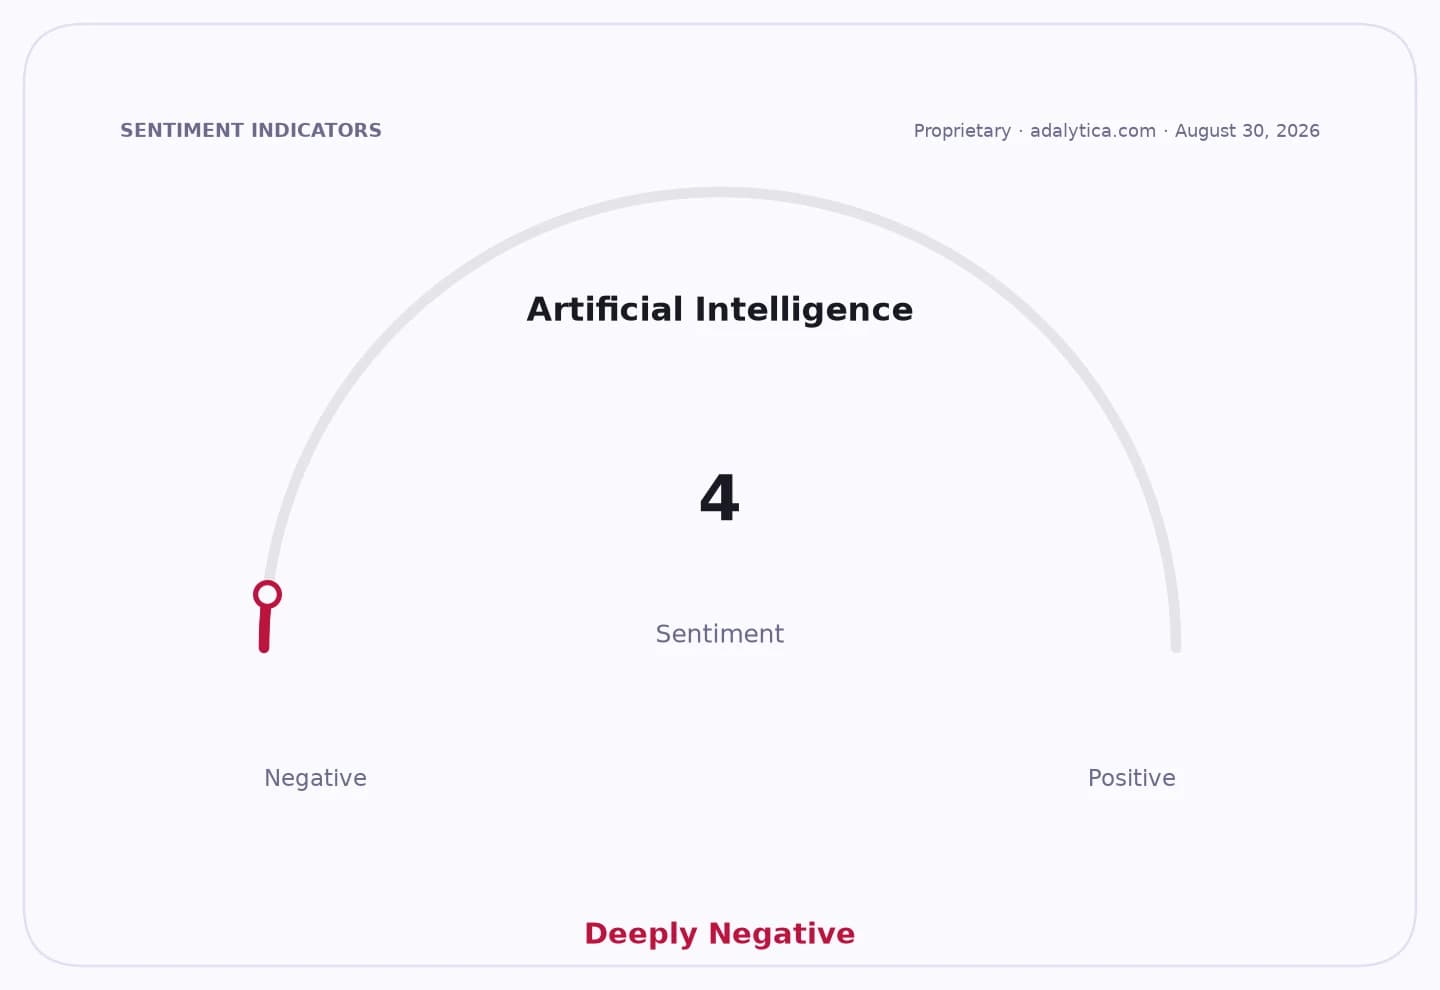
Sentiment IndicatorsⓘProprietary · adalytica.com · August 30, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The stock’s recent price action shows just how much expectation is already baked in. IREN surged to as high as 76.41 in early November before sliding back to 35.45 by Aug. 28, while the 50-day moving average sits above the latest price, a sign momentum has cooled. The move also comes after a sharp reversal in standard technical indicators such as RSI readings and MACD, suggesting traders have backed away even as the longer-term transformation remains intact.
That tension is exactly why IREN matters to investors. This is not just a bitcoin miner trying to survive the next cycle. It is trying to own a piece of the AI buildout, where demand for power, land and data-center capacity is exploding. Companies with existing infrastructure, cheap electricity and the ability to deploy high-performance computing fast have a real chance to compound value for years if they execute. IREN’s move into AI cloud puts it in the same broad strategic lane as other crypto miners pivoting toward HPC and data-center leasing.
Artificial Intelligence vs IRENadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
The risk, of course, is that the market is now demanding proof, not just a story. IREN’s 10-K itself flags that its AI cloud business has a shorter operating history than some rivals and may not prove profitable or scalable. That caution matters because the economics of building AI capacity can be brutal: capital spending is heavy, competition is rising, and customers have plenty of alternatives. A company can win the narrative and still lose money if it builds too much too soon.
Still, for long-term investors, the bigger takeaway is encouraging. The age of pure-play bitcoin mining is giving way to a more valuable model: owning infrastructure that can serve whichever workload pays best. If IREN can keep converting its electricity advantage into contracted AI demand, the business could look less like a speculative miner and more like a digital-utility platform with real optionality. That is the kind of shift worth watching, and potentially worth owning patiently for the next three to 10 years.
| Entity | Gains | Losses |
|---|---|---|
| IREN AI cloud | ▲Higher-margin compute demand | ▼Execution risk and capex burden |
| IREN bitcoin mining | ▲Diversification away from crypto swings | ▼Less pure mining leverage |
| Long-term investors | ▲Potential multiple rerating | ▼Near-term volatility |
| Bitcoin-mining peers | ▲Validation of AI pivot strategy | ▼Pressure to follow or fall behind |