Italy’s manufacturing sector is proving more resilient than expected, but the recovery remains vulnerable to renewed energy shocks, uneven domestic demand and geopolitical uncertainty.
Italy manufacturing revenue rises as energy risks remain
Oil WTI
A new report from Intesa Sanpaolo and Prometeia shows real manufacturing revenue rose 0.7% in the first seven months of 2026 and is on track to end the year up 0.8%, after three straight years of contraction. That marks a meaningful stabilization for one of Europe’s most important industrial bases, especially after the escalation in Middle East tensions raised concerns about a sharper hit to energy-intensive producers.
Sentiment Indicators
The recovery matters economically because manufacturing still anchors Italy’s export performance, investment cycle and industrial employment. Nominal turnover is growing faster, up 2.7% in the first seven months, largely because producer prices have accelerated as energy and raw material costs rebounded. That means the sector’s headline revenue is improving, but the underlying volume recovery is still modest.
The report points to a record annual manufacturing turnover of about €1.168 trillion, up roughly €257 billion from 2019 and 4.1% above 2025. Yet that figure also reflects inflation, not just stronger output. For policymakers and business leaders, the distinction is crucial: higher sales do not automatically translate into stronger margins or broader industrial health when input costs remain volatile.
Italy’s relative resilience stands out in a weak European environment. Industrial production rose 0.4% in the first eight months of 2026, compared with a 2.5% decline in Germany and a 0.2% gain in France. Spain was stronger at 0.9%, but Italy’s performance suggests its industrial base is currently holding up better than much of the region’s, helped by a rebound in intra-EU trade.
That external demand has become the main support for exports. Shipments of manufactured goods rose 3.9% in value in the first seven months, with European markets contributing 2.1 percentage points, led by Germany, France and eastern Europe. The trade surplus is still expected to edge higher to €114.5 billion in 2026 from €112.8 billion last year, even as import growth is projected to outpace export growth in volume terms.
The sector split is telling. Investment-linked industries are leading the recovery, while consumer-facing businesses remain under pressure from inflation and weaker household purchasing power. Elettrotecnica, electronics, pharmaceuticals and machinery are among the best performers. By contrast, appliances, furniture, fashion and mass consumer goods are still in negative territory, as are intermediate chemicals, which are undergoing restructuring across Europe.
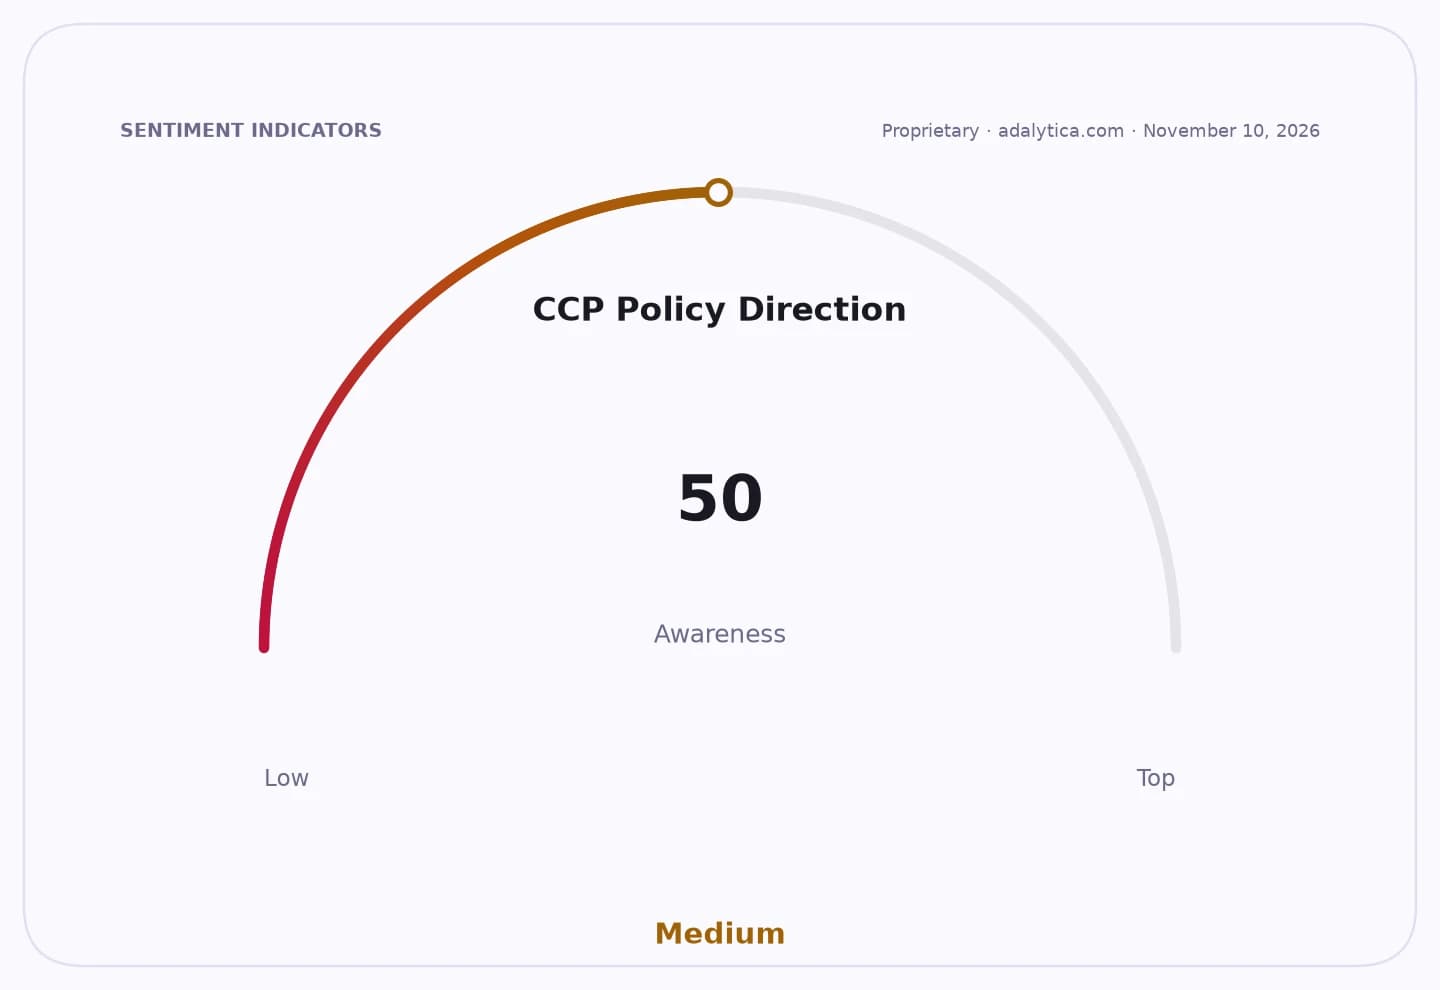
Energy remains the key risk factor. WTI crude has been trading near $88, well above the 50-day moving average and still elevated despite recent volatility, while U.S. oil trade sentiment has shifted into fear territory in Adalytica’s gauges. That underscores how quickly geopolitical stress can feed into input costs for industry, even if oil prices are no longer at the peaks seen in earlier crises. For Italian manufacturers, the near-term question is not whether demand exists, but whether margins can absorb another round of cost pressure.
The outlook for 2027 and 2028 is for continued growth, but only at a subdued pace, with real turnover expected to rise 0.8% and 0.9% respectively. That suggests the sector is moving out of contraction, not into a broad-based boom.
For investors, the message is twofold. Export-oriented capital goods, electrical equipment, pharma and automation-related companies look better placed to benefit from Italy’s industrial upturn, while consumer discretionary manufacturers and chemicals remain more exposed to margin pressure and weak final demand. The broader narrative is that Italian manufacturing is stabilizing, but the recovery is still being shaped by energy costs, European trade flows and the geopolitical backdrop rather than by a decisive surge in domestic demand.
| Entity | Gains | Losses |
|---|---|---|
| Export-oriented manufacturers | ▲Stronger EU demand | ▼Currency and input-cost volatility |
| Investment goods sectors | ▲Order growth | ▼Dependence on capital spending |
| Consumer-facing producers | ▲— | ▼Weak household demand |
| Italy’s industrial base | ▲Output resilience | ▼Margin pressure from energy costs |