Japan’s new prime minister is trying to square a politically popular tax cut with a financial market that still wants proof Tokyo can pay for it.
Japan Tax Cut Debate Hits Bonds and Yen
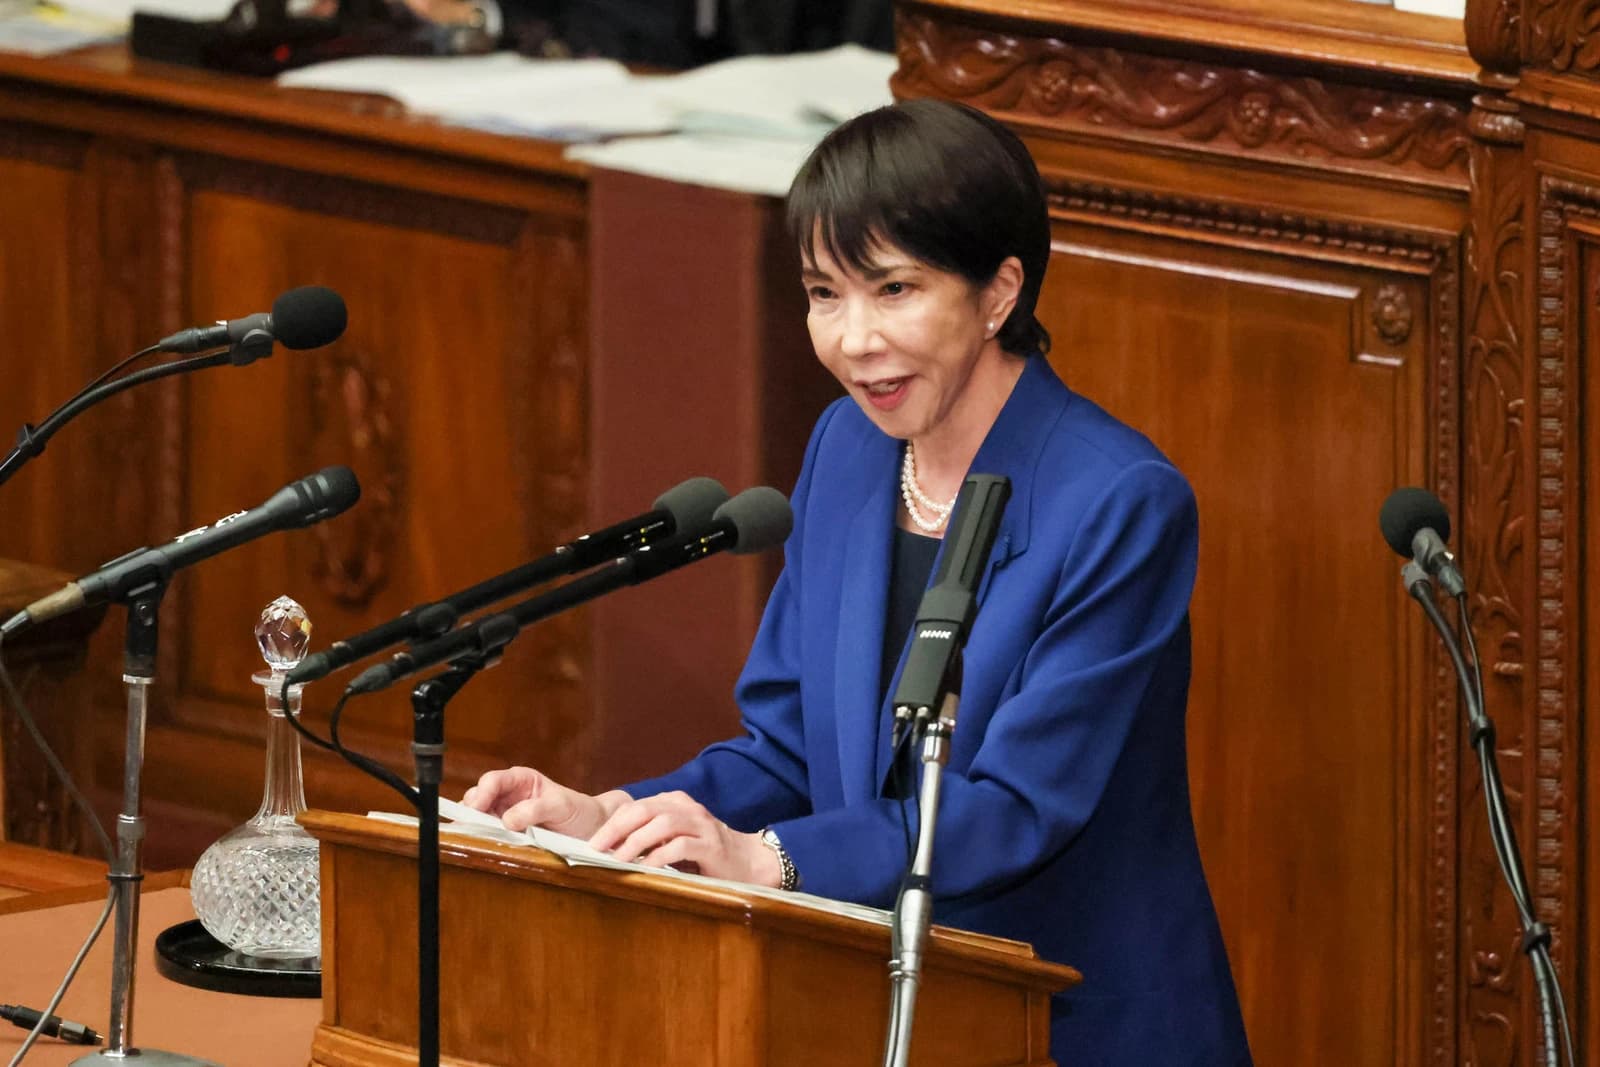
Prime Minister Sanae Takaichi’s emphasis on lowering the consumption tax, especially on food, matters because it goes to the heart of Japan’s next policy fight: how to cushion households struggling with inflation without unsettling bond investors who already watch the government’s fiscal path closely. In a country where consumer prices have climbed sharply and the cost of daily necessities remains a pain point, even a narrowly targeted tax cut could provide relief. But any reduction also risks widening the budget gap unless the government can show a credible offset.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That is why Takaichi’s repeated stress on “securing market confidence” is just as important as the tax-cut message itself. Japan cannot afford to look as if it is opening the fiscal taps indiscriminately. The 10-year Japanese government bond yield has been hovering around 1.3%, a reminder that borrowing costs remain low by global standards, but not insignificant for a government that carries one of the heaviest debt loads in the developed world. Investors will want to know whether a food-tax cut is a temporary consumer measure, a broader shift in fiscal policy, or the first step toward more aggressive stimulus.
Markets, for their part, have already been signaling that Japan remains investable, but not complacent. The Nikkei 225 has rallied to record territory, closing around 69,947 on Oct. 5, while the EWJ Japan ETF has climbed toward $99. That suggests global investors still like the country’s corporate earnings, shareholder returns and governance reforms. But they are also paying attention to policy risk. A consumption-tax cut could support domestic demand and retail spending, which would be positive for Japanese consumers and companies tied to local consumption. At the same time, it could pressure the yen if traders conclude fiscal discipline is being loosened, and the yen has already been weak by historical standards at roughly 158 per dollar.
For investors, the key question is not whether a tax cut is good or bad in isolation. It is whether it fits into a longer-term framework that supports earnings without undermining macro stability. If Takaichi can deliver relief while preserving confidence in Japan’s debt sustainability, that would be a constructive combination for equities, especially domestically oriented names. If the policy tilts toward open-ended stimulus, bond markets could become less forgiving, and that would eventually spill into equities too.
The broader narrative is straightforward: Japan is still trying to turn a fragile recovery into something sturdier, and fiscal policy is now back at the center of that effort. Consumers want relief, markets want discipline, and Takaichi is trying to satisfy both. For long-term investors, that makes Japan worth watching closely rather than chasing blindly. The opportunity is real, but so is the need for selectivity and patience.
| Entity | Gains | Losses |
|---|---|---|
| Japanese households | ▲Lower food costs | ▼Less tax revenue if not offset |
| Domestic retailers | ▲Better spending power | ▼Margin pressure if policy disappoints |
| Japanese government bonds | ▲Confidence if cuts are small and funded | ▼Selloff risk if deficits widen |
| Equity investors in Japan | ▲Support for consumer demand | ▼Higher policy uncertainty |