Libya’s oil paradox is not just a curiosity — it is a costly economic leak that helps explain why one of Africa’s most resource-rich countries still spends billions of dollars on imported fuel. For investors, the story matters because it shows how a lack of refining capacity can turn a crude exporter into a buyer of gasoline and diesel, leaving the country exposed to global price swings and draining cash that could otherwise support growth, infrastructure and public finances.
Libya oil imports expose refining gap
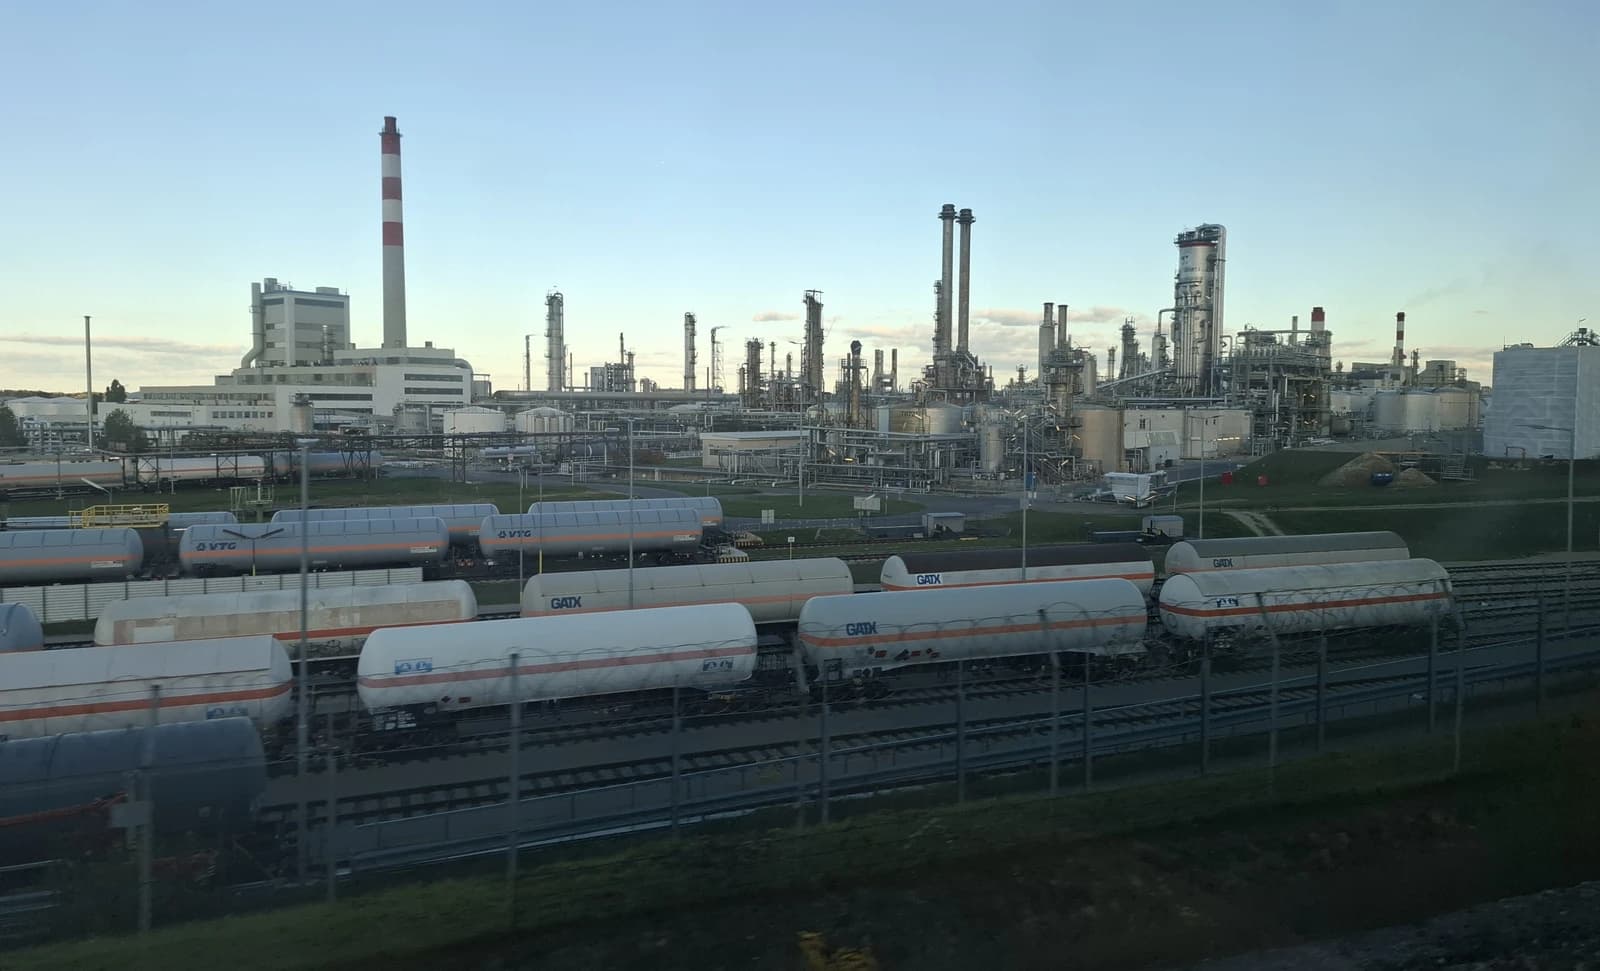
The core problem is simple: Libya produces large volumes of crude, but it cannot turn enough of that crude into the fuels its economy actually uses. That forces the country back into international markets to buy diesel and gasoline at global prices, even when oil prices are elevated. In other words, Libya captures only part of the value chain. It sells raw barrels, but imports the finished products that households, transport fleets and generators consume every day.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 14, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That imbalance matters economically because fuel imports act like a hidden tax on the state. Every dollar spent overseas on refined products is a dollar not spent at home on power systems, refining upgrades, roads or hospitals. It also makes the budget more fragile. When crude prices rise, Libya may earn more from exports, but the cost of imported fuels can rise too, blunting the benefit. The country is then caught between two markets at once: the crude market it supplies and the products market it depends on.
The wider market backdrop reinforces that risk. Oil prices have remained elevated by historical standards, with Brent around $106 and U.S. crude near $95, according to the price data supplied. Standard technical measures such as the 50-day and 200-day moving averages show both benchmarks still trading well above longer-term trend levels, underscoring that energy remains expensive even after recent pullbacks. That keeps the import bill painful for countries without enough domestic refining capacity.
For investors, Libya’s fuel gap is a reminder that the real value in oil is often downstream. Refiners, fuel distributors and integrated majors can benefit when crude-producing countries are forced to import products at premium prices. The same dynamic helps explain why global downstream margins can strengthen in supply-constrained markets. It also highlights why energy stocks with refining exposure — rather than pure upstream producers — can sometimes perform better in periods of supply stress.
There is also a geopolitical angle. Fuel shortages and import dependence increase pressure on governments to secure supplies, subsidize prices or tap reserves. Across markets, that has fed volatility in transport, aviation and consumer spending. High fuel costs ripple through everything from shipping to food inflation, and Libya’s case is an extreme example of how energy bottlenecks can weaken an entire economy even when the country sits on abundant oil reserves.
The long-term fix is obvious, but not easy: Libya needs more reliable refining, storage and logistics infrastructure, plus a political environment stable enough to keep it running. Until that happens, the country will keep exporting crude and importing the fuel it should be making at home. For investors, the lesson is broader: in energy, capacity and infrastructure matter as much as reserves. That is worth watching.
| Entity | Gains | Losses |
|---|---|---|
| Global refiners | ▲Stronger product margins | ▼None from Libya’s imports |
| Libya’s consumers | ▲More fuel availability | ▼Higher domestic fuel costs |
| Libya’s state finances | ▲Crude export receipts | ▼Billions spent on imports |
| Oil exporters with refining capacity | ▲Extra demand for products | ▼Pure crude producers lacking downstream assets |