Luxury travel is proving far more resilient than the summer headlines suggested, and that matters because premium clients are still paying for expertise, reliability and access even as broader holiday demand becomes more selective.
Luxury travel demand holds up in Italy and Dubai
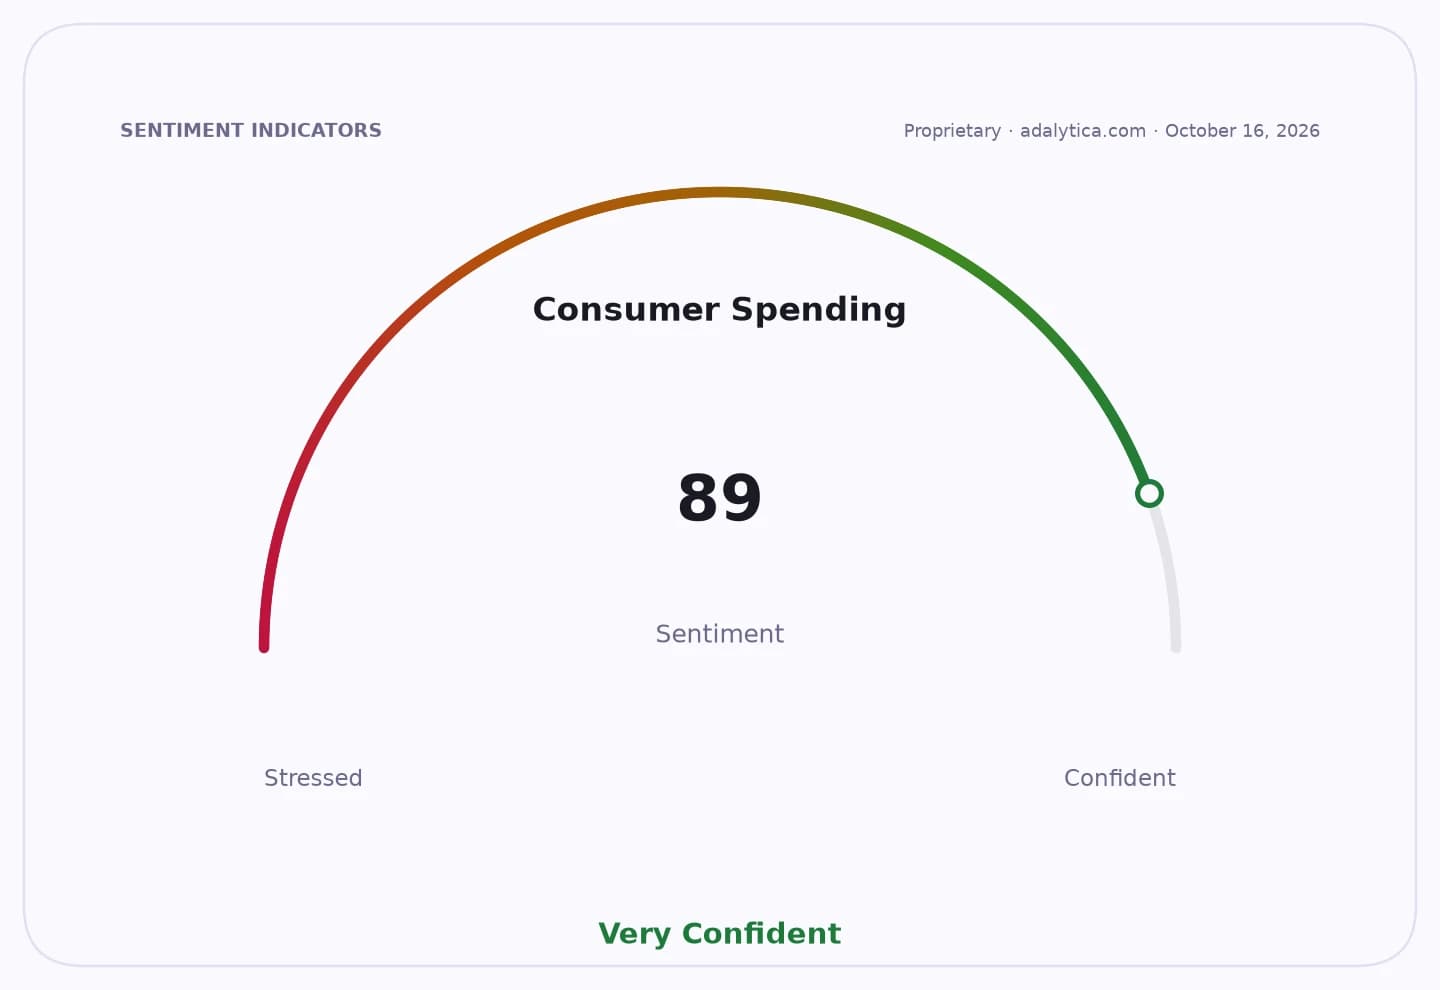
The clearest message from the market at Cristanini Viaggi in Novara is that affluent travelers are not retreating — they are changing how they buy. Sandro Cristanini says this summer Italy won out, with strong demand for Sardinia, Sicily and city breaks, while autumn bookings continued to favor the Indian Ocean, the United States and major capitals. That shift toward shorter, diversified trips reflects a high-spending customer base that is willing to spend, but only when the product feels secure, seamless and worth the premium.
For investors, the significance is twofold. First, luxury travel remains a pricing power story, not a volume story. Travelers in this segment are less focused on the fare and more focused on the total experience, from airline choice to airport handling to on-the-ground support. Cristanini’s decision to favor scheduled carriers, boarding via jet bridge and transfers by shuttle rather than exposed tarmac operations speaks to what the market is really buying: reduced friction. That is an advantage for operators that can control service quality, and a warning sign for low-touch players competing only on price.
Second, the data points to a broader rebound in destination-specific demand that can favor premium hotel chains, tour operators and travel platforms with strong inventory in the Mediterranean, the Indian Ocean and major urban markets. The return of the UAE is especially notable. Cristanini says Dubai is functioning well again, with hotels, restaurants and tourist sites operating normally and foreign visitors back, even if Italian demand remains soft. That suggests geopolitical stability is already being translated into booking behavior, which is exactly the kind of second-order recovery investors should watch.
The other structural theme is the growing role of the agent. Cristanini says today’s traveler arrives better informed thanks to AI, but that does not eliminate the need for human advice — it raises the value of it. In a market crowded with digital content, the premium is shifting to curation, problem-solving and trust. That is an important tailwind for high-end agencies and a reminder that technology may compress some booking functions while strengthening the case for advisory service where the stakes are high.
That helps explain why the luxury travel trade remains relatively constructive even as consumers face service disruptions, delays and security concerns. The market is underestimating how much wealthier travelers will pay to avoid uncertainty. In our view, that supports a bullish case for premium travel names tied to quality experiences, resilient destinations and the infrastructure that makes elite travel frictionless.
The next catalyst is likely to come from continued reopening in geopolitically stable destinations and from the winter booking cycle, where the willingness of affluent customers to trade up should remain visible. For investors, the takeaway is clear: own the picks-and-shovels of premium travel, not the commoditized traffic.
| Entity | Gains | Losses |
|---|---|---|
| Luxury travel agencies | ▲Higher fees, loyal clients | ▼Price-only competitors |
| Premium airlines | ▲Yield from service-focused demand | ▼Low-cost carriers on service disputes |
| Mediterranean destinations | ▲Short-haul luxury bookings | ▼Undifferentiated mass-market resorts |
| UAE / Dubai tourism | ▲Return of foreign visitors | ▼Destinations lacking stability |