Malaysia’s latest batch of corporate updates points to the same investable theme: capital is flowing into healthcare, data-enabled industrial technology, energy infrastructure and logistics, even as smaller companies clean up balance sheets and monetize assets. For investors, that mix matters because it suggests the market is still underpricing the second-order winners from Malaysia’s domestic buildout and regional digitalization.
Malaysia corporate updates highlight healthcare and logistics
The most economically significant development is not any single announcement, but the breadth of activity across sectors that typically lead an expansion cycle. Sunway Healthcare is moving into a 325-bed private hospital in Putrajaya through a 60:40 joint venture with Putrajaya Holdings, a project that will not break ground until late 2027 but underscores a long-duration healthcare capex pipeline. That is the sort of asset build that can support earnings visibility for years, especially as Malaysia leans into higher-value private care and the region’s aging population keeps demand rising.
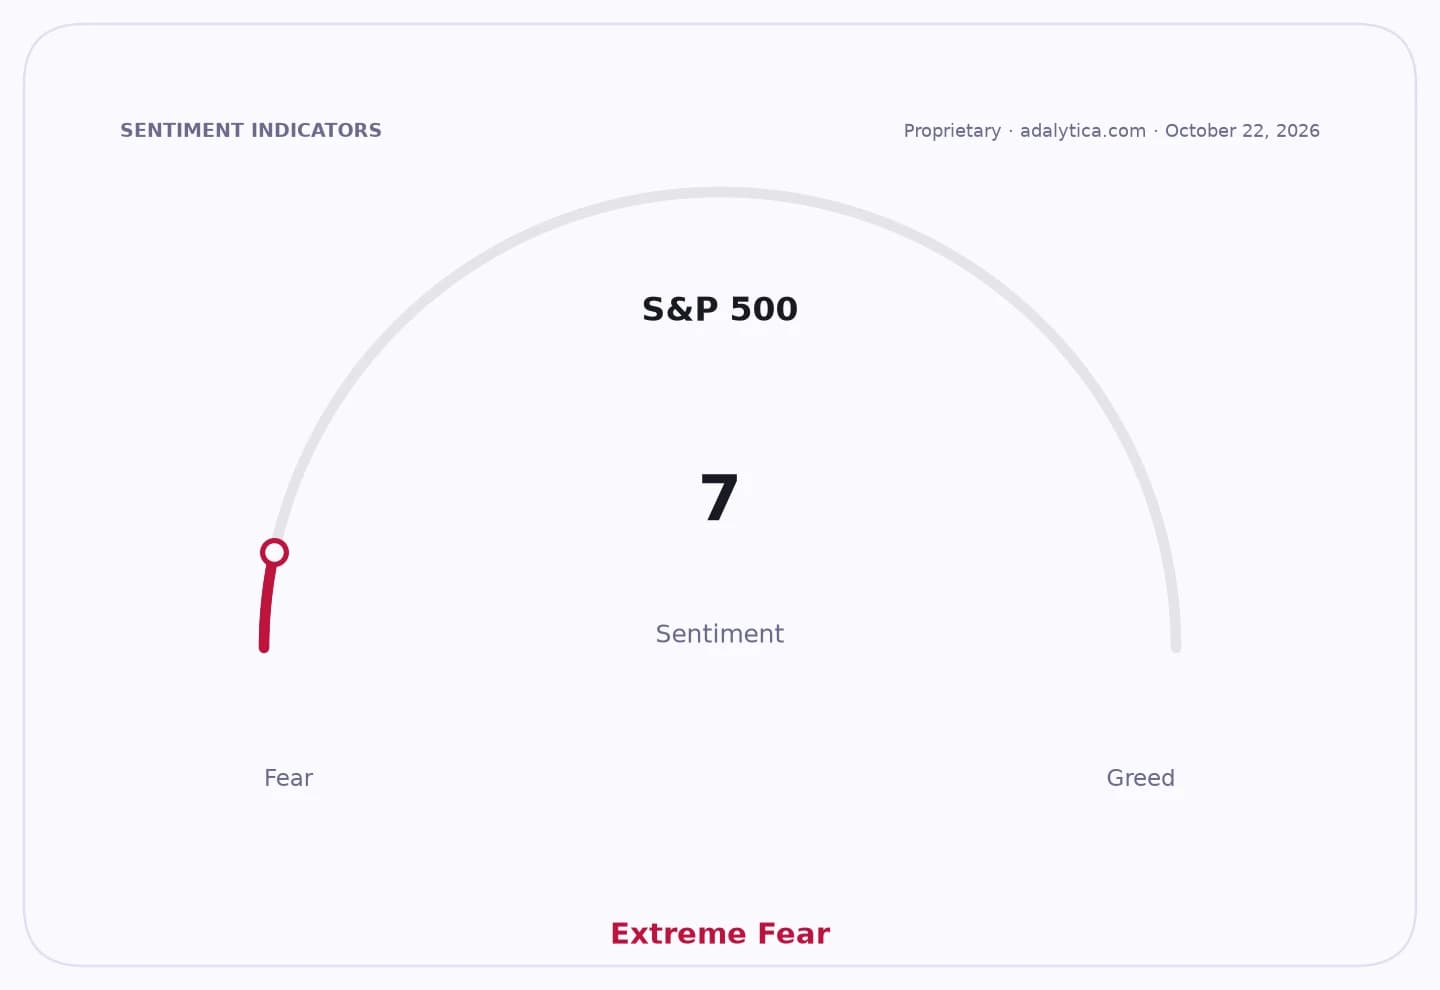
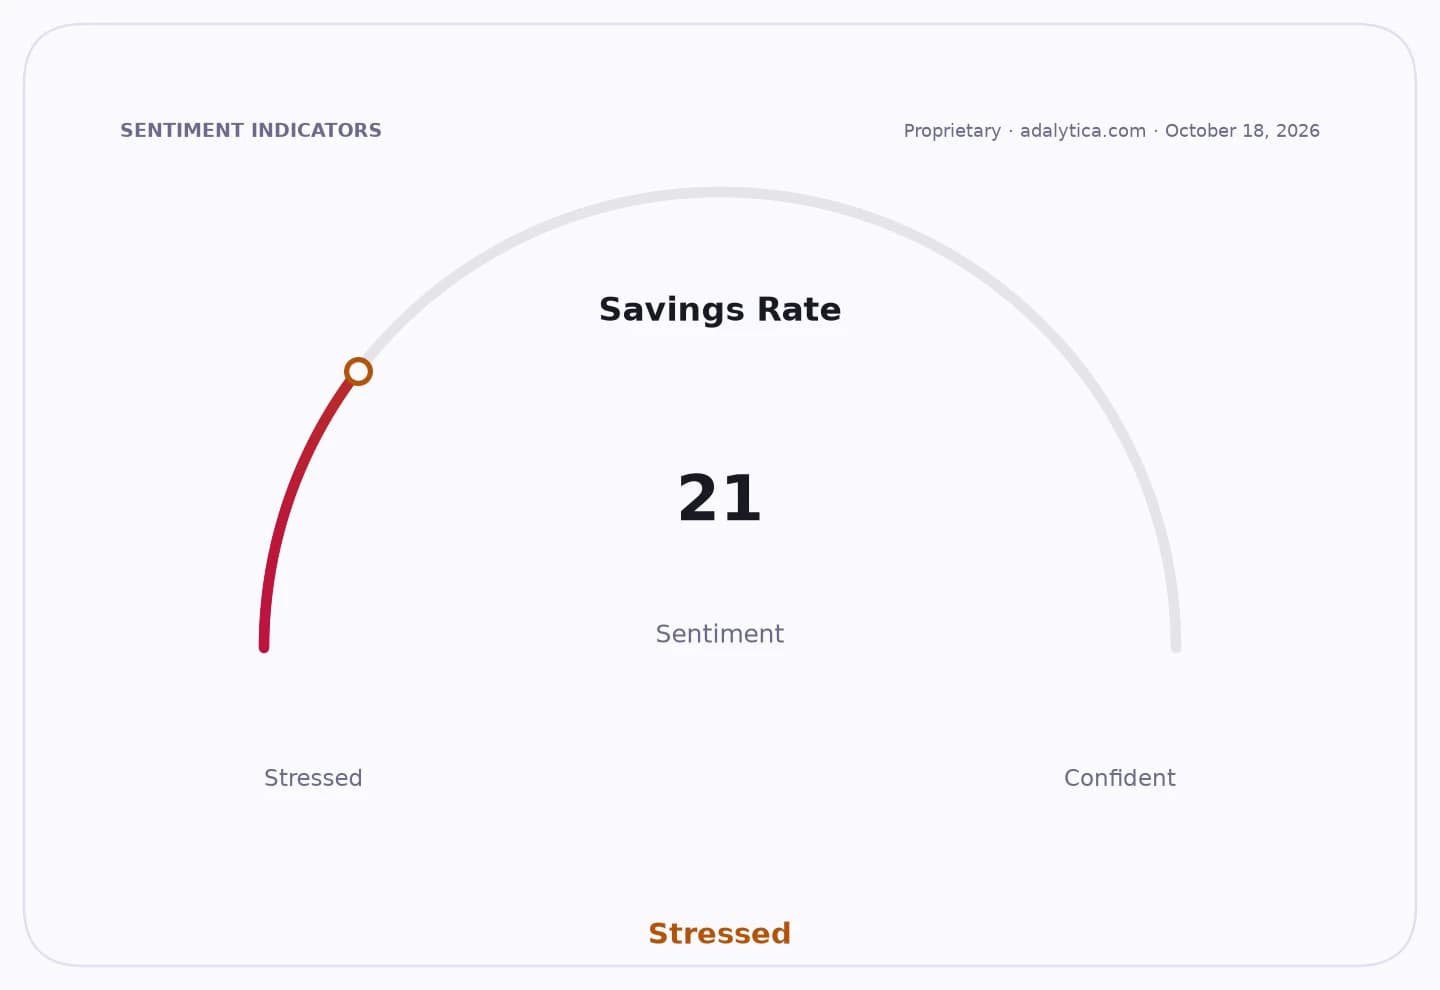
Sentiment Indicators
At the same time, SkyeChip’s partnership with Japan’s SAIMEMORY, a SoftBank subsidiary, puts a Malaysian semiconductor-adjacent name into the AI memory race. That is strategically important because the market remains fixated on chip designers and foundries while underappreciating the ecosystem around AI memory, power efficiency and engineering services. If this collaboration leads to commercial traction, it could open a far more scalable niche than the market is currently giving local design and support players credit for.
The infrastructure and utilities angle is just as compelling. Tenaga Nasional’s work with MRT Corp on renewable energy, EV charging and energy-efficient rail infrastructure, starting with the Johor Bahru-Singapore RTS Link, reinforces a broader electrification theme. This is not just about one rail project; it is about the capex multiplier that follows when utilities, transport operators and equipment suppliers align around a cross-border corridor. That benefits contractors, component makers and REITs tied to logistics and industrial assets, while strengthening the case for Malaysia’s grid and transit modernization.
That backdrop helps explain why names such as AME REIT and CLMT continue to matter. AME REIT reported an 11.5% rise in quarterly net property income to RM16 million, helped by higher rent and newly acquired properties, while CLMT posted a 35.5% jump in quarterly profit to RM47.02 million on stronger rental income and industrial and logistics additions. Those are not flashy numbers, but they are exactly the kind of steady compounding that tends to outperform when industrial demand and logistics throughput are improving.
There is also evidence the earnings cycle is still rewarding companies with pricing power and operating leverage. Pantech Global’s quarterly net profit surged 89.5% on stronger volumes, better pricing and a richer product mix, while Revenue IF’s tie-up with China’s WeSure Digital Technology expands cross-border payments and insurance-linked payment solutions across Southeast Asia. Both stories speak to the same market dynamic: investors should be looking beyond headline indices and toward the companies plugged into trade, fintech rails and regional commerce.
The market should not ignore the balance-sheet and asset-recycling side of the ledger either. Tien Wah’s RM34 million property purchase in Indonesia expands its real asset base, while Mudajaya’s proposed RM118.45 million disposal of a 45% stake in Real Jade to settle debts is a reminder that distressed balance-sheet repair can unlock value if it reduces financing drag. ES Sunlogy’s related-party mandate with Kerjaya Prospek also matters because it signals recurring business flows that can support order books and execution visibility.
My takeaway is straightforward: Malaysia’s opportunity set is broadening from defensive yield into a more powerful mix of healthcare expansion, AI infrastructure, electrification and logistics compounding. The market is still too focused on isolated headlines and not focused enough on the platform effect across these sectors. For investors, the best risk-reward likely sits in the picks-and-shovels names and asset-heavy operators tied to this capex wave, not in the obvious consumer or cyclical trades.
| Entity | Gains | Losses |
|---|---|---|
| Sunway Healthcare | ▲Long-term hospital growth | ▼Near-term capex burden |
| TNB / MRT Corp | ▲Grid and rail electrification | ▼Legacy infrastructure laggards |
| SkyeChip | ▲AI memory partnership upside | ▼Pure-play hardware rivals |
| AME REIT / CLMT | ▲Higher rental income | ▼Under-rented property owners |