The Maldives has welcomed India’s decision to extend a $320 million currency swap facility, giving the island nation more breathing room to manage foreign-exchange needs and avoid an immediate repayment squeeze.
Maldives Gets India Swap Facility Extension

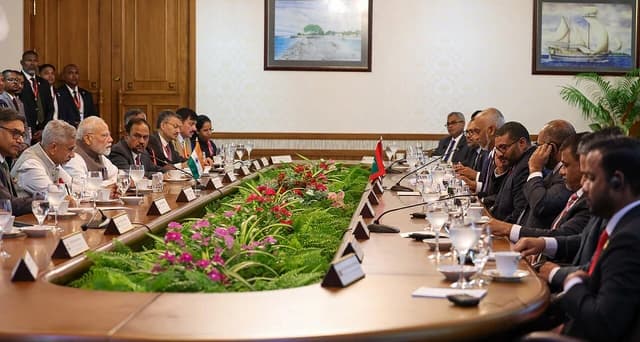
The rollover covers the first INR 30 billion drawdown under the bilateral swap arrangement between the Reserve Bank of India and the Maldives Monetary Authority. Malé had asked for more time because the payment was due in about 10 days, and reports said India agreed to give a further three months, though New Delhi has not formally announced it yet.
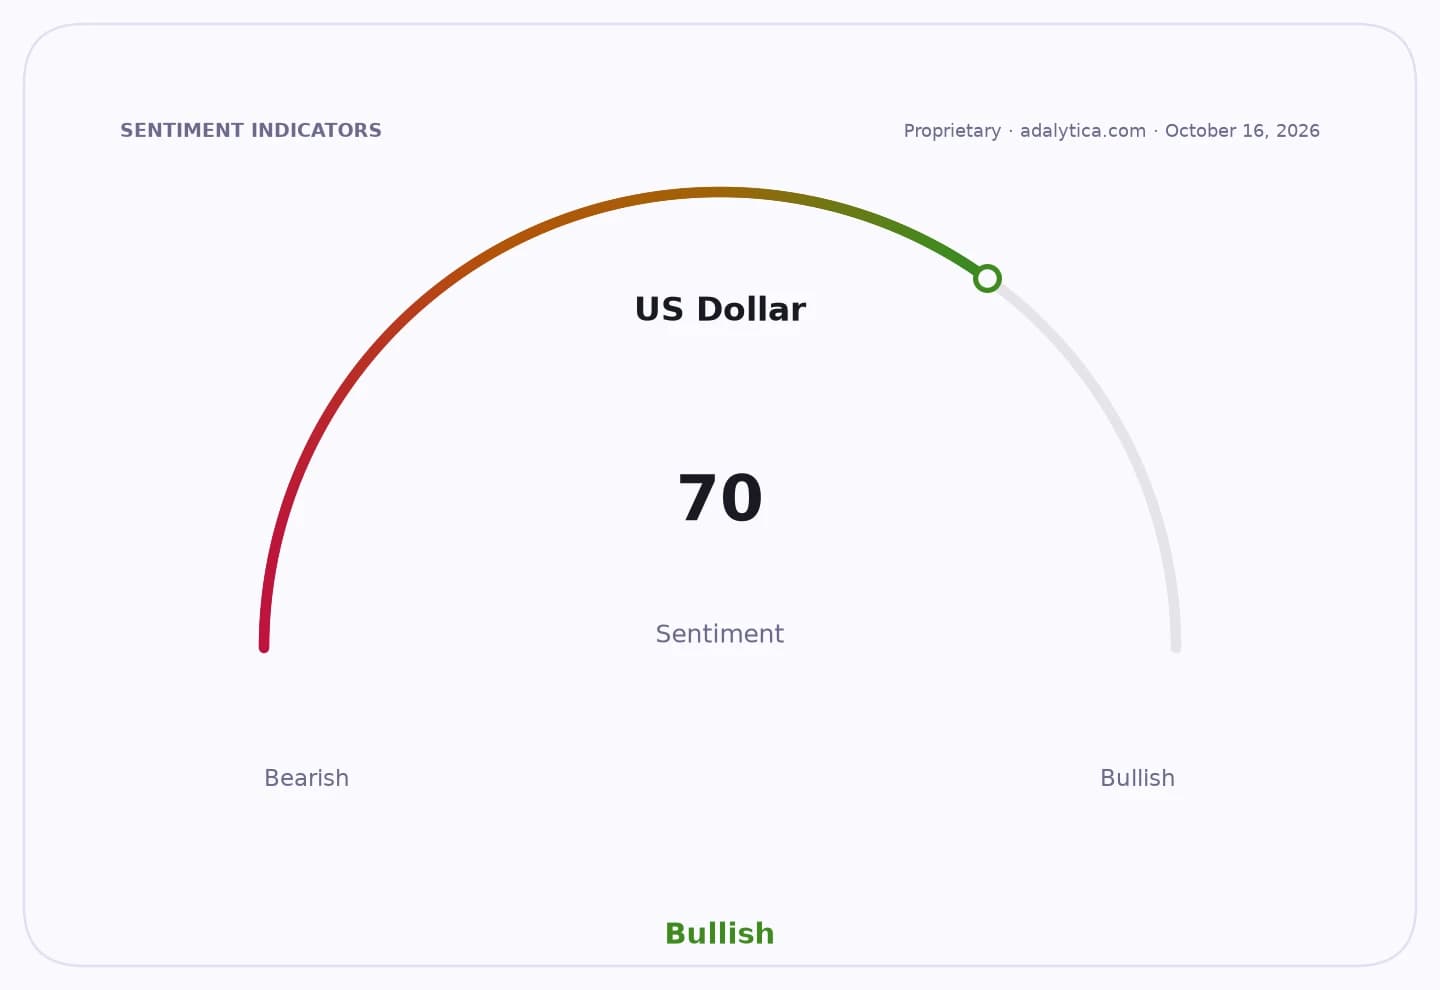
Sentiment IndicatorsⓘProprietary · adalytica.com · October 21, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The move matters because the Maldives relies heavily on external financing to cover imports, service debt and stabilize its balance of payments. A short-term swap extension does not solve the country’s broader funding needs, but it helps prevent near-term pressure on reserves and reduces the risk of a sharper currency or liquidity shock.
India first approved the $320 million withdrawal on April 23 under the SAARC Currency Swap Framework, underscoring the strategic use of financial assistance alongside diplomacy in the Indian Ocean. The facility was agreed during President Mohamed Muizzu’s state visit to India in October 2024, and the Maldives repaid $50 million in debt to India in September, showing the two sides are still actively managing obligations inside the relationship.
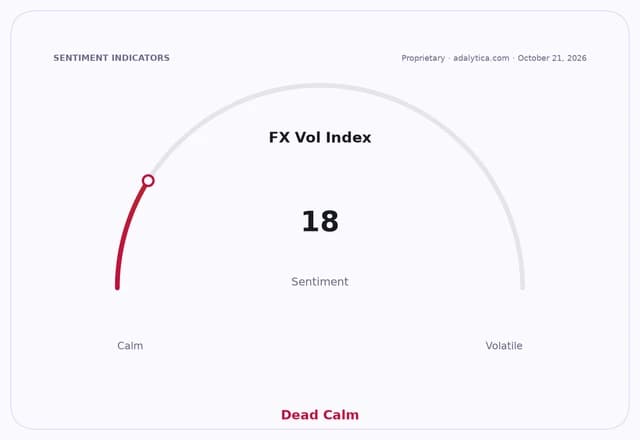
For investors, the extension is a sign that the Maldives is still dependent on official support to bridge external financing gaps. That can calm immediate default concerns, but it also highlights how vulnerable the country remains to refinancing risk, tourism swings and reserve erosion, all of which matter for sovereign credit pricing and regional risk sentiment.
The development also reinforces India’s Neighbourhood First policy and its willingness to use financial lines as a tool of influence. Markets will now watch for an official confirmation from India, and for whether the Maldives secures longer-term funding that reduces its reliance on repeated roll-overs.
| Entity | Gains | Losses |
|---|---|---|
| Maldives government | ▲Short-term FX relief | ▼Ongoing refinancing dependence |
| India / RBI | ▲Regional influence | ▼More exposure to Maldives support |
| Maldivian lenders and importers | ▲Near-term liquidity stability | ▼No structural funding fix |
| Sovereign creditors / FX bears | ▲Less immediate default risk | ▼Lower distress premium opportunity |