McDonald’s reported higher profit even as continued sluggish domestic sales underscored a split between its U.S. business and the rest of the world, showing the burger chain’s scale and pricing power can still cushion earnings when American consumers pull back.
McDonald’s profit rises as U.S. sales stay weak
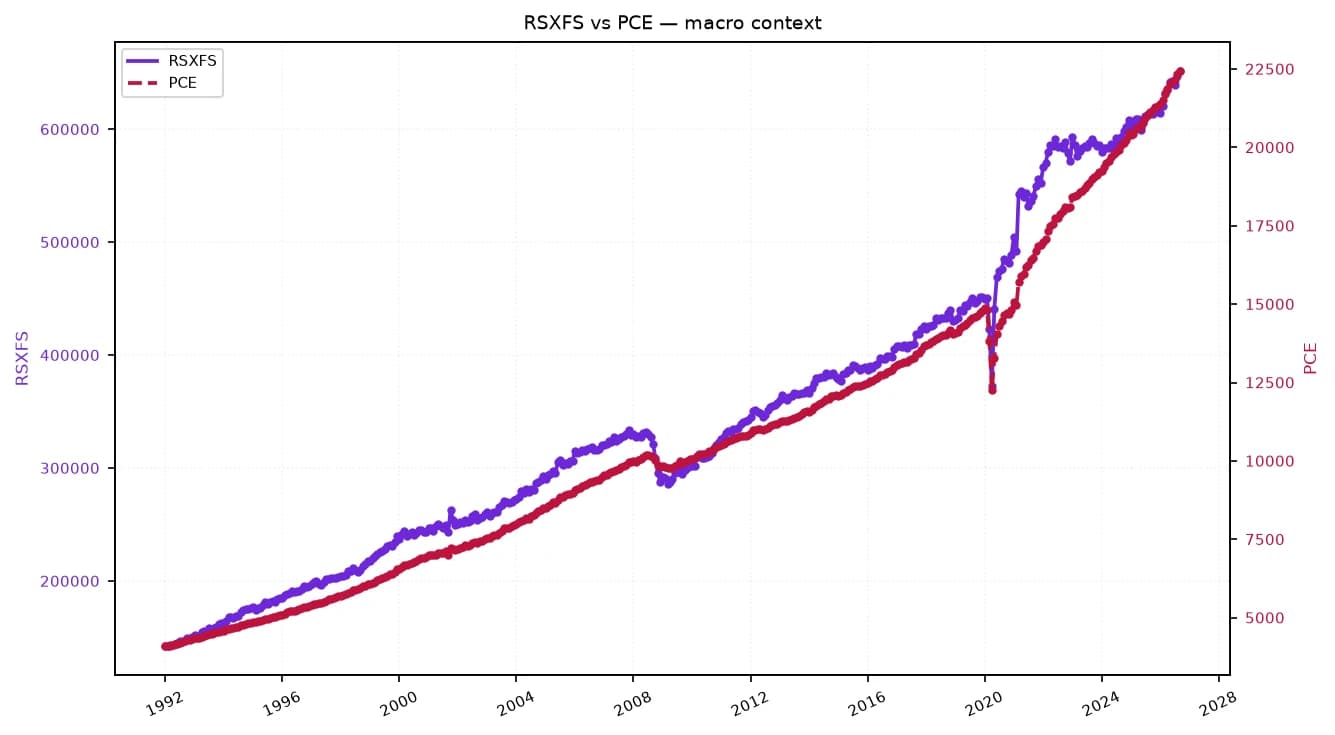
The result matters because McDonald’s remains one of the clearest gauges of mass-market restaurant demand. Weak domestic traffic suggests lower-income consumers are still under pressure from sticky food prices and a cautious labor backdrop, but the company’s global footprint, franchise-heavy model and menu pricing helped keep earnings moving in the right direction. For investors, that combination is important: it points to resilient cash generation even if the core U.S. market is not yet firing on all cylinders.
Sentiment Indicators
McDonald’s shares have also been digesting a sharp rebound in late-year trading, with the stock closing at 276.52 on Nov. 6 after touching 334.50 in February before sliding through the spring and summer. The recovery has come alongside a broader rotation back into defensive consumer names, even as technical indicators show the stock was still below its 200-day moving average and coming off elevated RSI readings in early November. That suggests the market is rewarding stability, but not ignoring the uneven operating picture.
The company’s latest filing pointed to a multi-year rollout of its “McDonald’s > NEXT” strategy, with execution varying by market depending on customer demand, technology readiness and franchisee capacity. That matters because it signals management is trying to improve restaurant economics without relying solely on aggressive discounting. If the strategy can lift throughput, digital sales and store productivity, it may help offset the pressure from a weak domestic consumer. If not, U.S. softness could continue to cap same-store-sales momentum.
The broader restaurant backdrop remains mixed. Peers such as Yum Brands and Starbucks have also shown that higher menu prices and shifting consumer behavior can support revenue while masking strain underneath, especially in the U.S. quick-service market. In that environment, McDonald’s advantage is its global diversification and its ability to trade customers down into value items without sacrificing profitability as quickly as smaller chains.
For investors, the key question is whether McDonald’s can turn international strength and operational improvements into more durable U.S. traffic gains. If domestic sales stay sluggish, the stock’s upside may depend on margin control, marketing execution and franchisee health rather than a broad demand rebound. If U.S. consumer spending stabilizes, McDonald’s could have room to extend earnings growth from an already powerful base.
| Entity | Gains | Losses |
|---|---|---|
| McDonald’s | ▲Profit resilience | ▼U.S. traffic softness |
| International markets | ▲Earnings support | ▼Less dependence on U.S. sales |
| Franchisees | ▲Brand scale and support | ▼Pressure from weak domestic demand |
| U.S. value diners | ▲Lower-priced meal options | ▼Limited menu trade-up |