Meta Platforms and Advanced Micro Devices are emerging as the clearest ways to play a market that still wants AI exposure, even as Wednesday’s inflation data and ASML earnings decide whether the latest tech rebound has room to run.
Meta, AMD, ASML Lead AI Trade Into CPI Data
That is the key setup for investors: the trade is no longer simply “buy megacap tech.” It is buy companies with tangible AI monetization, while keeping one eye on bond yields and another on semiconductor supply-chain guidance. Dow Jones futures, S&P 500 futures and Nasdaq futures were little changed after hours, but that calm masks a market on edge after a session in which Meta and other megacaps helped cushion the indexes while tech stocks remained vulnerable to rising borrowing costs and renewed questions about AI spending.
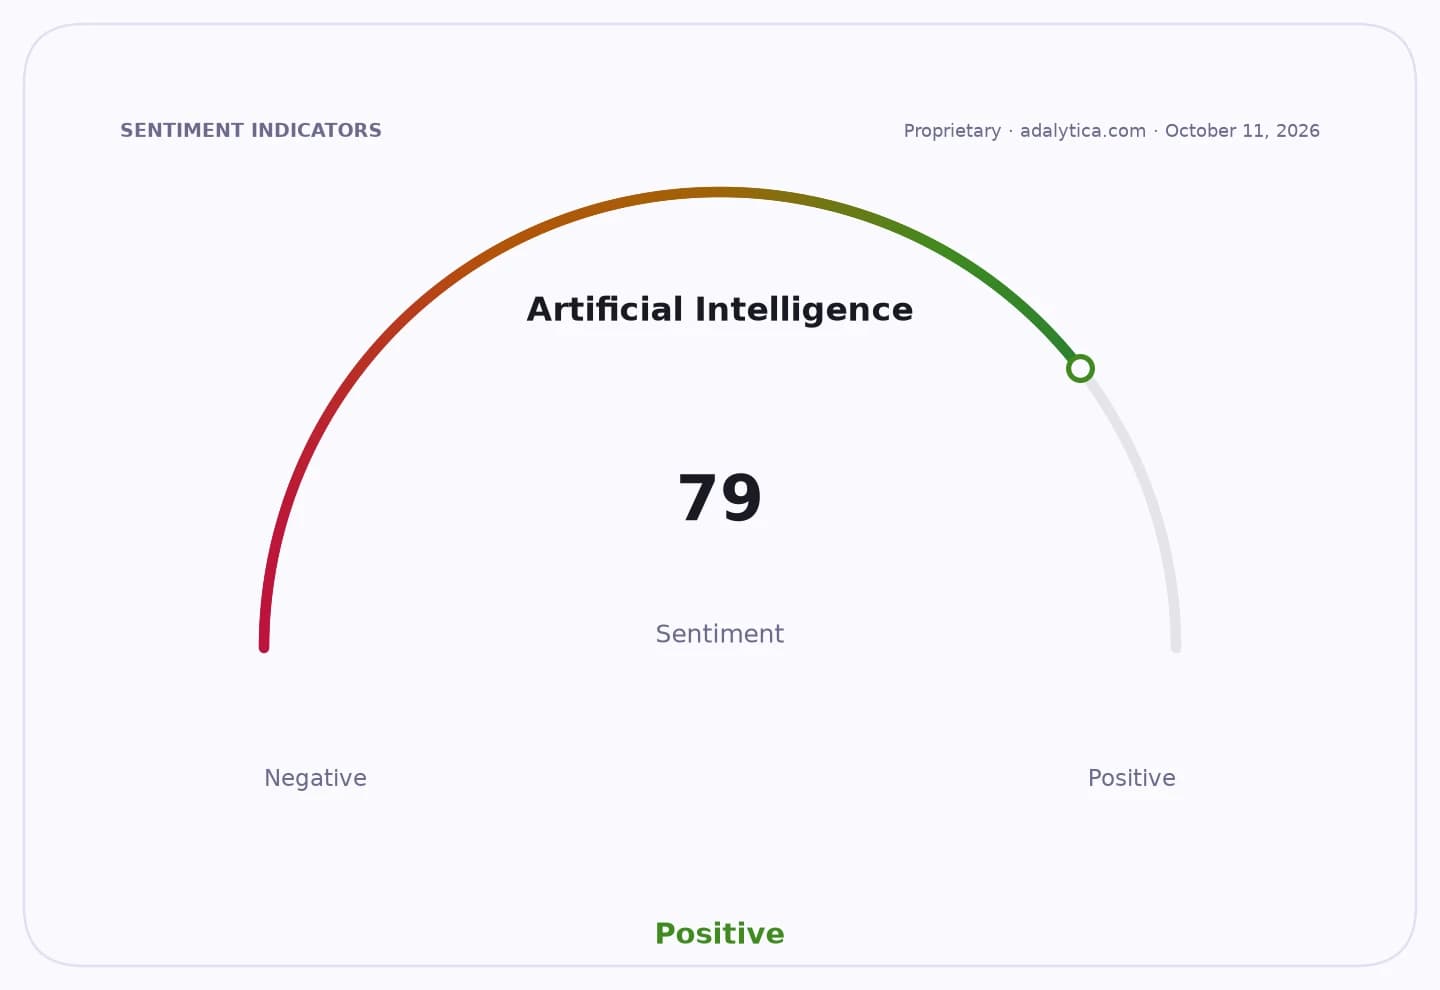
Sentiment IndicatorsⓘProprietary · adalytica.com · October 14, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The macro backdrop matters because inflation is still the hinge for valuations. The consumer price index report due Wednesday will shape expectations for the Federal Reserve’s next move, and U.S. rate futures are already pricing a policy rate around 3.73% next month after a recent run near 3.63%, with the 10-year Treasury yield hovering above 5%. That is a tough environment for long-duration growth stocks. If CPI comes in soft, it gives the market room to reprice AI winners higher. If it comes in hot, investors are likely to rotate toward cash-generating leaders and away from the most speculative corners of tech.
Meta is the most obvious beneficiary of that setup. The stock has already shown the kind of power market leadership that attracts momentum capital, and its technical profile remains constructive, with the shares recently trading above both the 50-day and 200-day moving averages even after volatility. More important than the chart, though, is the business model: Meta’s ad engine is still compounding, and its AI spending is increasingly tied to measurable revenue gains rather than abstract promises. In a market worried that AI capex is outrunning returns, that distinction matters. Investors are not paying for a story; they are paying for monetization.
Artificial Intelligence vs METAadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
AMD is the other name that stands out because it sits at the intersection of AI enthusiasm and second-order hardware demand. The market has already rewarded the stock heavily this year, and even after recent pullbacks it remains far above long-term trend measures. That is a sign of conviction, but it also means the bar is high. A clean CPI print and any evidence that AI infrastructure spend is still accelerating could fuel another leg higher. The larger opportunity is not just in AMD itself, but in the entire ecosystem built around AI compute, networking and power-intensive data centers.
ASML is the critical tell for that thesis. The Dutch equipment giant is due to report at a time when semicap investors are trying to figure out whether the AI buildout is broadening or peaking. ASML’s latest outlook already pointed to 2026 sales of roughly €43 billion to €45 billion, with gross margins of 54% to 56%, underscoring just how much demand still sits in advanced chipmaking. If ASML confirms that customers are still spending aggressively, it will reinforce the case that the AI capital cycle is intact. If it disappoints, the market will quickly question whether the current wave of spending is becoming more cyclical than secular.
That is why the next move in tech likely belongs to a narrower group of winners rather than the whole sector. Meta offers operating leverage and AI monetization. AMD offers upside to compute demand. ASML offers exposure to the bottleneck that every advanced chipmaker must pass through. Together they frame the trade better than broad index exposure does.
The market is also sending a subtler message through sentiment and positioning. Adalytica’s AI sentiment gauge is deep in greed territory even as awareness remains at extreme fear, a combination that usually reflects crowded enthusiasm alongside investor reluctance to chase. That is exactly when disciplined investors should focus on the highest-quality picks-and-shovels names rather than the most crowded hype. The setup argues for owning the infrastructure behind AI, not just the headlines around it.
The actionable takeaway is simple: if CPI cooperates, Meta, AMD and ASML are positioned to lead the next phase of the AI trade; if it does not, they are still the names most likely to hold relative strength. Either way, this remains a stock-picker’s market, and the asymmetric opportunity is in companies converting AI capex into real earnings power.
| Entity | Gains | Losses |
|---|---|---|
| Meta Platforms | ▲AI-driven ad monetization | ▼Rate-sensitive growth skeptics |
| AMD | ▲AI compute demand | ▼Broad tech laggards |
| ASML | ▲Semiconductor capex cycle | ▼Investors betting on an AI slowdown |
| Treasury yields | ▲Bondholders seeking capital gains | ▼Long-duration tech valuations |