Mexico’s inflation rate quickened to 3.75% in October, underscoring that price pressures remain firm enough to keep the central bank cautious even as the reading stays within Banxico’s target band.
Mexico inflation rises to 3.75% in October
The number matters because it shows inflation is not breaking decisively lower, limiting the scope for aggressive interest-rate cuts and keeping borrowing costs elevated for households and businesses. In a region where monetary policy is being watched closely against a backdrop of tighter U.S. financial conditions, Mexico’s latest print suggests policymakers still need to balance disinflation against the risk of weakening growth.
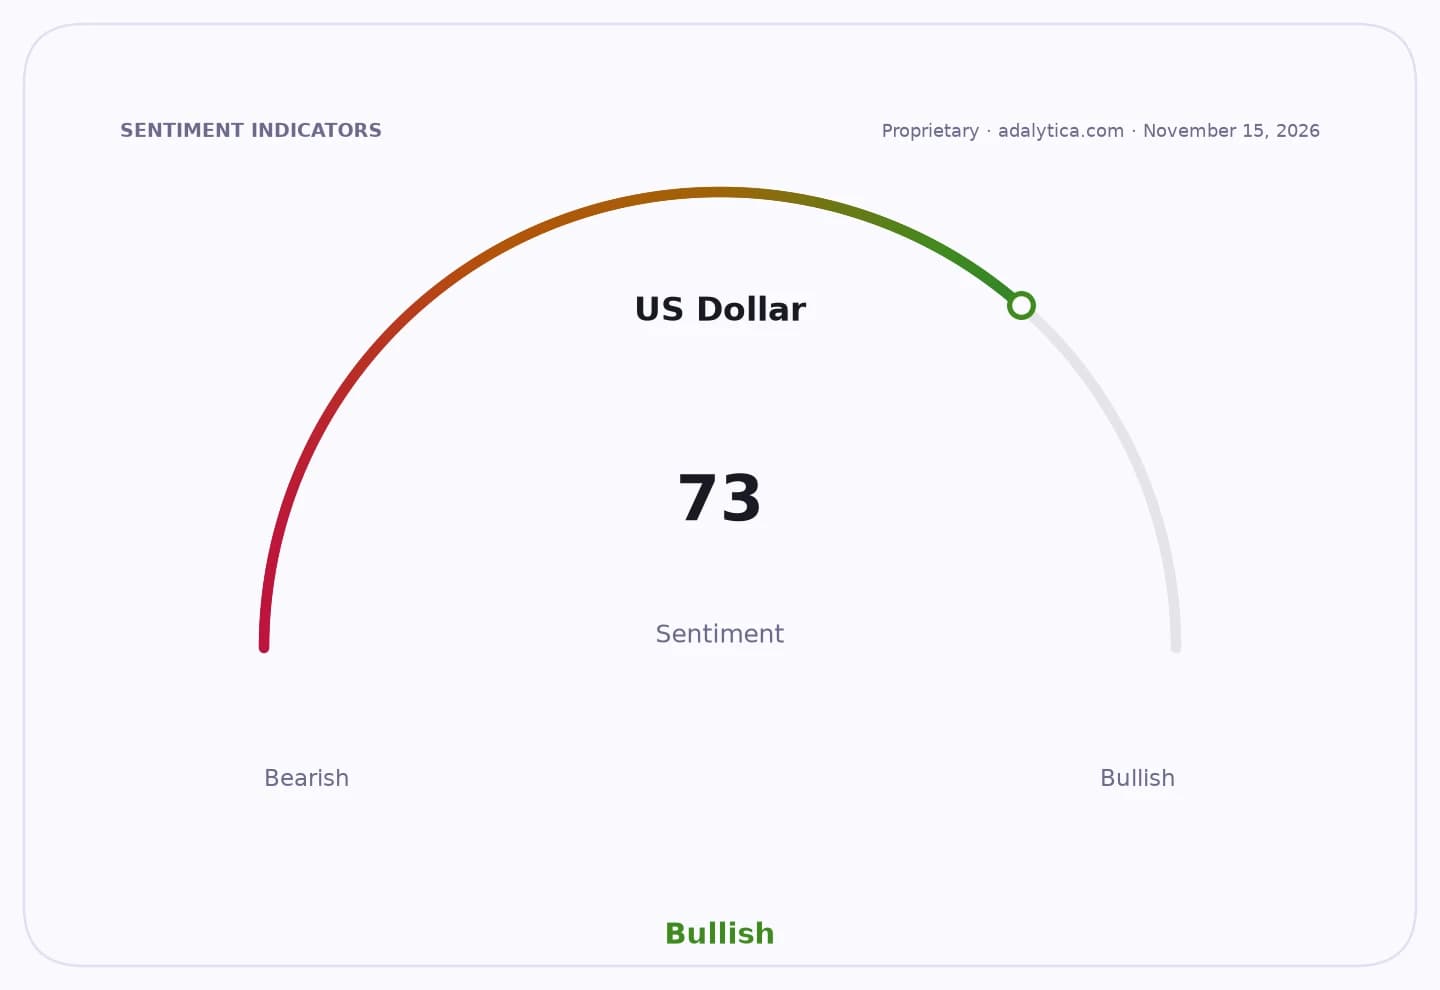
Sentiment Indicators
October’s reading was consistent with a month-on-month increase of 0.35%, according to the data, following 0.65% in September. That is not a resurgence to crisis levels, but it is enough to keep the conversation focused on the persistence of services and food-price pressures rather than on a clean inflation retreat. The trajectory also leaves the central bank little room to ease too quickly without risking renewed price stickiness.
For investors, the immediate implication is that Mexican rates may stay relatively high for longer than the market would prefer, supporting carry but also constraining domestic demand. That has mixed consequences for equities, where banks and some exporters can benefit from a higher-rate backdrop and a firm peso, while consumer-facing companies face pressure from cautious households and softer discretionary spending.
CPI
The story also sits against a broader global inflation backdrop in which the U.S. has reaccelerated more than expected, keeping the dollar supported and reinforcing tighter external financial conditions for emerging markets. Mexico’s inflation print therefore matters not just as a domestic macro reading but as part of the case for a still-restrictive policy stance across North America.
If inflation remains close to this pace into the next few releases, Banxico may be forced to slow any easing cycle and wait for clearer evidence that underlying price growth is cooling. For markets, that means the path of Mexican yields, the peso and consumer-sensitive stocks will continue to hinge on whether October proves to be a pause in disinflation or the start of a longer plateau.
| Entity | Gains | Losses |
|---|---|---|
| Banxico hawks | ▲policy credibility | ▼faster rate cuts |
| Mexican banks | ▲wider margins | ▼cheaper funding |
| Consumers | ▲price stability | ▼purchasing power |
| Consumer stocks | ▲select pricing power | ▼weaker demand |