Mexico’s stock market extended its slump for a fifth straight session on Thursday, with the IPC falling 0.64% to 68,713.6 points as a weaker peso and broad global risk aversion kept pressure on local assets.
Mexico IPC Falls 0.64% as Peso Weakens
That matters because Mexico is increasingly being judged less as a standalone equity story and more as a high-beta trade on global liquidity, U.S. growth and emerging-market sentiment. When the peso weakens and equities fall together, foreign investors tend to demand a bigger risk premium, which can hit capital flows, valuations and the ability of Mexican corporates to finance expansion on favorable terms.
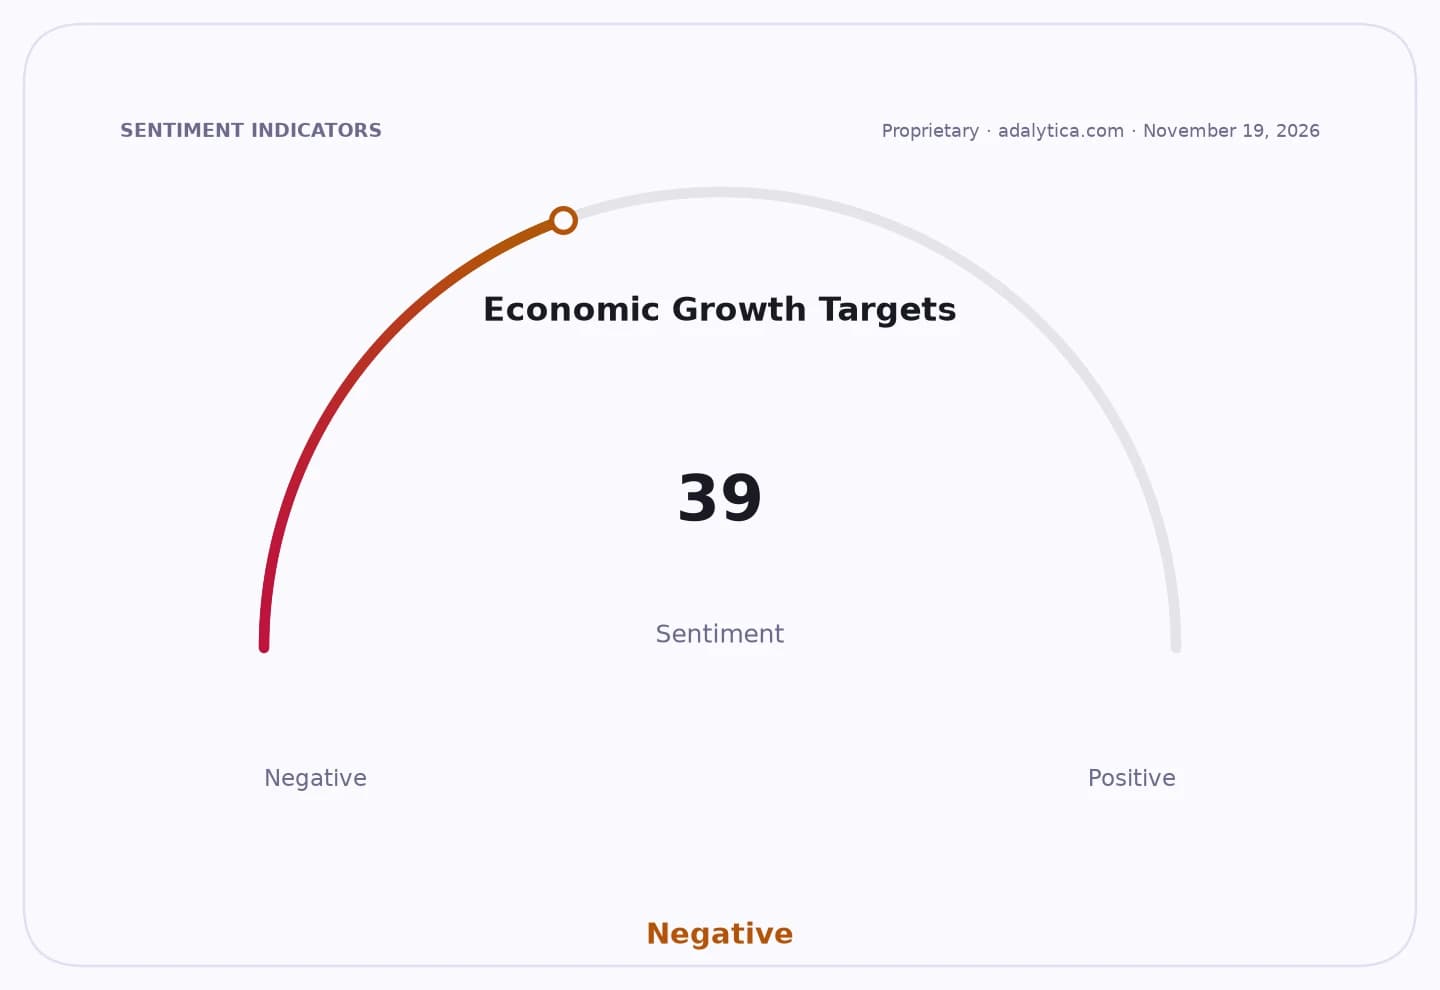
Sentiment Indicators
US Dollar
The selloff also leaves the benchmark on track for a negative weekly close, with losses of 3.48% from Tuesday through Thursday after Monday’s holiday. Even so, the index remains up 6.88% so far this year, underscoring that the current pullback is taking place against a still-positive longer-term backdrop rather than a full-scale trend reversal.
The day’s weakness was concentrated in metals, mining and construction-related names, a sign the market is reacting to both cyclical and currency pressure. Industrias Peñoles fell 4.52%, Grupo México dropped 3.87%, GCC lost 3.59%, Genomma Lab slipped 3.5% and Cemex declined 3.22%. On the upside, Grupo Carso rose 4.51%, while airport operator ASUR gained 3.41% and steelmaker Industrias CH added 3.09%.
US Dollar
The peso’s 1.43% slide to 19.12 per dollar is the key second-order signal. A weaker currency helps exporters but squeezes importers, raises the local cost of dollar funding and can weigh on consumer confidence if the move persists. It also makes Mexico’s equity market look less insulated at a time when global stocks are already under strain.
The backdrop was not uniquely Mexican. Most major markets were lower, according to local market commentary, which said capital markets saw broad losses worldwide despite the debut of Anthropic in Nasdaq-linked trading. That tells investors this is not just a domestic rotation; it is a risk-off episode hitting Mexico through both equities and FX.
For investors, the opportunity is not to chase the weakest names blindly but to distinguish between cyclicals and compounding franchise businesses. Export-oriented, dollar-earning companies and asset-light operators can hold up better if the peso stays soft, while miners, cement, discretionary and import-sensitive stocks may remain vulnerable until the currency stabilizes and global risk appetite improves.
The message from the tape is straightforward: Mexico is still in a constructive year-to-date uptrend, but the market is pricing a more cautious near-term macro environment. If global equities remain under pressure and the peso continues to weaken, the next leg will likely favor quality balance-sheet names, dollar-linked cash flows and sectors with pricing power over levered domestic cyclicals.
| Entity | Gains | Losses |
|---|---|---|
| Exporters and dollar earners | ▲FX tailwind | ▼None |
| Importers and peso-sensitive firms | ▲None | ▼Higher input costs |
| Miners and construction stocks | ▲Possible long-term leverage to cycle | ▼Heavy selling pressure |
| Mexico equity bulls | ▲Year-to-date gains intact | ▼Five-day losing streak |