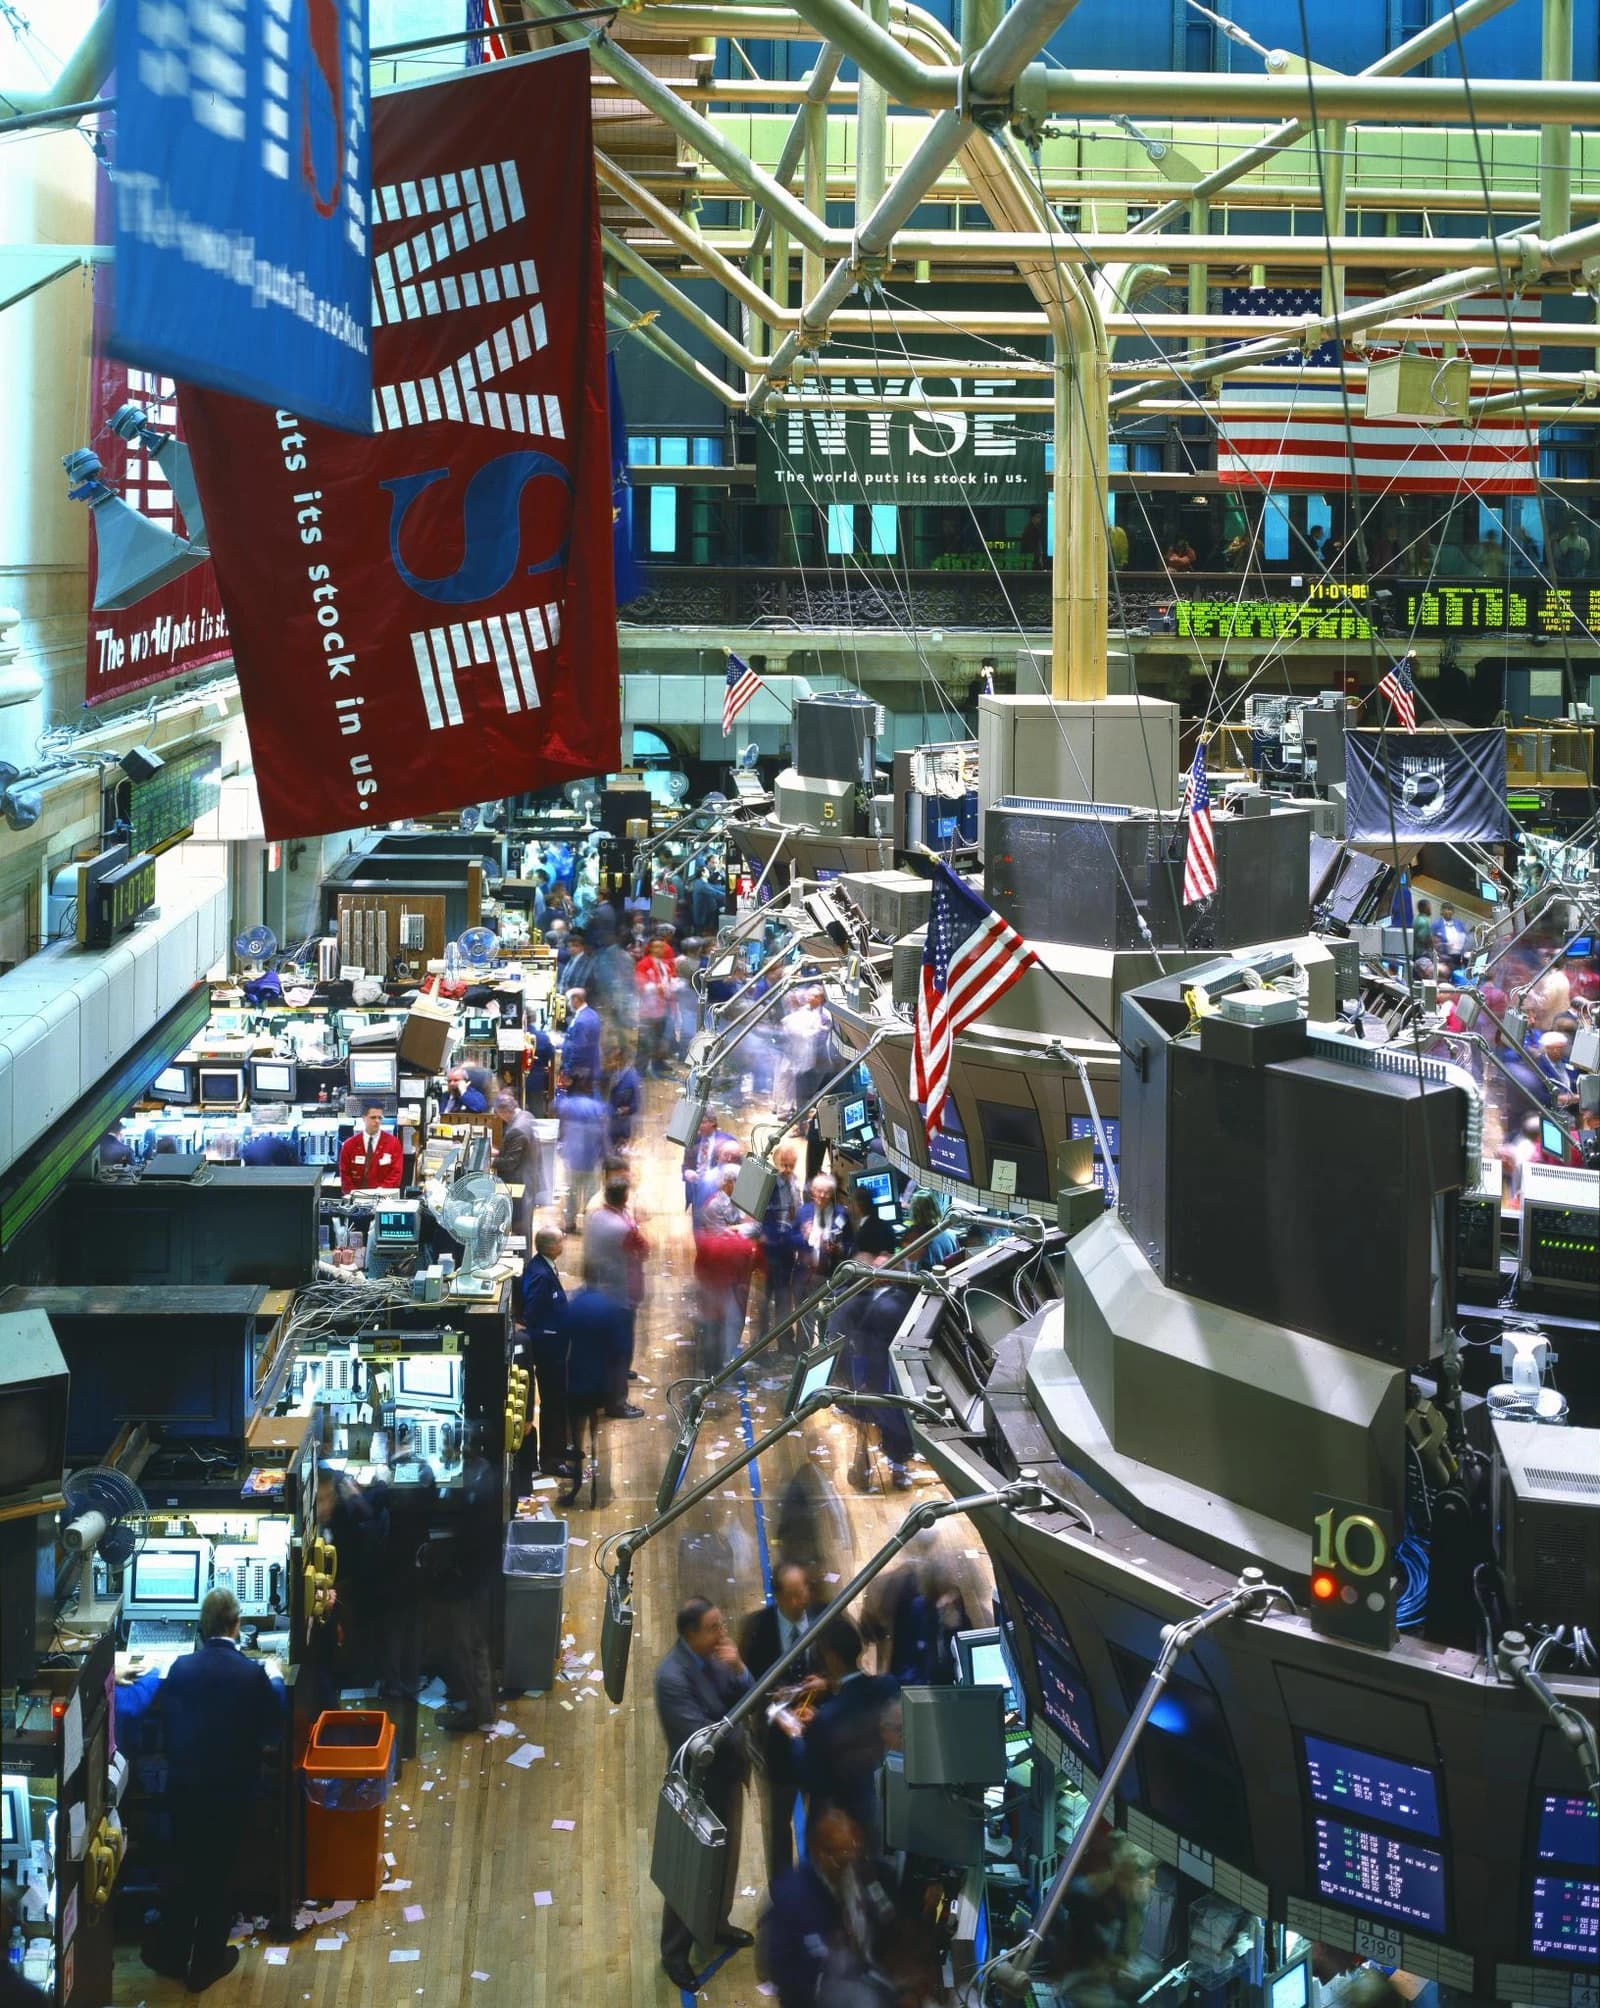
Investors are heading into next week with the market still reeling from a sharp unwind in the AI trade and with the October consumer price report set to test whether the Federal Reserve can keep easing rate-hike fears.
Nasdaq Correction Before October CPI Data
The timing matters because inflation is now colliding with a fragile equity tape. The Nasdaq Composite closed Thursday nearly 12% below its Oct. 6 peak, formally entering correction territory, after a rout that sent the Philadelphia SE Semiconductor index down more than 12% in its worst one-day drop in more than six years.
Sentiment Indicators
CPI
The selloff has spread beyond the chipmakers that powered this year’s rally. The S&P 500 tech sector fell 7.3% on Thursday, and all 11 S&P sectors finished lower as volatility surged to a seven-month high, underscoring how quickly investors are moving out of the market’s most crowded growth trade.
The inflation report due Tuesday could determine whether that de-risking continues. Fed fund futures still priced roughly a 65% chance of a December rate hike, even after traders trimmed bets during Thursday’s slide, leaving the market exposed to a hotter-than-expected reading that would strengthen the case for further tightening.
That would matter most for megacap technology and AI infrastructure names, where valuations have been sensitive to both rates and policy risk. The post-midterm selloff was exacerbated by concern that Democrats’ victories could slow the data-center buildout, adding a political overlay to a trade already under pressure from stretched positioning and financing worries.
The pressure is showing up in relative performance too. Tech has underperformed the S&P 500 over the past month by the widest margin since May 2002, according to Truist, a sign of what one strategist called a “buyers’ strike” in the sector.
Next week’s earnings from CoreWeave, Applied Materials and Cisco will add another read on whether AI spending remains intact or starts to wobble. For investors, the near-term risk is simple: a strong CPI print could keep rates elevated, keep pressure on growth stocks and extend the correction in the market’s most important trade.
| Entity | Gains | Losses |
|---|---|---|
| Bond bears | ▲Higher-yield backdrop | ▼Rate-cut hopes |
| AI infrastructure stocks | ▲Softer CPI, easing rates | ▼Hot CPI, tighter policy |
| Fed hawks | ▲Strong inflation data | ▼Dovish easing bets |
| Nasdaq / tech longs | ▲Cool inflation print | ▼More deleveraging and volatility |