Norway’s $2.36 trillion sovereign wealth fund posted a rare quarterly loss in the third quarter as higher interest rates knocked bond values lower, showing how quickly inflation and central-bank tightening can still erode even the world’s biggest investor.
Norway sovereign fund posts rare quarterly loss
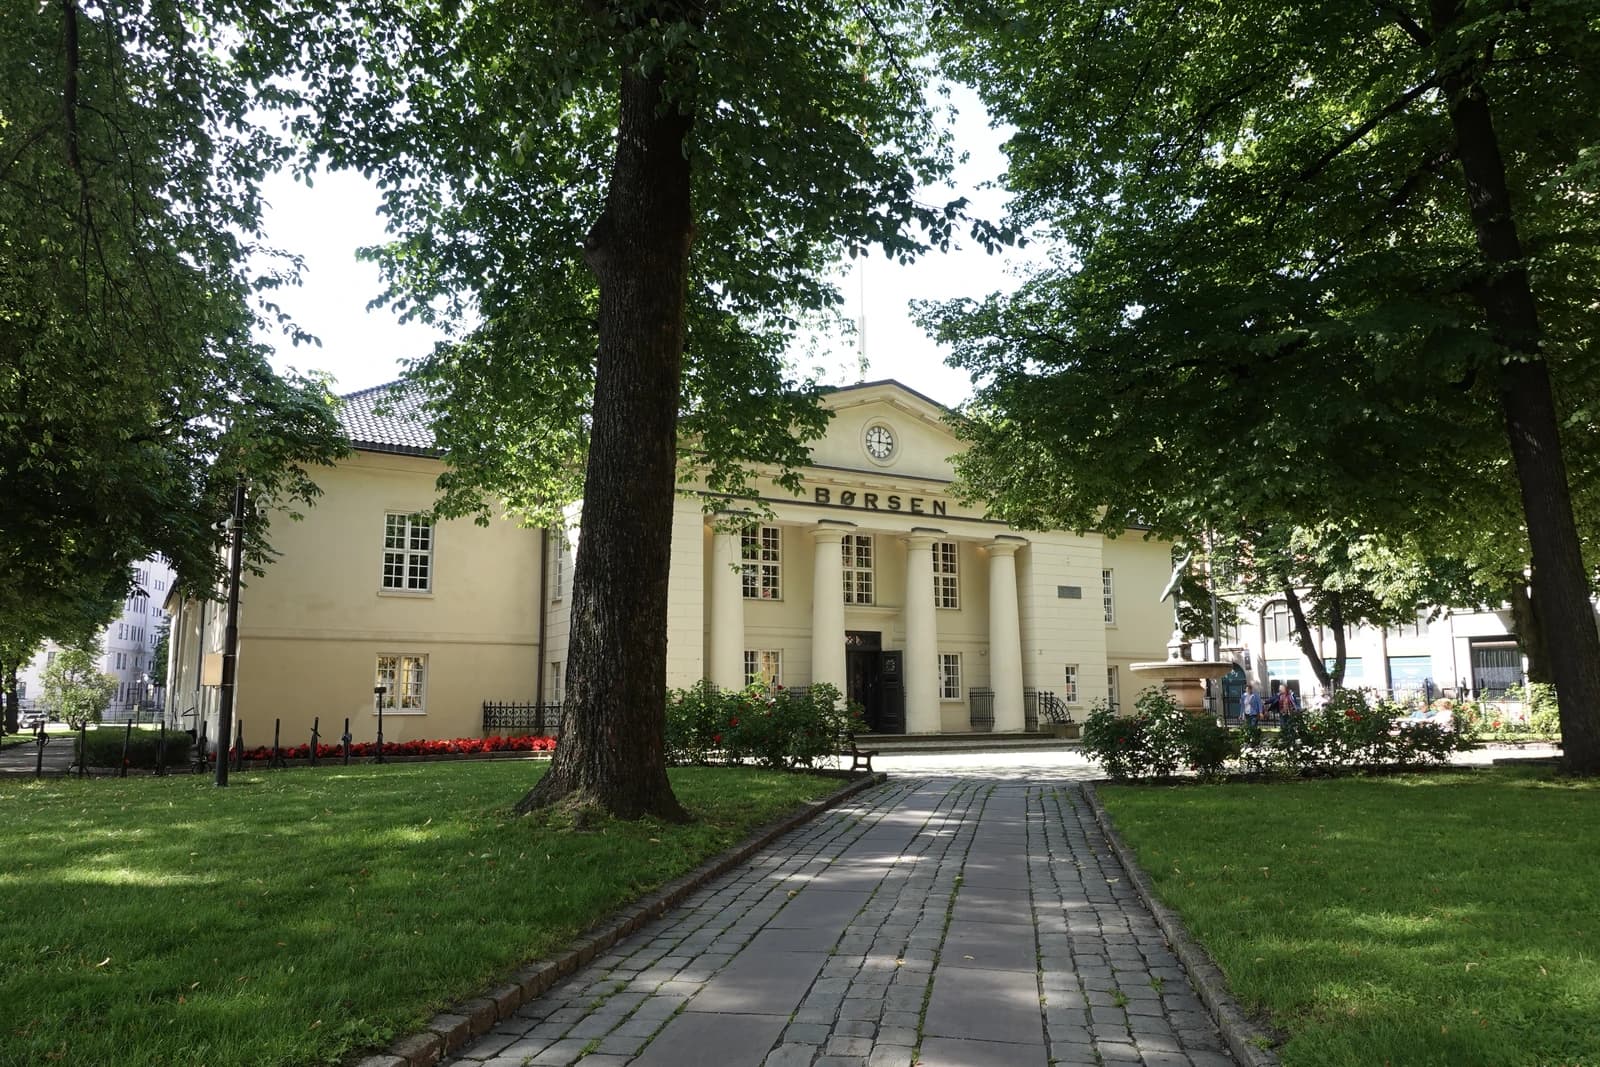
The Government Pension Fund Global said it lost 278 billion kroner, or $29.2 billion, over the period, with overall returns slipping 0.5%. The drag came mainly from fixed income, where bond investments fell 3.5% as yields rose and prices dropped. Stocks and real estate managed only modest gains, not enough to offset the bond losses.
Sentiment Indicators
For investors, that matters because the fund is not just a Norwegian savings vehicle — it is a barometer for global asset prices. When the largest sovereign wealth fund in the world takes a hit from duration risk, it underscores a broader truth: inflation is still forcing central banks to keep rates higher for longer, and that pressure flows straight through to bond portfolios, pension funds and long-term capital allocators.
The timing was especially uncomfortable. Persistent inflation, helped by strong U.S. economic growth and elevated energy prices tied to the Middle East conflict, kept the Federal Reserve and European Central Bank on a tightening bias during the quarter. That pushed bond yields higher and reduced the market value of the very securities the fund owns in large quantities.
At the end of September, the fund’s assets stood at 22.014 trillion kroner, about $2.36 trillion, making the setback meaningful but not alarming in the context of its long-term compounding model. Norway’s fund is built to absorb short-term volatility, and quarterly swings like this are part of the trade-off for owning a massive, globally diversified portfolio.
Still, the message for long-term investors is clear: fixed income is no longer the easy ballast it was when rates were near zero. Higher yields can improve future return prospects, but in the near term they continue to punish existing bond holdings. That means portfolios still need patience, diversification and realistic expectations about how inflation and policy can ripple through even the strongest balance sheets.
| Entity | Gains | Losses |
|---|---|---|
| Bond sellers | ▲Higher yields on new issuance | ▼Existing bond prices |
| Norway’s sovereign fund | ▲Long-term reinvestment at higher yields | ▼Third-quarter asset values |
| Central banks | ▲More room to fight inflation | ▼Growth-sensitive borrowers |
| Long-duration investors | ▲Potentially better future income | ▼Near-term mark-to-market losses |