NVIDIA’s latest analyst snapshot says the AI trade is still intact, even after a volatile stretch for the stock.
NVIDIA Analysts Keep Buy Ratings, Raise Target
Seven analysts tracked in September all rated NVIDIA a buy, with an average price target of $368.57 versus the shares’ recent $228.38 close, implying roughly 57% upside. That matters because NVIDIA remains one of the market’s clearest ways to own the buildout of artificial intelligence infrastructure, and Wall Street is still betting that demand for its chips, systems and software will keep compounding for years.
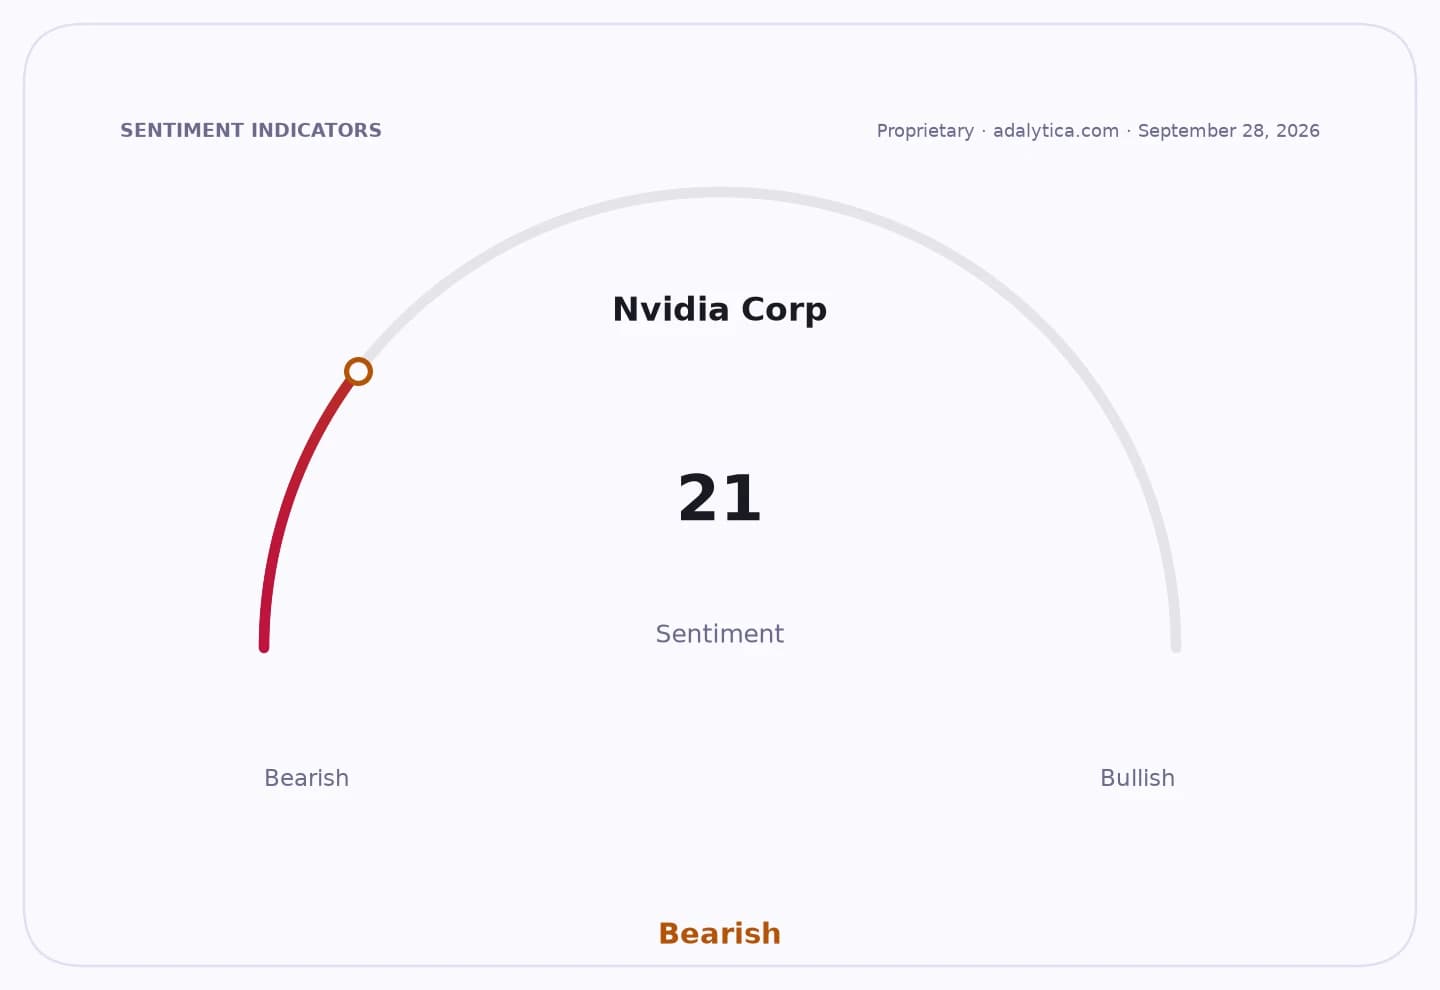
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the key point is not just that the target is higher. It is that analysts are looking past short-term swings and focusing on NVIDIA’s role at the center of a multi-year capital-spending cycle across cloud computing, model training and data-center upgrades. The company’s own filings describe it as a data-center-scale AI platform business, and that framing helps explain why the stock continues to command bullish coverage even when the market gets choppy.
The shares have certainly not been sleepy. NVIDIA closed at $233.95 on Oct. 2 after trading as high as $237.88, well above its 50-day moving average of $218.12 and 200-day moving average of $200.38. The relative strength index of 83 suggests the stock has been running hot in the near term, which can invite consolidation, but it does not change the broader thesis: when a market leader keeps holding above major technical levels while analysts remain uniformly bullish, long-term investors tend to view pullbacks as entries rather than exits.
There is also a bigger industry story behind the rating trend. Taiwan Semiconductor, one of NVIDIA’s key manufacturing partners, has seen its own shares climb to 472.78 from 456.19 at the end of September, underscoring how demand for advanced chips is still flowing through the supply chain. Microsoft, meanwhile, has been investing aggressively in AI capacity, and that kind of spending is exactly what feeds NVIDIA’s growth engine. If customers keep building out AI infrastructure, NVIDIA benefits not just from unit sales but from the broader ecosystem of software, networking and system-level upgrades tied to those deployments.
That said, investors should keep the risks in perspective. The stock is already priced for a lot of success, and the high RSI reading suggests enthusiasm is stretched. Execution matters, especially in a business where supply-chain complexity, customer concentration and the timing of AI spending can move results around from quarter to quarter. But for a company with NVIDIA’s moat, scale and exposure to one of the strongest secular trends in technology, the long-term setup still looks compelling.
For buy-and-hold investors, the takeaway is straightforward: Wall Street continues to see NVIDIA as a core AI winner, and the combination of unanimous buy ratings, a large target-price gap and ongoing hyperscale demand keeps the stock firmly on watch for those willing to think in years, not weeks.
| Entity | Gains | Losses |
|---|---|---|
| NVIDIA shareholders | ▲Higher target prices | ▼Missed upside if they sell too early |
| AI infrastructure buyers | ▲Access to faster computing | ▼Higher capital spending |
| TSMC | ▲More chip demand | ▼Supply strain and concentration risk |
| Short-term traders | ▲Volatility opportunities | ▼Risk from momentum staying strong |