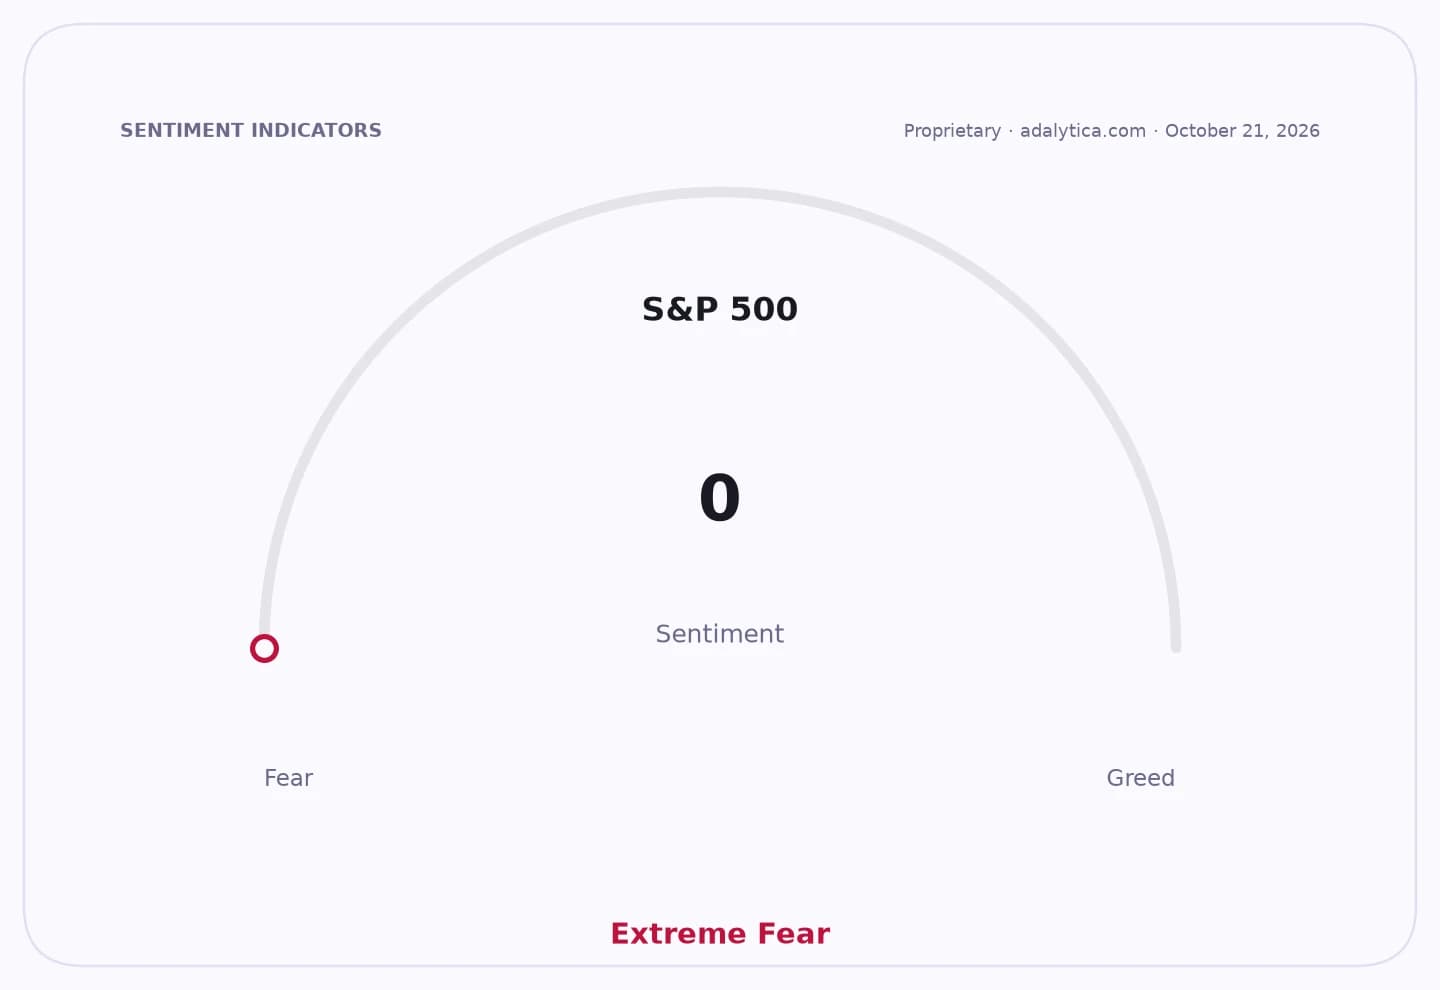
Wall Street’s latest batch of Tuesday calls shows investors are still willing to pay for artificial intelligence, but they are becoming far more selective about which names deserve the premium. That matters because the market’s biggest winners in this cycle are no longer just riding enthusiasm — they are being judged on how much cash flow, earnings growth and durability they can still deliver over the next several years.
Nvidia, Apple, BlackRock See Analyst Call Shifts
The sharpest signal came in semiconductors and megacap tech. Piper Sandler reiterated an overweight rating on Nvidia even as it said investors are struggling to identify the next near-term catalyst, a reminder that the stock’s long-term AI story remains intact but harder to chase after a massive run. Loop Capital, meanwhile, cut Apple to hold from buy, saying the company needs a “fundamental catalyst reset” and that prior hopes for iPhone unit recovery no longer look as dependable, especially if demand is no longer the main issue behind weaker shipments. That is a meaningful shift for investors who have long treated Apple as a steady compounder: the burden of proof is now on the company to show that its next growth leg can come from product cycles, services or AI-led upgrades rather than simply from waiting for hardware demand to normalize.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 25, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The market backdrop helps explain why these calls matter. Nvidia shares have been volatile even after a huge advance, and the stock’s recent technical setup shows how quickly momentum can fade when traders start looking for the next proof point. The shares recently slipped below their 50-day moving average, while RSI readings moved into oversold territory on one stretch before recovering somewhat — signs that the stock is still digesting expectations rather than sprinting higher in a straight line. For long-term investors, that usually means the debate is less about whether AI spending continues and more about whether the valuation already reflects a lot of it.
BlackRock is getting a different kind of validation. TD Cowen upgraded the asset manager to buy from hold, arguing that earnings growth should accelerate after a slower period and that the stock could outperform once that inflection arrives. That is important because BlackRock sits at the center of a huge secular trend: more retirement savings, more ETF adoption, and more demand for low-cost, diversified products. In other words, while traders obsess over quarter-to-quarter noise in chip demand or iPhone shipments, the long-term investment case for BlackRock is tied to compounding assets under management and operating leverage across global markets.
Nvidia Corp — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
The analyst calls also reinforce the wider AI trade beyond Nvidia itself. Wells Fargo upgraded Venture Global on confidence in its ability to execute on AI data-center power demand, and JPMorgan initiated nVent Electric as overweight as another data-center beneficiary. HSBC, by contrast, stayed bearish on CoreWeave, warning about debt-market pressure and moderating large language model revenue. That split captures the key investor question of this cycle: which companies are providing the picks and shovels for AI infrastructure, and which are simply borrowing too much to stay in the game?
For investors, the lesson is not that AI is over or that megacap tech has lost its edge. It is that the easy part of the trade may be over. The market is shifting from narrative expansion to earnings discrimination, and that typically favors companies with strong balance sheets, recurring revenue and visible cash generation. Nvidia still fits that mold better than most. Apple will need to prove it can reaccelerate. BlackRock looks like a quieter but attractive compounding story if markets stay healthy and assets continue to migrate into its platforms.
If you are building a long-term portfolio, this is the kind of tape that argues for patience and diversification rather than heroics. AI remains a powerful secular theme, but the best returns often go to investors who own the ecosystem broadly — not just the most popular ticker. The Tuesday calls suggest Nvidia, Apple and BlackRock are still worth watching closely, but for very different reasons.
| Entity | Gains | Losses |
|---|---|---|
| Nvidia | ▲AI demand leadership stays intact | ▼Traders chasing a fresh catalyst |
| Apple | ▲Patient long-term owners if growth reaccelerates | ▼Investors expecting an immediate reset in demand |
| BlackRock | ▲Compounding from ETF and asset growth | ▼Skeptics of a slower but durable earnings story |
| CoreWeave | ▲Higher-growth AI bulls if execution improves | ▼Credit-sensitive investors and short sellers |