Nvidia’s dominance in AI hardware may prove only the first chapter of a much larger wealth transfer, with valuation expert Aswath Damodaran arguing that the biggest long-term gains from artificial intelligence are more likely to accrue to an as-yet-unknown application company than to today’s infrastructure leaders.
Nvidia and AI value may shift to apps
The thesis matters because it goes to the heart of how investors should value the AI boom. Nvidia has become the market’s clearest proxy for artificial intelligence, yet history suggests the firms that lay the pipes are rarely the ones that keep the richest economics once the technology matures. Damodaran, the NYU Stern professor long known as the “Dean of Valuation,” is drawing a direct line from Cisco and Sun Microsystems in the dot-com era to Nvidia and OpenAI today, arguing that the permanent, compounding value will likely settle elsewhere.
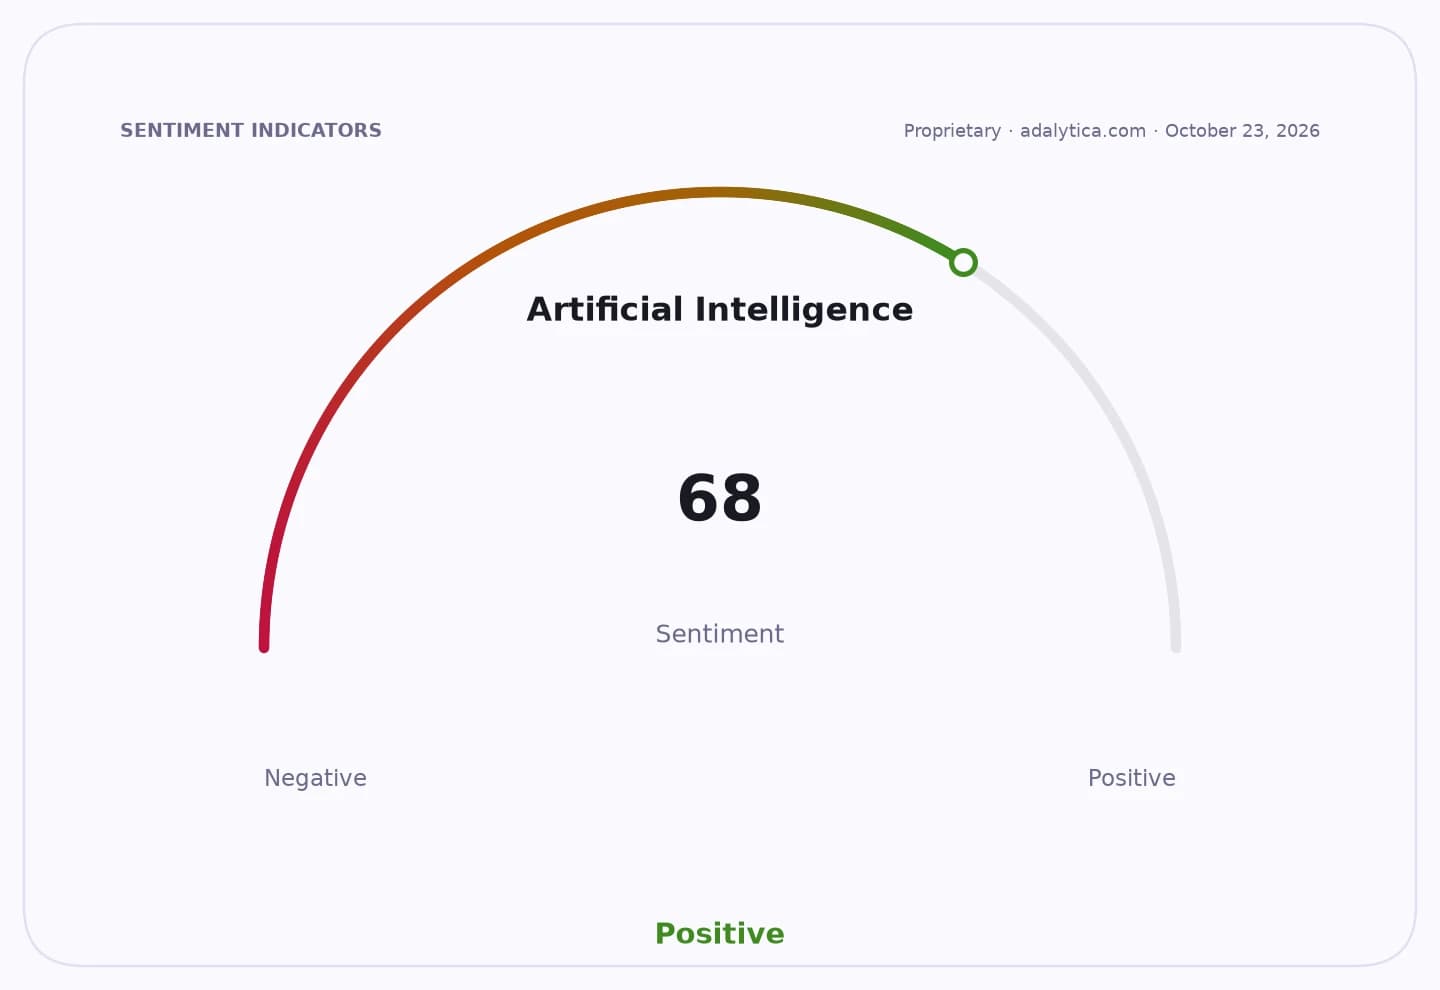
Sentiment IndicatorsⓘProprietary · adalytica.com · October 25, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That argument lands at a moment when the stakes are unusually high. Nvidia’s market value has surged above $3 trillion, while Big Tech’s annual spending on AI infrastructure has topped $200 billion, creating what may be the most capital-intensive technology buildout in decades. OpenAI has also reportedly crossed $5 billion in annual revenue, but its economics remain tied to a costly race to keep frontier models ahead of rivals such as Anthropic, Google’s Gemini, Meta’s Llama, Mistral and a wave of Chinese competitors. Goldman Sachs and others have flagged power and data-center constraints as a growing bottleneck, underscoring how much of the current AI opportunity is still being monetized through infrastructure rather than end-user software.
For investors, the relevance is not that Nvidia or OpenAI are poor businesses. It is that infrastructure leaders can be extraordinary businesses without being the ultimate long-term winners of a platform shift. In the internet era, Cisco built the backbone and Amazon captured the durable value. Damodaran’s framework says AI is more likely to follow that pattern than to break it. The implication is particularly important for investors who have treated Nvidia as a perpetual monopoly on AI profits. Competitive pressure is already rising from AMD, Intel, Google’s custom TPUs, Amazon’s Trainium and a growing universe of startups, while the model layer faces price pressure as capabilities commoditize.
The market backdrop reinforces that caution. Nvidia’s shares have been volatile even after huge gains, with the stock recently trading below its 50-day moving average and its relative strength index sliding into oversold territory on the supplied price data. That does not invalidate the bull case; it does suggest investors are no longer paying for a one-way narrative. Microsoft, meanwhile, remains one of the heaviest spenders in AI and still trades well above its 200-day average, showing that the market continues to reward companies with both distribution and infrastructure exposure. But Damodaran’s point is that the real prize may not belong to the seller of chips or models at all, but to the company that turns AI into a consumer or enterprise habit with network effects and retention.
That is why the “next Amazon” question matters more than the “next Nvidia” question. If AI follows prior technology cycles, the largest fortunes will not come from owning the most expensive hardware today, but from owning the interface, workflow or consumer destination that makes AI indispensable once infrastructure costs normalize. The challenge for investors is that such a company may not exist yet, which means the most consequential AI gains could still be sitting outside the current roster of market favorites.
For now, the investable message is two-sided. The bull case is that Nvidia and OpenAI can remain central beneficiaries for years if AI spending keeps compounding and inference demand expands faster than competition can erode pricing. The bear case is that margins and terminal value shift down the stack, leaving today’s infrastructure champions with strong but finite economics, while the future trillion-dollar winner emerges from an unrelated sector that has not yet been anointed as an AI play.
The most important catalyst to watch is whether AI spending starts producing durable consumer and enterprise applications with genuine retention, rather than just larger capital budgets. If that happens, the market’s attention may shift from who builds the chips to who captures the user relationship.
| Entity | Gains | Losses |
|---|---|---|
| Nvidia | ▲Near-term AI capex boom | ▼Long-run pricing power |
| OpenAI | ▲Frontier-model demand | ▼Margin durability |
| Future AI application company | ▲Network effects, compounding value | ▼— |
| Late-cycle infrastructure buyers | ▲Access to cheap pipes | ▼Early-cycle valuation premiums |