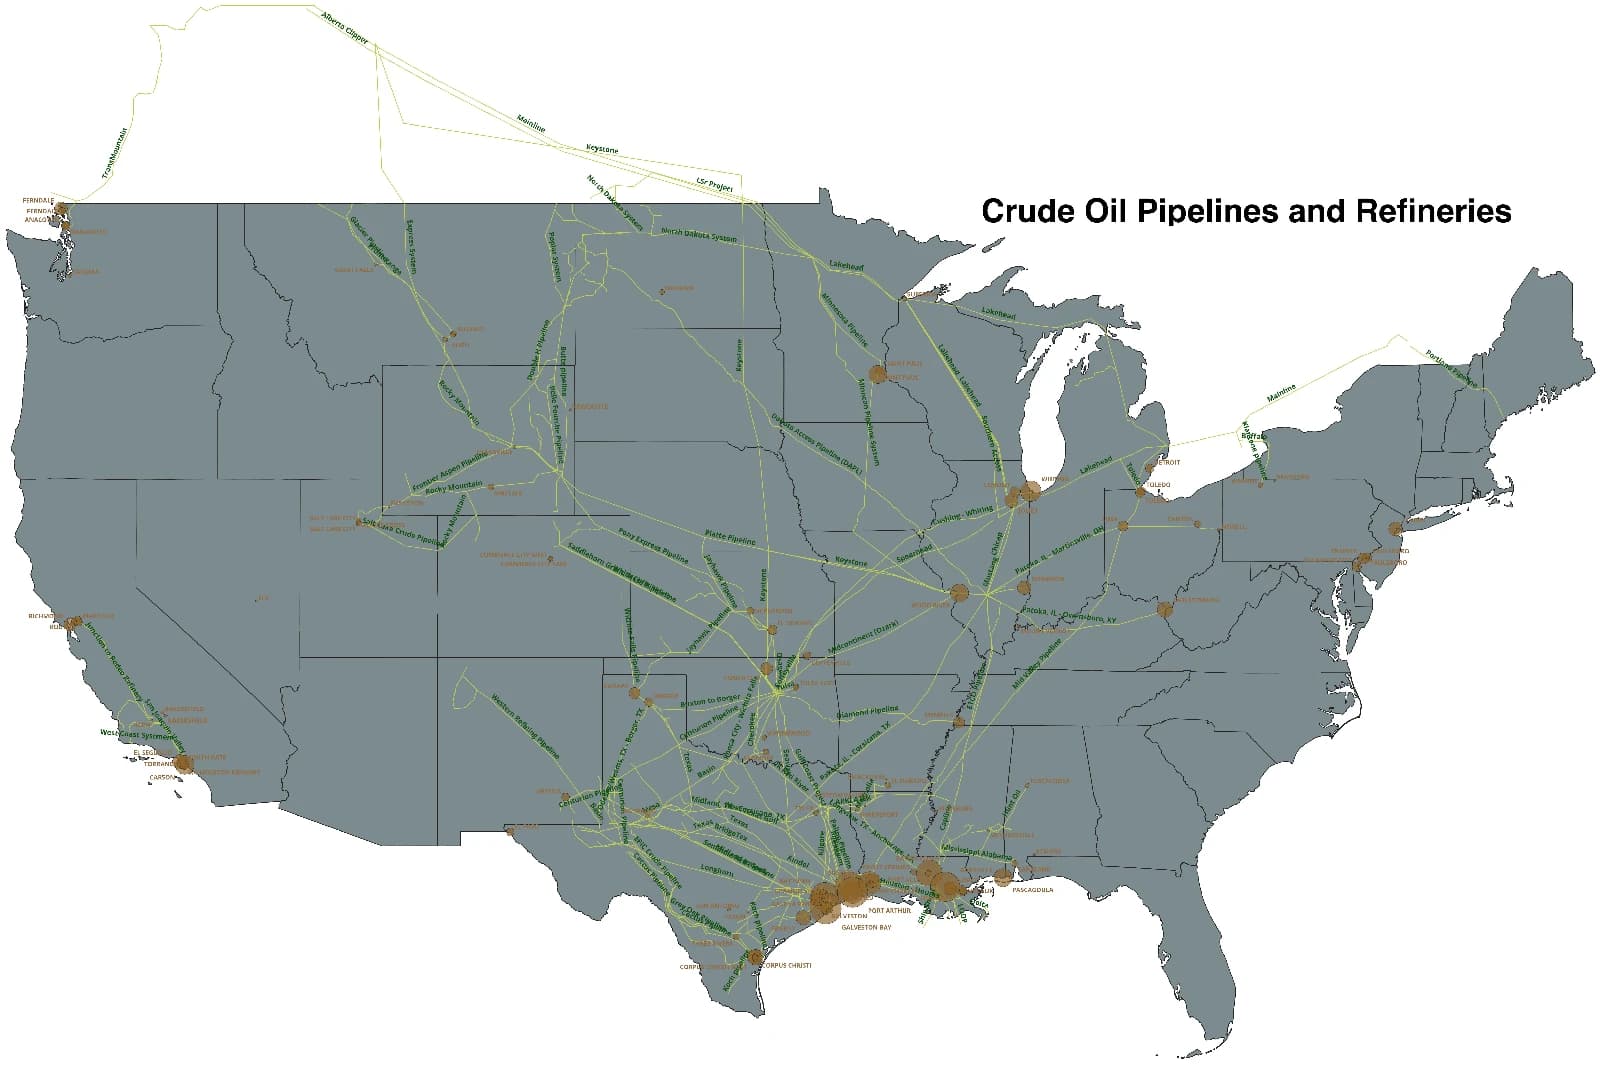
Global markets are being hit by the same two forces that can turn a garden-variety pullback into a real regime change: a fresh oil shock and renewed sovereign-debt anxiety in Europe.
Oil Surge and France Yield Spike Hit Global Markets
Brent crude’s surge toward $112 a barrel is the immediate economic threat because it feeds directly into inflation, transport costs and corporate margins just as investors were already questioning the durability of the global recovery. At the same time, France’s 10-year yield climbing to 5.11% and its spread over German bonds widening to about 170 basis points shows fiscal stress is no longer a local problem — it is becoming a market-wide risk premium that can tighten financial conditions across Europe.
Sentiment Indicators
That is why the selloff has spread from Asia to Europe and into US futures. China’s CSI 300 fell 1.8%, extending a slide of roughly 20% since June and reinforcing the view that the world’s second-largest economy is stuck in a bear market. Japan’s Nikkei 225 dropped 2.7%, South Korea’s Kospi lost 3.5% and Hong Kong’s Hang Seng fell 3%, a reminder that higher energy prices are especially punishing for import-dependent economies. When oil rises this fast, the market does not just price expensive gasoline — it prices weaker margins, stickier inflation and less room for central banks to ease.
For investors, the message is broader than one bad session. The combination of expensive crude and wider sovereign spreads is exactly the kind of macro mix that hits growth stocks, cyclicals and leveraged balance sheets at the same time. Nasdaq 100 futures fell 1.8% and S&P 500 futures dropped about 1%, while the latest Adalytica readings on the S&P 500 show “Extreme Fear” even as market awareness remains elevated. That kind of setup usually rewards defensive positioning, energy exposure and quality balance sheets over long-duration growth.
DCOILWTICO vs DGS10 — macro contextadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.
The clearest beneficiaries are the producers and infrastructure names tied to commodities, not the consumers that pay for them. Energy shares have been one of the few areas to hold up, and that makes the case for staying overweight oil-linked assets, from major integrated producers to energy ETFs such as XLE, which has surged alongside crude. USO, the oil ETF, is now trading near 168, reflecting a powerful technical uptrend and a market still chasing supply risk rather than dismissing it.
China remains the weakest link in the chain. Alibaba’s 4% drop after fresh regulatory scrutiny adds another layer of pressure to a market already struggling with growth skepticism and policy uncertainty. The broader implication is that investors are being forced to choose between regions and sectors, not just stocks — favoring commodity winners, safe-haven bonds and defensive cash flows while avoiding the most interest-rate-sensitive and regulation-sensitive names.
Europe is the other fault line. Germany is still drawing buyers as the region’s relative safe haven, but France’s rise in borrowing costs is a warning that fiscal credibility matters again. If those spreads keep widening, the European Central Bank may face a familiar dilemma: support stressed sovereign markets without undermining its inflation fight. That tension is exactly what makes this moment dangerous — and exactly why the market is repricing risk so aggressively.
The next catalyst is straightforward: if oil stays near these levels and European spreads remain elevated, the selloff can spread from an acute shock into a slower, more persistent de-rating of global equities. For now, the highest-conviction trade is to stay with energy, avoid vulnerable growth names, and treat Europe’s bond market stress as a signal that this is no ordinary dip.
| Entity | Gains | Losses |
|---|---|---|
| Oil producers | ▲Higher realized prices | ▼Fuel-demand erosion |
| Energy ETFs and majors | ▲Cash-flow upside | ▼Volatility risk |
| European borrowers | ▲None | ▼Higher refinancing costs |
| Global equity buyers | ▲Select entry points | ▼Growth and margin pressure |