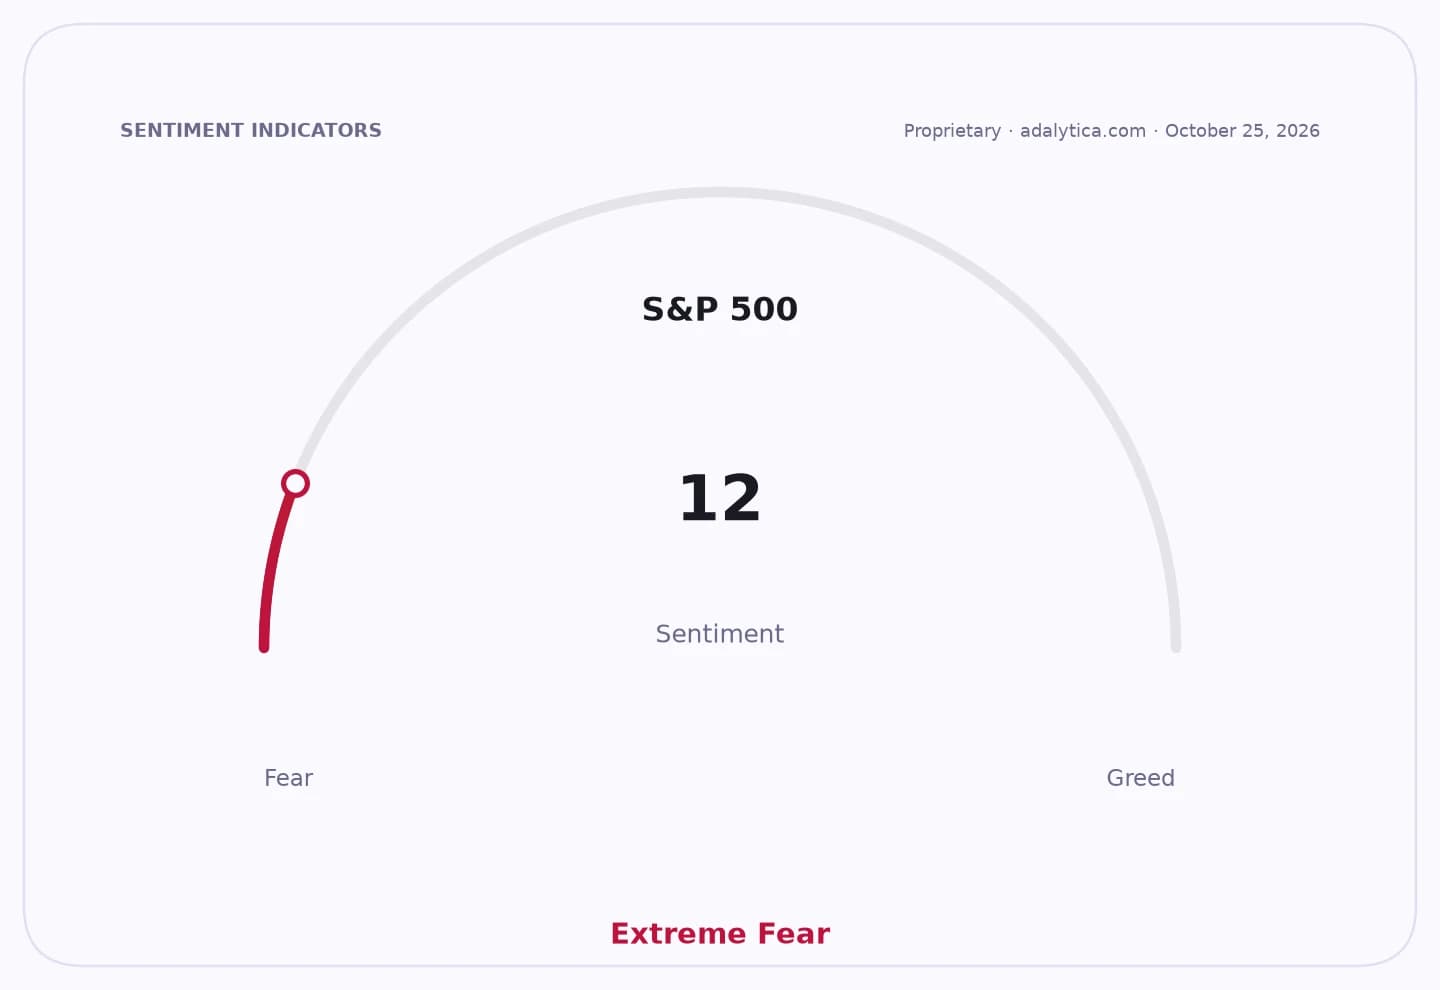
Oil and U.S. bond yields are back in the driver’s seat, and that is the market story investors should care about most on Thursday.
Oil, Yields, and Earnings Pressure Stocks
The combination of Brent above $100 a barrel, a 10-year Treasury yield near 5% and fresh geopolitical uncertainty is tightening financial conditions just as corporate America enters the next stretch of earnings season. That mix matters because it squeezes equity valuations, raises the cost of capital and threatens to erode margins for everything from airlines to consumer staples, even as AI-linked stocks try to justify ever-higher spending.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Crude is doing the most damage at the margin. West Texas Intermediate was trading near $101.5, while Brent was around $109, keeping energy costs high enough to rekindle inflation worries and limit the room for the Federal Reserve and the European Central Bank to ease policy. WTI futures remain well above their 50-day and 200-day moving averages, with RSI readings still elevated, underscoring how persistent the rally has been even after short-term pullbacks. Adalytica’s WTI trade snapshot still shows “Extreme Fear,” a sign that traders are pricing in a market that can gap higher again on any supply shock.
That is the key reason investors are watching the Middle East and the Russia-Ukraine talks so closely. Markets are not simply reacting to headlines; they are pricing the risk that shipping lanes, sanctions policy or a failed ceasefire could keep energy costs pinned near uncomfortable levels. A further spike would feed through to inflation expectations, especially in Europe, where French sovereign stress is already adding another layer of pressure after the 10-year OAT yield moved above 5%.
DCOILWTICO vs DGS10 — macro contextadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
The bond market is adding to the strain. The U.S. 10-year yield around 5% keeps discount rates punitive for long-duration growth stocks, particularly the mega-cap technology names that have powered the rally. That is why Nvidia, SpaceX-linked optimism and the broader AI trade matter so much in this setup: the market is still willing to fund exponential capex for compute and data centers, but only if earnings can keep pace with the spending. Nvidia’s turnkey DGX POD push is exactly the kind of product that can extend the AI infrastructure buildout, but it also highlights how much real capital is being deployed — and how quickly investors could punish any slowdown.
The earnings calendar will test that thesis immediately. Results from Procter & Gamble, Lockheed Martin, Nokia, American Airlines, Spotify, Comcast and Honeywell will give investors a read on whether pricing power, defense demand and travel recovery can absorb higher energy costs and tighter financing conditions. Tesla’s stronger-than-expected quarter, with profit of $4.4 billion, showed how quickly a single name can reset sentiment, but it also reminded the market that the winners are being rewarded for scale, cash generation and optionality, not just narrative.
For investors, the message is straightforward: this is not a market where every growth stock wins. The higher-probability trade is still in the picks-and-shovels beneficiaries of energy security, defense and AI infrastructure, while capital-intensive airlines, refiners exposed to compression in crack spreads, and richly valued software names remain vulnerable if yields stay high and oil stays elevated.
I believe the market underestimates how durable this regime can be. If geopolitics keeps oil supported and long rates refuse to fall, the next leg of returns is likely to favor producers, defense contractors, select industrials and infrastructure names tied to power demand and data-center buildout. The risk is not just higher volatility; it is a prolonged repricing of what investors will pay for future growth. Position early, and stay selective.
| Entity | Gains | Losses |
|---|---|---|
| Energy producers | ▲Higher realized prices | ▼Demand destruction risk |
| Oilfield services | ▲More drilling activity | ▼Project delays if volatility spikes |
| Defense contractors | ▲Higher security budgets | ▼Peace-talk headlines |
| Long-duration tech stocks | ▲AI capex enthusiasm | ▼Higher discount rates |