Ornua’s higher September Purchase Price Index is pointing to better farmgate milk returns across Ireland just as global dairy prices firm, a welcome lift for producers heading into the autumn milk payment cycle.
Ornua September PPI rises to 135.8
The cooperative said its PPI rose to 135.8 from 130.4 in August, implying an indicative milk price of 38.2 cent a litre including VAT for milk at standard fat and protein content, up from 36.2 cent. The 2c/L increase matters because it improves cash flow for dairy farmers at a time when feed, energy and financing costs remain sensitive, and it suggests processors are capturing firmer market conditions after a softer stretch.
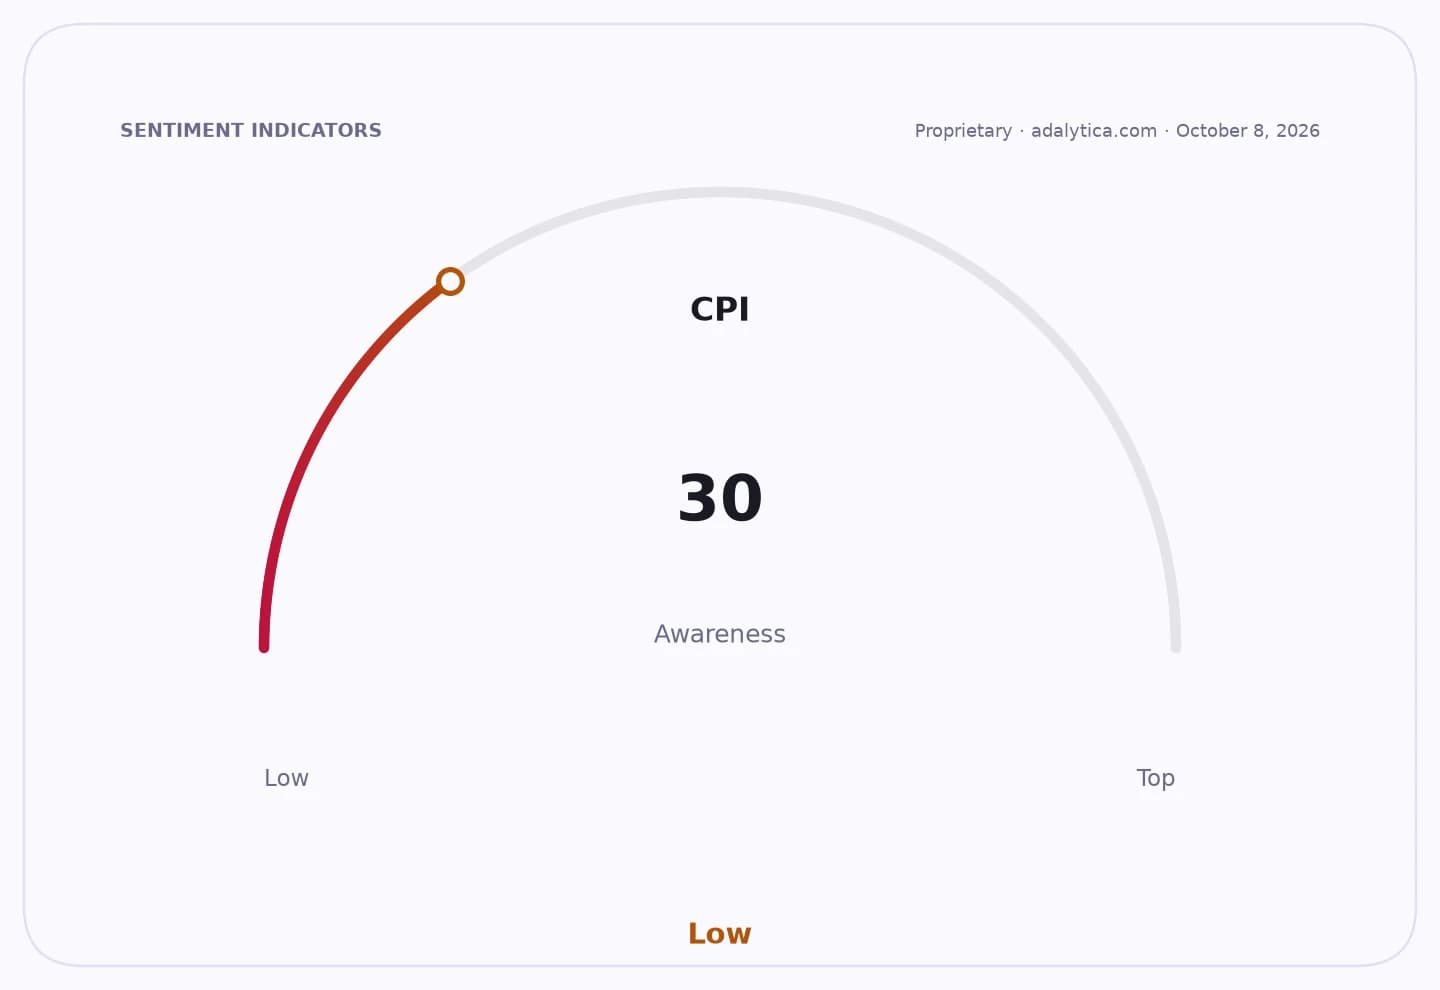
Sentiment IndicatorsⓘProprietary · adalytica.com · October 9, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Ornua said the move reflects stronger market returns in September, though it also warned the PPI does not map perfectly onto actual milk payments because of seasonality. That caveat matters for investors and lenders watching the dairy complex: the index is not a guaranteed cheque, but it is a useful read-through on where commodity pricing is headed and whether farm incomes are stabilizing or deteriorating.
The broader signal from the latest dairy trading is similarly constructive. The Global Dairy Trade index rose 1.2% to 1,177, reversing part of the previous decline, with skim milk powder up 4.3% and whole milk powder up 1.2%. Those gains are important because powder prices tend to drive sentiment across the sector and feed through to export-oriented processors, even as individual products remain mixed.
Not everything moved in the same direction. Lactose, cheddar and mozzarella all fell, while butter was slightly lower and anhydrous milk fat also eased. That split market suggests dairy demand is improving unevenly rather than breaking out in a straight line, which should keep a lid on complacency even as the near-term pricing backdrop turns more supportive.
For investors, the takeaway is that dairy is entering a more favorable pricing phase, and the market may be underestimating how quickly modest commodity improvement can flow through to cooperatives, processors and farm balance sheets. Ornua’s higher PPI, paired with the stronger GDT auction, points to a sector with better earnings visibility than it had a month ago.
The next catalyst will be whether these firmer auction prices hold through the coming trading rounds and translate into sustained milk-price gains. If they do, the winners will be efficient processors and input suppliers with volume exposure; the laggards will be producers and brands still exposed to softer cheese and fat markets. For now, the message is clear: the dairy cycle is improving, and early positioning matters.
| Entity | Gains | Losses |
|---|---|---|
| Ornua/member processors | ▲Higher milk returns | ▼None immediately |
| Dairy farmers | ▲Better farmgate cash flow | ▼Still exposed to seasonality |
| GDT powder sellers | ▲Firmer pricing | ▼Buyers facing higher costs |
| Cheese/fat buyers | ▲No benefit from rally | ▼Lower-priced input advantage fades |