Ourense’s assessed housing value rose 25.4% in five years, underscoring how Spain’s property boom has accelerated unevenly and left some provincial markets well behind the country’s coastal and urban hot spots.
Ourense housing values rise 25.4% in five years
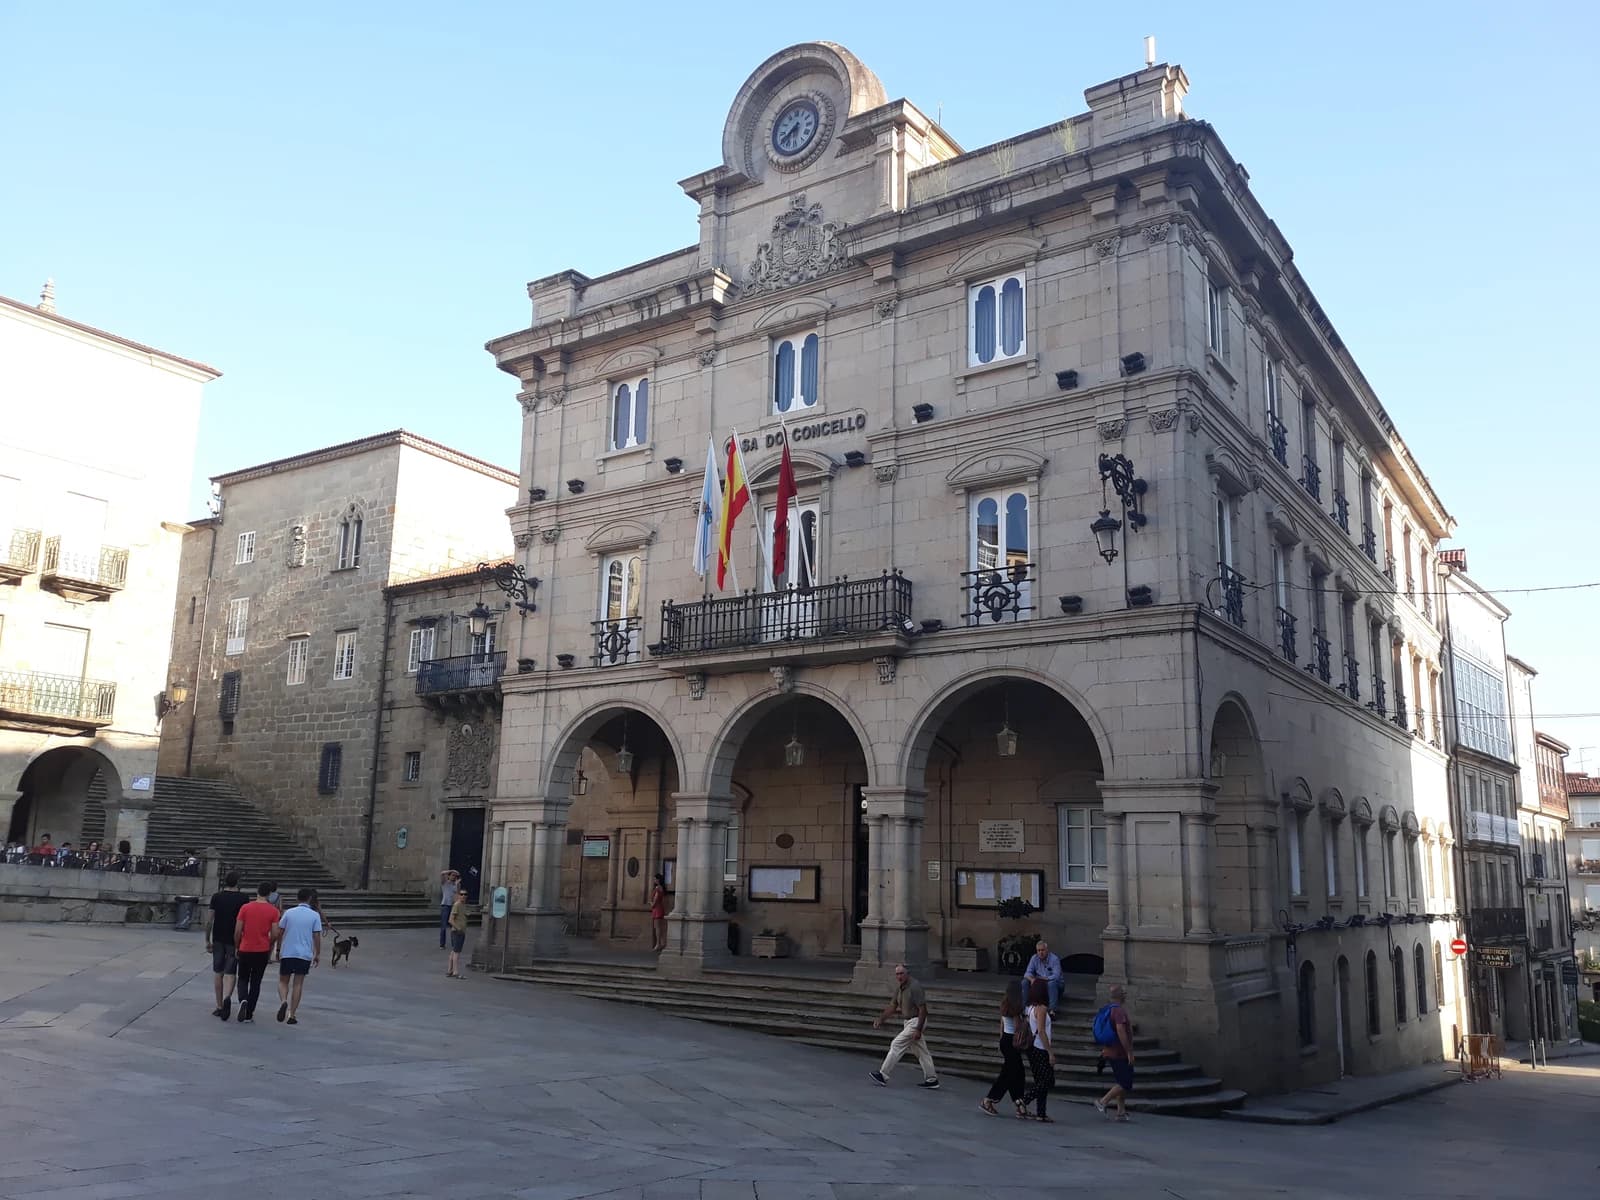
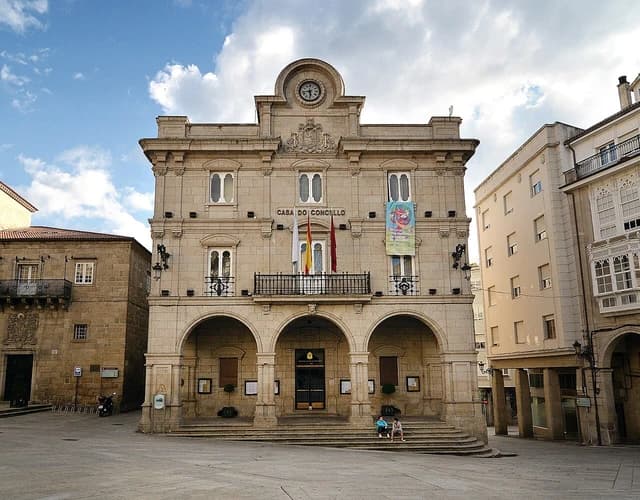
Between March 2021 and March 2026, the average tasación in the Galician city climbed from 1,152.20 euros to 1,445.20 euros a square metre, according to Housing Ministry data. That is a gain of 293 euros a square metre, a respectable increase but one that sits below the national rise of about 42.5% over the same period and far short of the double-digit surges recorded in parts of the Mediterranean coast and the islands.
The figures matter because assessed values are more than a statistical footnote: they are a proxy for the price base that shapes mortgage collateral, household wealth and municipal tax receipts. In a country where housing affordability has become a central political issue, the widening gap between cities such as Ourense and faster-rising markets such as Valencia or Alicante points to a property cycle driven less by a single nationwide shortage than by intense local pressure in high-demand regions.
That divergence is stark. Valencia’s assessed housing value nearly doubled to 2,972.80 euros per square metre, while Alicante rose 96%. Several municipalities in the Valencian Community and along the Mediterranean coast also posted gains of 80% to more than 120%, including Quart de Poblet, Xirivella, Mislata and Burjassot. At the other end of the table, Villarrobledo rose just 9.6%. Galicia as a whole advanced 34.5%, also below the national pace.
For investors, the split has implications across the housing chain. Developers, landlords and lenders with exposure to the strongest markets may benefit from firmer collateral values and pricing power, but they also face greater political and affordability risk as governments come under pressure to act. In slower markets like Ourense, more moderate gains may limit upside for owners but can help preserve access for local buyers and reduce the risk of overheating.
The broader backdrop is a housing crisis that has become a political fault line in Spain, where parliament has recently rejected key measures intended to ease the shortage. That failure has raised the odds of further policy efforts, but the data suggest any national solution will have to contend with a market that is becoming more regionalised by the year.
For investors and policymakers alike, the message from Ourense is that Spain’s housing problem is no longer just about rising prices — it is about which cities are rising fastest, who can still buy, and how difficult it will be to design a fix that fits markets moving at very different speeds.
| Entity | Gains | Losses |
|---|---|---|
| Homeowners in Ourense | ▲Higher assessed wealth | ▼Faster affordability strain elsewhere |
| Buyers in Ourense | ▲Slower price pressure than coastal cities | ▼Still face higher entry costs |
| Coastal/metro markets | ▲Collateral and pricing power | ▼Greater policy backlash risk |
| Spanish policymakers | ▲Clearer evidence of regional divergence | ▼Less room for a one-size-fits-all fix |