Social media is becoming the fastest route for AI-powered scams, and that is bad news for payment platforms, brokerages and anyone monetizing digital identity, because the same user-generated content that drives engagement can now be repurposed into convincing fraud at scale.
PayPal and Robinhood Face AI Fraud Risks
The economic damage is straightforward: AI lowers the cost of impersonation, deepfakes and social engineering, which means more attempted fraud, higher verification costs and greater losses for platforms that sit closest to consumer money. For investors, that shifts the debate from growth alone to trust, compliance and fraud-defense spending — a mix that can compress margins even when transaction volumes look healthy.
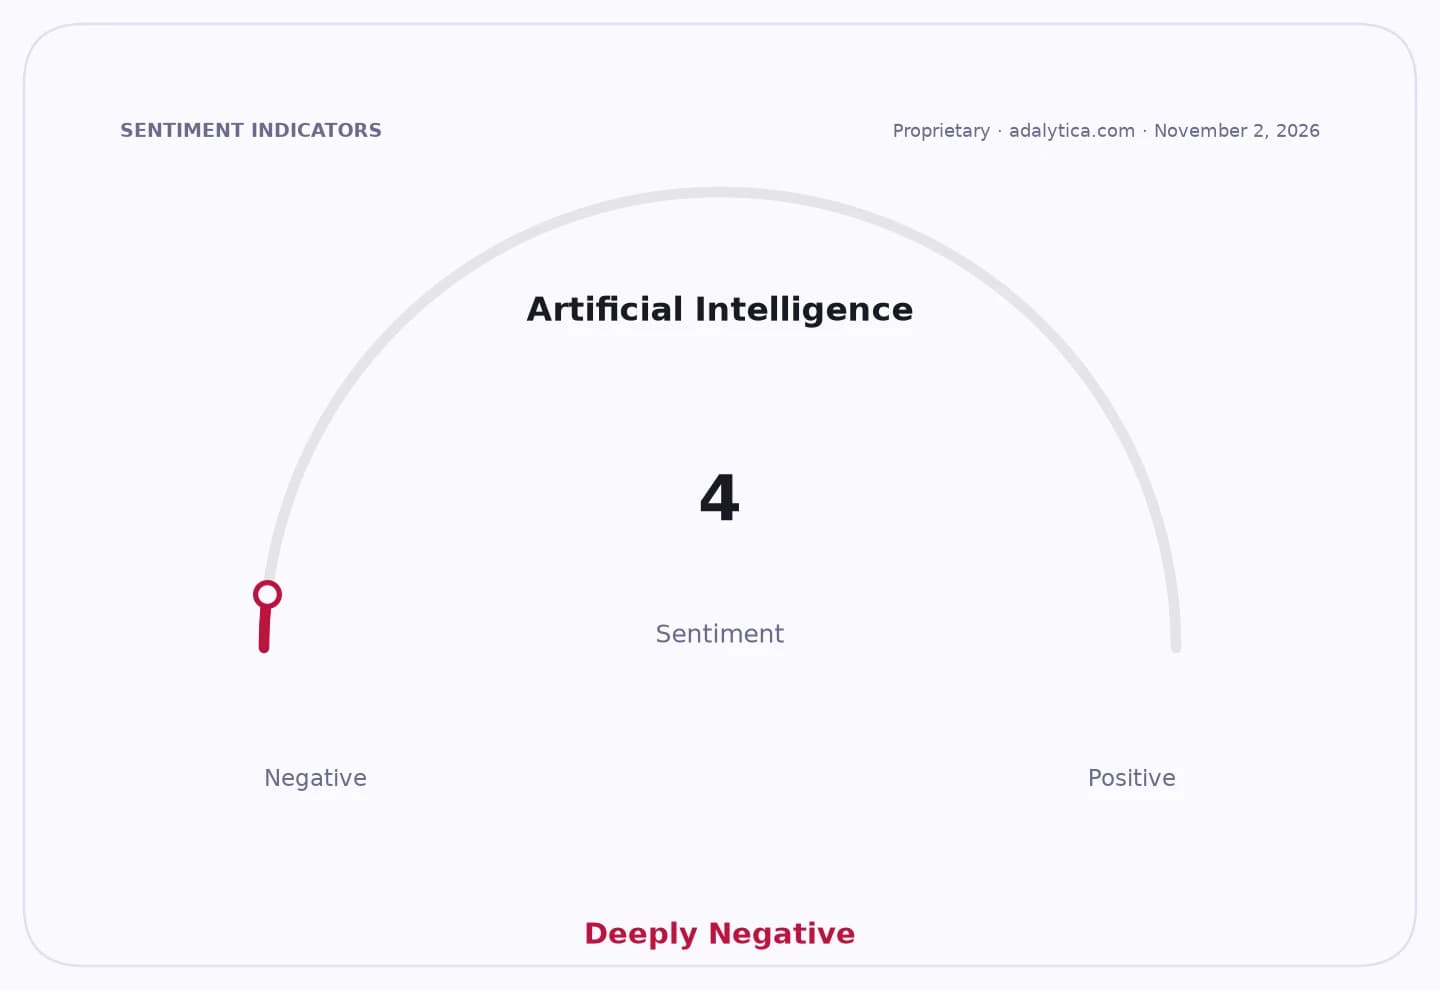
Sentiment Indicators
PayPal is the clearest public-market warning sign. Its shares have been volatile, but the stock remains near the high-$50s after a year that included a slide to $38.74 in February and a sharp rebound to $60.20 on Nov. 4 before easing to $58.96 the next day. The wider point is not the near-term trading pattern — it is that a payments company with a market role built on moving money quickly is exposed when scammers can weaponize social feeds, synthetic audio and fake identity trails. PayPal’s own filing says cybersecurity and information-security risks for global payments companies have increased significantly, and that cyberattacks could seriously harm its reputation, business and financial condition.
Robinhood sits in an even more exposed position. The stock dropped to $78.39 on Nov. 5 from $87.41 the previous session, after a brutal February low near $71.12 and a summer rally that briefly pushed the shares above $117. The company’s platform is increasingly intertwined with AI features, while its filing explicitly warns that generative AI can bring new regulatory scrutiny, litigation and security risks. That matters because scam activity does not just create headline risk; it can drive account verification friction, customer-service costs and a tougher operating environment for a business that depends on fast, frictionless user acquisition.
The broader market message is that AI is not only a productivity story — it is also an adversarial infrastructure story. Every jump in generative capability raises the cost of authentication, moderation and fraud prevention. That is why the real beneficiaries may not be the consumer platforms taking the hits, but the toll-road businesses in identity, fraud scoring, network security and transaction monitoring. Visa’s latest filing underscores the same theme, citing rising cyber and payment-fraud activity tied to ecommerce, social media and mobile channels, and pointing to value-added fraud-prevention tools as a core defense.
Investors should therefore look past the most visible AI names and toward the picks-and-shovels layer that gets paid whether scams rise or user behavior changes. The market underestimates how persistent this spending can be: once fraud becomes AI-assisted, it is not a one-off fix but a permanent line item. That gives a structural tailwind to payment security, identity verification and risk analytics providers, while leaving the consumer-facing platforms with an ugly choice between tighter controls and more losses.
The takeaway is simple: the next AI trade is not just about building models, but defending the plumbing they can exploit. In a world where a social post can become a fraud script, investors should favor the companies selling trust, not just transactions.
| Entity | Gains | Losses |
|---|---|---|
| Fraud-prevention vendors | ▲Higher demand | ▼— |
| PayPal | ▲— | ▼Higher scam exposure |
| Robinhood | ▲— | ▼More verification and compliance costs |
| Visa | ▲Fraud tools demand | ▼Higher payment-fraud pressure |