Mortgage demand in Poland cooled in August after a half-year surge, with the value of housing-loan inquiries still up 9.3% from a year earlier but down sharply from July as seasonal weakness and refinancing activity began to fade.
Poland Mortgage Demand Eases After Summer Surge

The latest estimate from the BIK credit bureau shows banks and credit unions received applications from 7% more people than a year earlier, but 14.4% fewer than in July. On a like-for-like basis with BIK’s last published count, the number of applications likely fell to about 36,000 in August, slipping below 40,000 for the first time in six months.
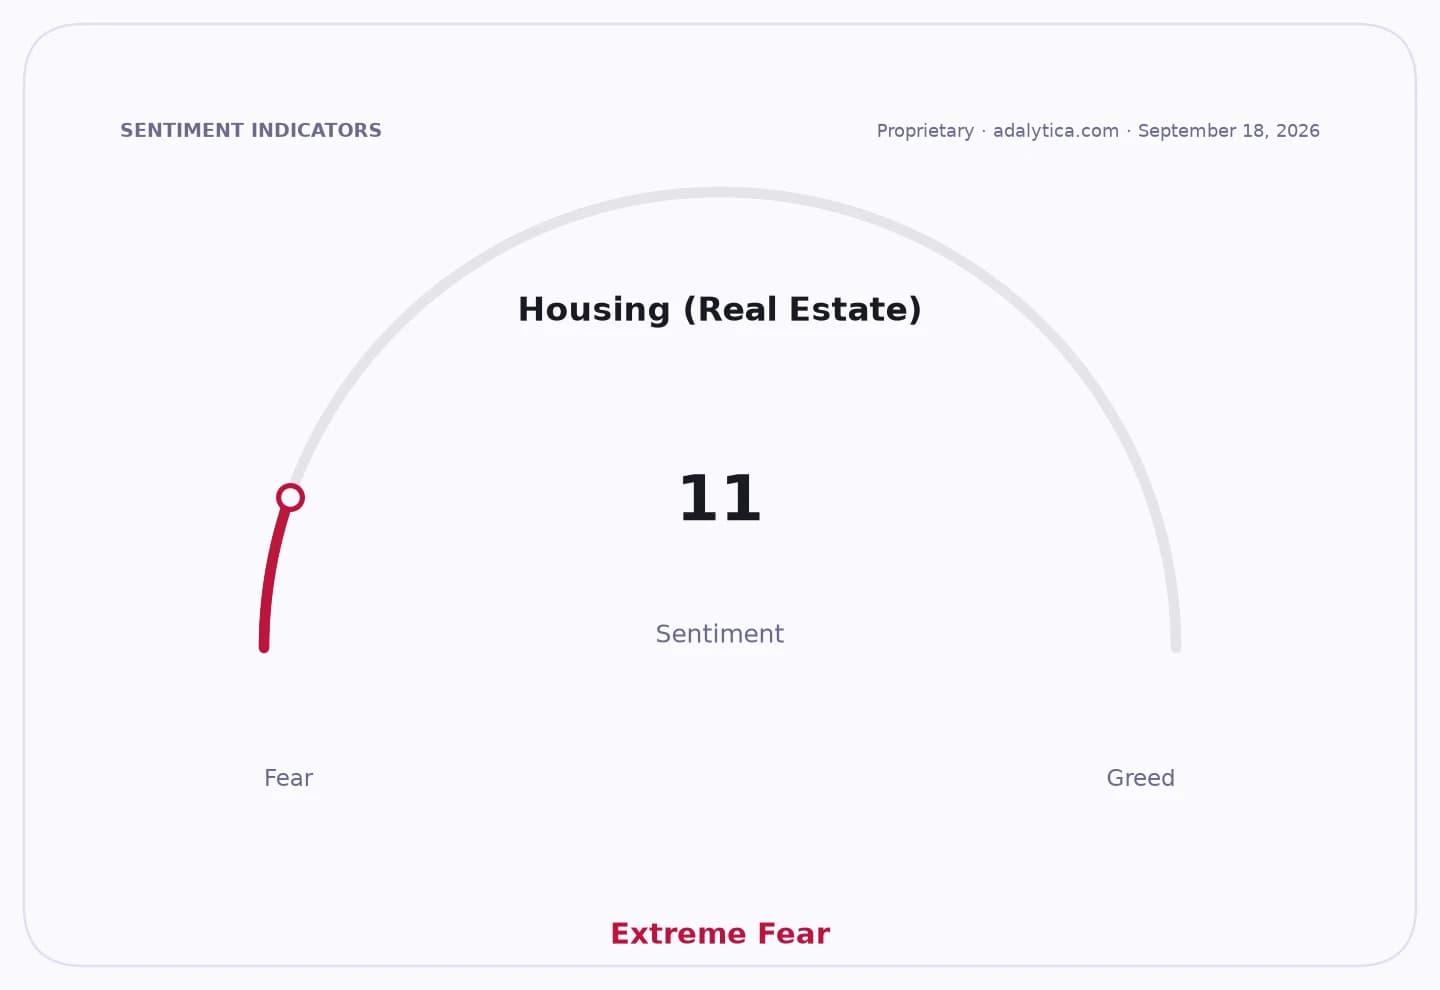
Sentiment IndicatorsⓘProprietary · adalytica.com · September 10, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because Poland’s housing market has been one of the region’s clearest beneficiaries of lower borrowing costs and stronger wages. In July, lenders booked a record 14.78 billion zlotys in mortgage loans, bringing seven-month originations to 88.9 billion zlotys, 57% more than a year earlier, helped by improved affordability and a wave of refinancing from borrowers locked into older, higher fixed rates.
August’s pullback suggests some of that momentum is normalizing, even if demand remains solid. The average requested mortgage rose to 525,700 zlotys, up 7.2% from a year earlier, showing that households are still chasing larger loans and that prices and borrowing needs remain elevated.
BIK chief analyst Waldemar Rogowski said the monthly pace of borrower growth will likely ease further because comparisons get tougher in 2026, after 2025 already saw a rebound in mortgage demand. He also said applications are still running above last year’s level, with refinancing making up more than a third of current lending activity.
For investors, the data point to a market that is still healthy but no longer accelerating. Polish banks tied to mortgage lending may keep seeing respectable loan growth, but the mix is shifting away from the July-style surge in refinancing and record issuance, which could temper expectations for near-term upside in housing finance.
The broader housing picture is mixed rather than weak. Otodom estimated that developers sold more than 4,300 homes in August across seven major markets, up 25% from a year earlier, while more than 32,000 new homes were sold in the first eight months of the year, up 40% annually.
With mortgage inquiries easing and home sales still firm, the next test is whether the autumn market can preserve demand once the summer distortions fade and comparisons get harder.
| Entity | Gains | Losses |
|---|---|---|
| Polish banks | ▲steady loan volumes | ▼July-style refinancing boom |
| Homebuyers | ▲still-easier affordability | ▼less urgent rate-driven demand |
| Developers | ▲resilient unit sales | ▼risk of slower mortgage momentum |
| Borrowers with old fixed rates | ▲refinance opportunities | ▼cheaper-late-cycle pricing power |