PV GAS reported a 33% jump in nine-month profit and is heading into a planned state stake sale by parent PVN, putting the Vietnamese gas major in the spotlight as stronger earnings and a tighter free float converge.
PV GAS profit rises ahead of PVN stake sale
The company’s net profit after tax rose to 13.5 trillion dong in the first nine months of 2026, more than halfway above its full-year target and already equal to 150% of its profit plan, according to an ACBS Securities update. Revenue climbed 32% to nearly 121 trillion dong, while third-quarter profit surged 74% from a year earlier to 4.5 trillion dong.
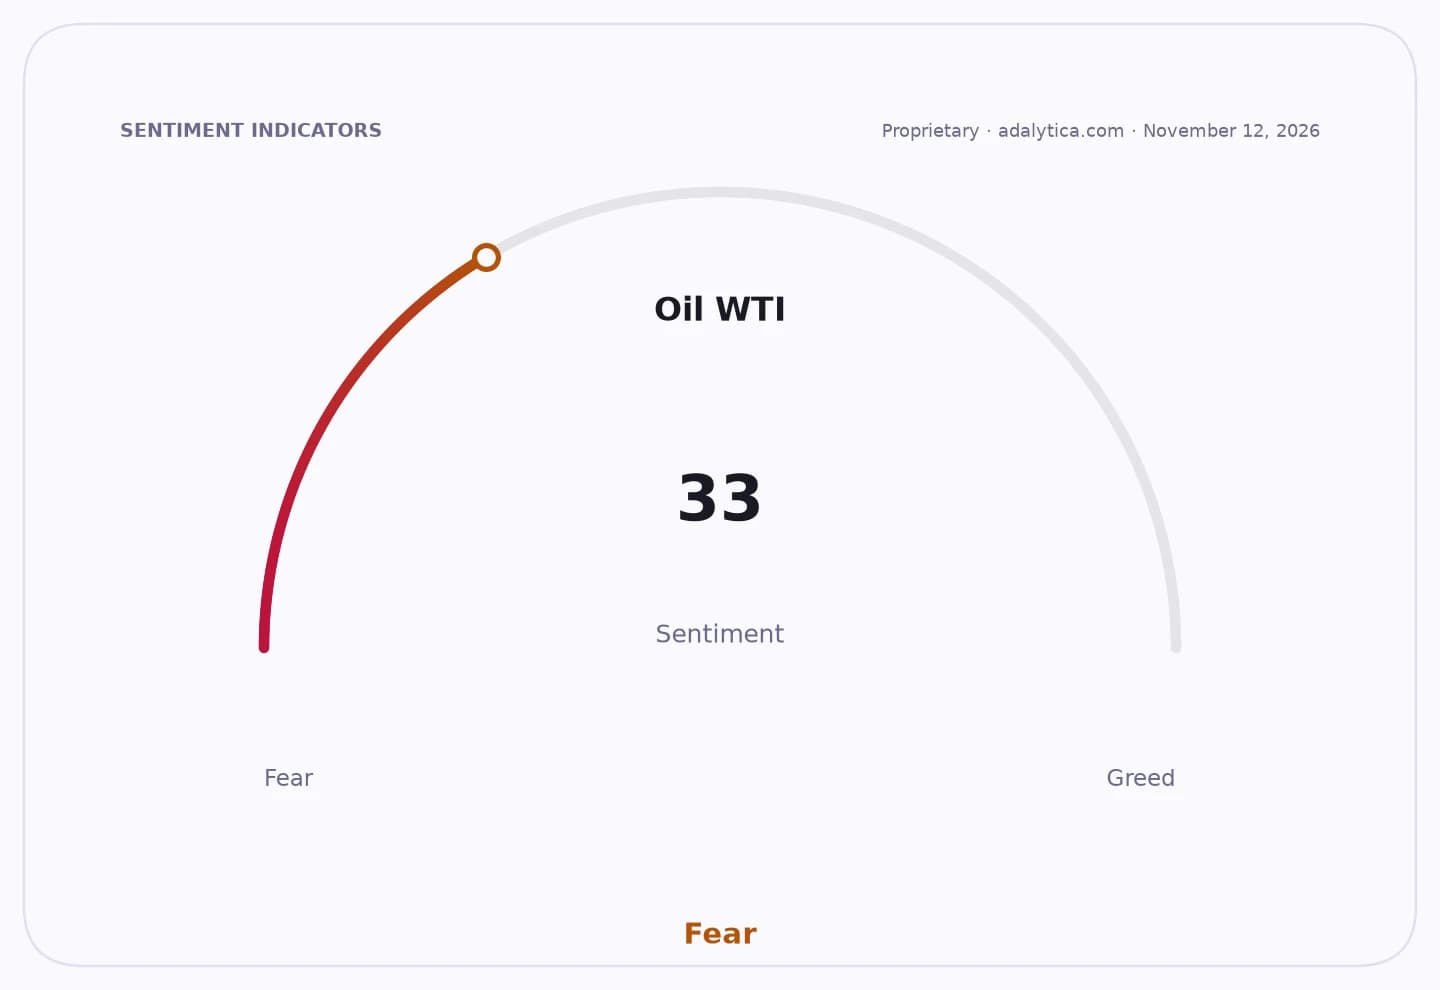
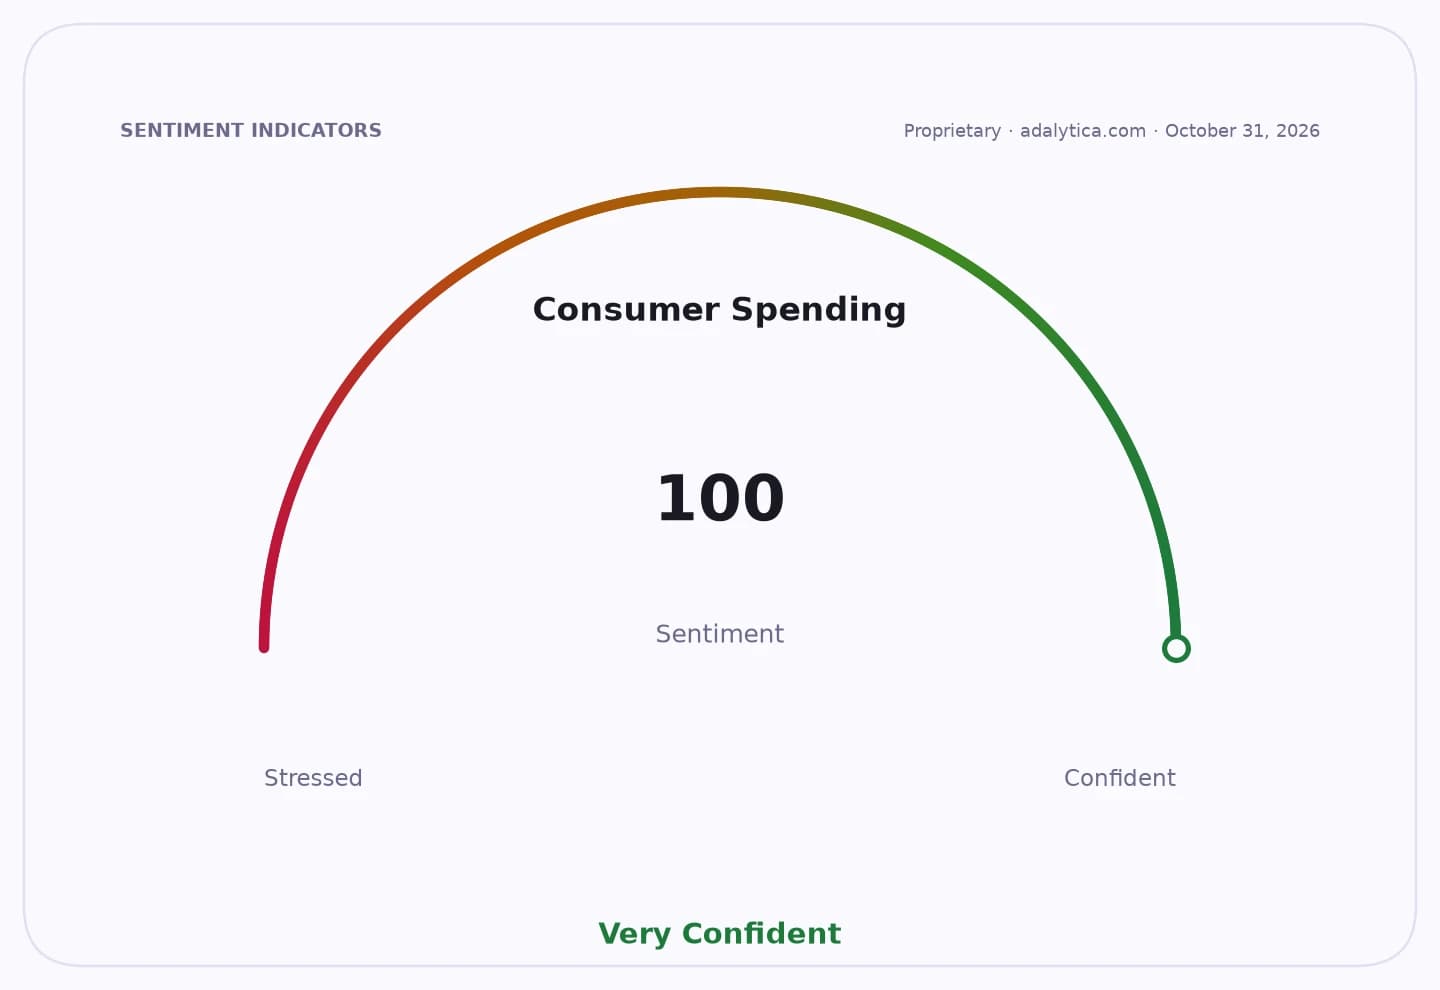
Sentiment Indicators
The earnings beat matters because it gives PV GAS more room to absorb volatility in energy prices and strengthens the case for a richer valuation ahead of PVN’s divestment. ACBS said crude prices were a key driver, with Brent averaging about $97 a barrel in the third quarter, up 40% from a year earlier, lifting gas and LPG selling prices faster than input costs.
Gross margin widened to 15.7% in the quarter from 11.5% a year earlier, helped by higher dry gas and LPG prices and slower growth in domestic gas purchase costs. Sales of dry gas and LNG rose nearly 24% to 1.8 million cubic meters, while selling and administrative expenses as a share of revenue fell to 2.2% from 3.4%.
The broker lifted its 2026 profit forecast for PV GAS by 12% and nudged its 2027 estimate up 5%, projecting net income of 15.8 trillion dong in both years. It also raised its target price for the stock to 99,800 dong, versus 73,200 dong on Nov. 12, implying about 36% upside, before counting an expected 3% dividend yield.
PVN plans to sell at least 5.76% of PV GAS to meet public-company requirements, with valuation work due to finish in December 2026 and the shares to be auctioned on the stock exchange. PVN currently owns 95.76% of the company, so the stake sale would slightly dilute its control while potentially broadening the shareholder base and improving market liquidity.
Investors will now watch whether oil stays high enough to support prices into 2027 and whether new gas projects, including Block B - O Mon expected to begin first gas at the end of 2027, can sustain volume growth. If Brent slips below $90 a barrel, ACBS said pricing pressure could offset production gains, leaving earnings broadly flat next year.
| Entity | Gains | Losses |
|---|---|---|
| PV GAS | ▲Higher earnings and valuation support | ▼More exposure if oil falls below $90 |
| PVN | ▲Cash from divestment and compliance with listing rules | ▼Reduced ownership and control |
| Existing shareholders | ▲Potential liquidity boost and upside from rerating | ▼Dilution from new share sale |
| Buyers of GAS shares | ▲Entry into a profitable gas asset | ▼Risk of price normalization after strong oil-led gains |