High supply is keeping a lid on UK asking prices just as mortgage costs climb back up and buyers turn more selective, making the autumn housing market more of a pricing test than a recovery.
Rightmove: UK asking prices flat as supply rises
Rightmove said the total number of homes for sale is at its highest level for this time of year since 2014, a backdrop that is forcing sellers to compete on price rather than rely on scarcity to do the work. Its latest index showed average asking prices for new listings were broadly flat in October, up 1% on the month to £371,015 and down 0.1% from a year earlier, with average sale activity and buyer enquiries both weaker than a year ago.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 24, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
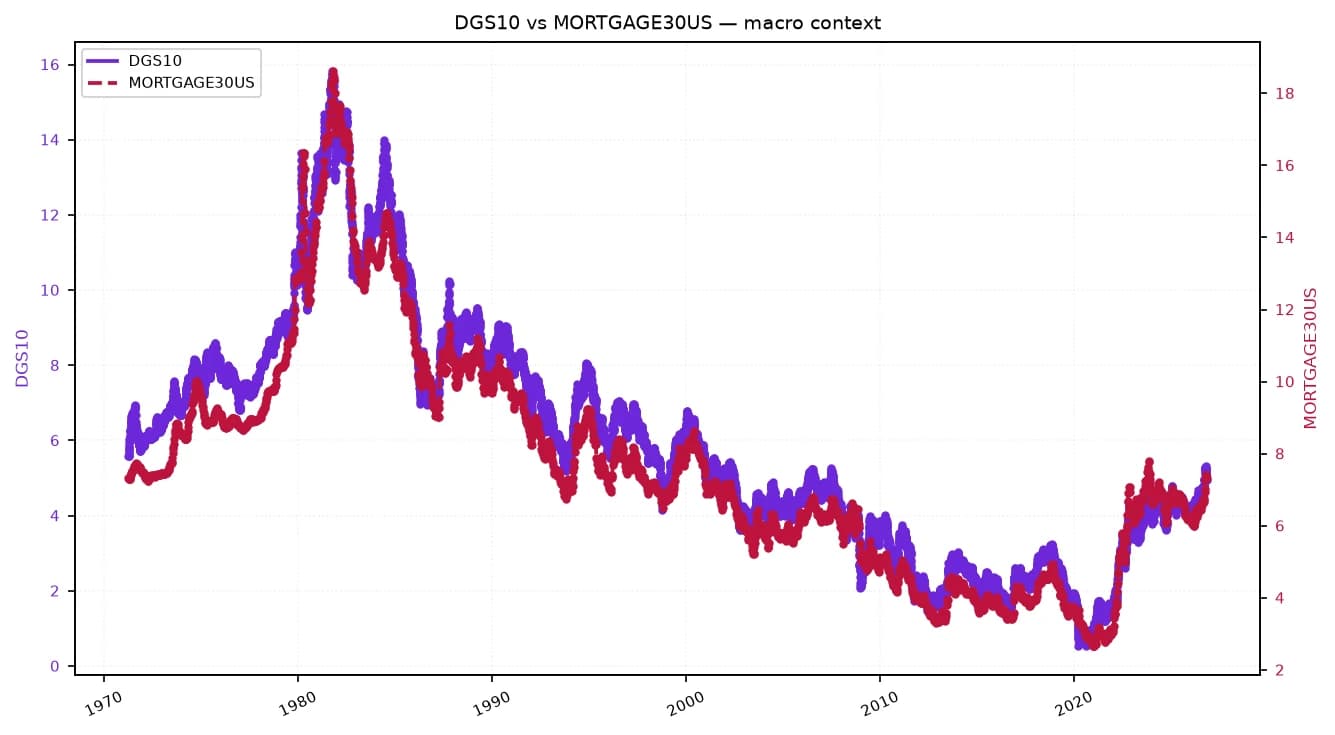
That matters because the UK housing market is already absorbing another squeeze from finance costs. Rightmove said the average two-year fixed mortgage rate has risen from 5.29% to 5.55%, eroding affordability at a time when sales agreed are down 8% year on year and new buyer enquiries are 9% lower. More stock, fewer bidders and higher borrowing costs is a classic recipe for softer pricing power, particularly in lower-priced markets where affordability is most stretched.
The strain is showing unevenly across the country. Average asking prices fell in almost five regions last month, with the North East down 2% to £195,977, Scotland off 1.9% to £203,415 and the North West down 0.6% to £273,222. Wales and the South West also slipped. London was the outlier, with asking prices up 2.5% on the month, though Rightmove said that looks more like a partial bounce after a 6% summer decline than the start of a wider rebound.
For investors, the message is that the housing slowdown is becoming more transactional than dramatic: sellers are still listing, but they are meeting buyers who are more rate-sensitive and less willing to chase prices. That tends to cap upside for estate agents and property portals, while keeping pressure on builders to offer incentives, discount selectively or lean harder on affordable product lines.
The broader macro backdrop is also working against a quick turn. Propertymark said inflation has not yet returned to the Bank of England’s 2% target, leaving borrowing costs elevated and mortgage choices constrained. Rightmove added that some buyers may be waiting for details of the government’s Your First Home scheme in the Budget later this month, suggesting policy expectations may be delaying decisions rather than lifting demand.
For now, the market narrative is straightforward: supply is abundant, mortgage rates are higher, and buyers know it. That leaves competitive pricing from day one as the main route to a sale, while any sustained improvement in asking prices will probably need either lower borrowing costs or a clearer policy boost to demand.
| Entity | Gains | Losses |
|---|---|---|
| Buyers | ▲More choice | ▼Less urgency |
| Sellers | ▲Well-priced homes | ▼Pricing power |
| Estate agents | ▲Faster deals on realistic listings | ▼Longer sales cycles |
| Housebuilders | ▲Affordable inventory demand | ▼Margin pressure |