Romania’s competitiveness is increasingly being eroded by labor costs, with economists and union voices arguing that the country is no longer an outlier for cheap workers in the European Union.
Romania labor costs rise as cheap-work edge fades
The debate matters because it goes to the heart of how Romania attracts investment, retains workers and grows without relying on wage suppression. If labor is no longer cheap, the country’s edge shifts from low-cost manufacturing and service work toward productivity, skills and capital investment — a change with direct implications for profits, public policy and household incomes.
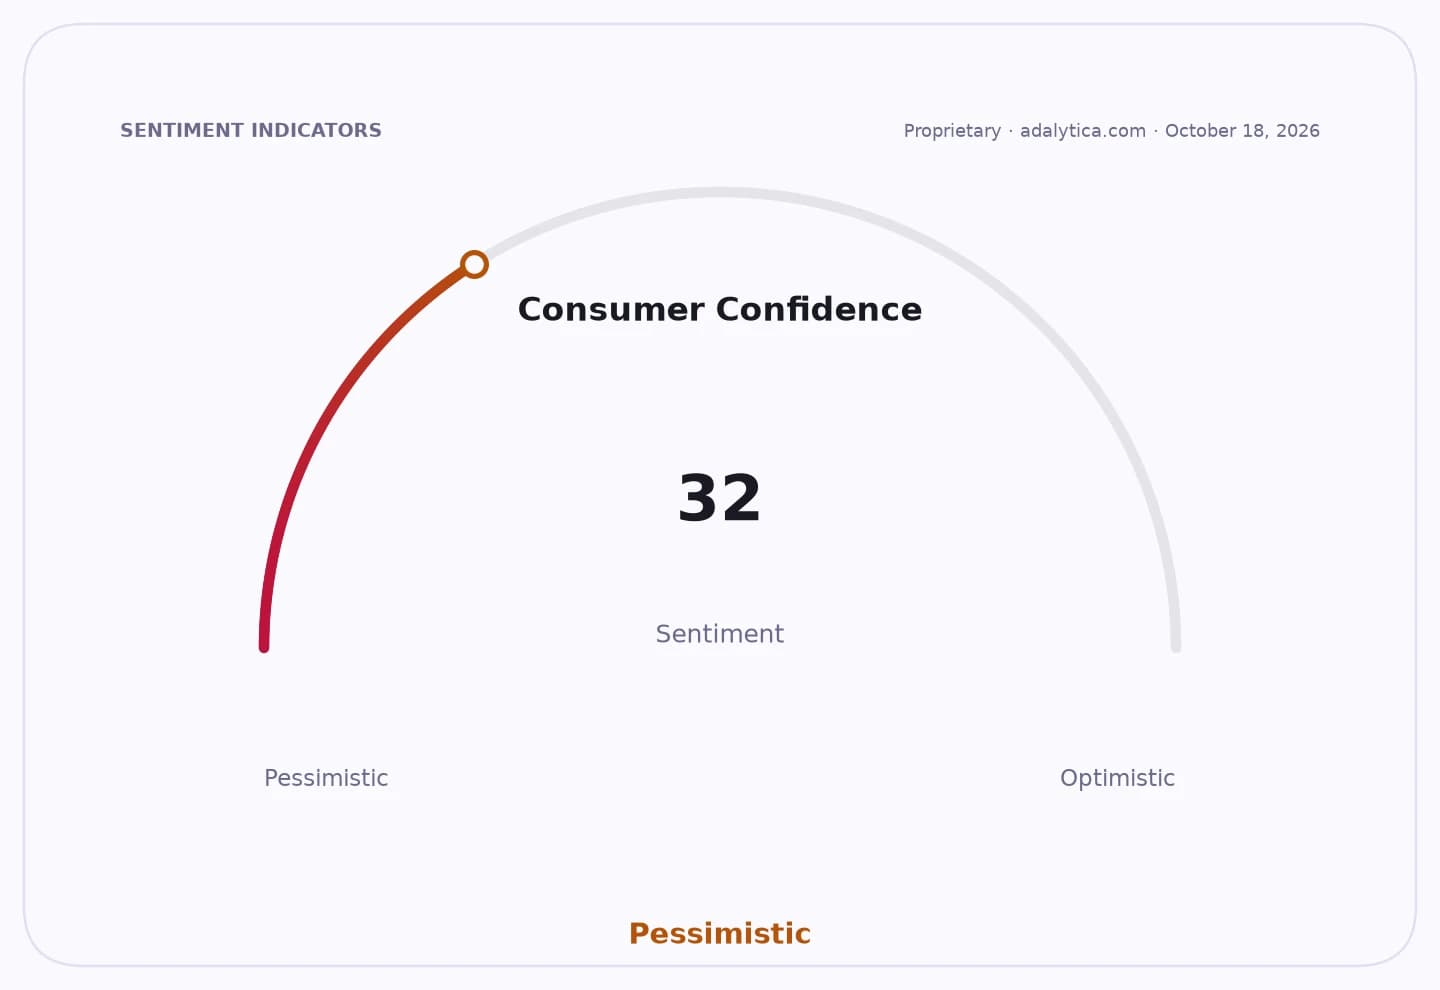
Sentiment Indicators
That is the thrust of remarks attributed to economist Ioniță, who rejected the idea that Romania can still compete mainly through low pay. The argument has gained force amid broader regional wage pressure and public frustration over minimum-pay levels that many workers say fail to cover living costs. In eastern parts of Europe, the gap between official wage statistics and day-to-day affordability has become a political issue, not just an economic one.
For investors, the message is two-sided. Higher pay can support consumption, helping retailers, lenders and domestic-demand plays, but it also raises the bar for employers that built business models on inexpensive labor. That is especially relevant in labor-intensive sectors such as manufacturing, outsourcing, logistics and services, where margin expansion has historically depended on wage arbitrage versus western Europe.
The market backdrop reinforces the shift. Emerging-market equities have been volatile, while U.S. labor-market signals remain relatively firm, keeping global wage competition in focus. At the same time, Adalytica’s job-market sentiment gauge shows strong optimism even as awareness of labor strain remains extremely low, underscoring the tension between headline employment resilience and worker anxiety over pay and costs.
In Romania’s case, the strategic consequence is clear: the old investment pitch based on cheap labor is becoming less credible. That puts pressure on policymakers to focus on productivity, vocational training and social dialogue over wage compression, while forcing companies to decide whether to absorb higher payrolls, pass them on to customers or automate faster.
For portfolio managers, the key question is which businesses can live with structurally higher labor costs and which ones cannot. The winners are likely to be firms with pricing power, high-value exports and automation capacity. The losers are companies still dependent on a low-wage advantage that is fading faster than the political narrative admits.
| Entity | Gains | Losses |
|---|---|---|
| Romanian workers | ▲Higher pay bargaining power | ▼Fewer low-wage jobs |
| Domestic consumers | ▲Stronger household spending | ▼Inflation pressure |
| Employers relying on cheap labor | ▲Productivity incentive | ▼Margin squeeze |
| High-value exporters / automators | ▲Better skills, less churn | ▼Higher payroll costs |