Romania’s savers are heading into another year where the choice between lei, euro, gold and government bonds will matter more for preserving purchasing power than for chasing returns.
Romania savers weigh lei, euro, gold and bonds
With the leu down 4.95% against the euro over the past year, inflation still running at 6.61% in September and the National Bank of Romania expected to keep its policy rate at 6.5% for several more quarters, the question is less about maximizing gain than about limiting erosion in real terms. That makes the trade-offs among local-currency deposits, foreign exchange, bullion and sovereign paper economically significant for households sitting on cash and for investors trying to position for a prolonged period of tight monetary policy.
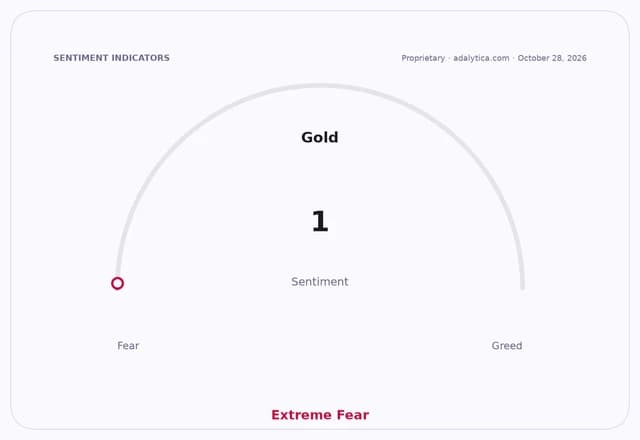
Sentiment IndicatorsⓘProprietary · adalytica.com · October 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The clearest recent winner was gold. Measured in lei, the metal gained about 10% over the last 12 months, outperforming both inflation and the currency move, according to XTB Romania consultant Claudiu Cazacu. The euro also offered a buffer, helped by the leu’s depreciation, and Cazacu said that on a one-year horizon the single-currency bet could remain the better defensive choice if conversion costs are low.
That matters because Romania’s inflation problem is not a one-off shock. The central bank is still fighting sticky price pressures tied to fuel, energy and food, while fiscal strains and external vulnerabilities keep the leu under pressure. In that setting, the nominal return on an asset is only half the story; the currency in which that return is earned is increasingly decisive.
Gold — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
Local-currency government bonds are the most straightforward nominal hedge on offer. The October 2027 lei-denominated sovereign notes were yielding around 7.2% recently, above the 6.61% annual inflation rate for September. But the spread does not guarantee a real gain. Inflation can stay elevated through the bond’s life, and the investor also has to factor in taxes, bid-offer spreads and the risk of selling before maturity.
Euro-denominated sovereign paper offered roughly 3% over the same horizon, a much lower coupon but one that comes with the possibility of further leu weakness. For households with future liabilities in euros — mortgage repayments, tuition or savings for spending abroad — the lower yield may still be preferable if the currency hedge matters more than the nominal coupon.
Gold remains the most ambiguous option. It has delivered the strongest past-year return in lei and still benefits from a broader strategic shift by central banks, which have bought roughly 4,030 tonnes net over the past four years, far above the previous decade’s annual average of about 500 tonnes. A 2026 World Gold Council survey found 83% of central banks expected gold’s share of reserves to rise over the next five years, and 45% planned to add holdings in the next 12 months. But short-term positioning looks stretched: Adalytica’s Gold Fear & Greed Index showed extreme fear, while the GLD ETF traded below its 200-day moving average and its RSI remained weak, suggesting investors have become more cautious after a strong run.
The bond market tells a similar story of caution rather than conviction. U.S. Treasury price signals were mixed, and the 10-year yield hovered near 5%, while the 10-year/2-year spread remained slightly positive. That backdrop matters for Romanian assets because global yields help set the tone for carry trades and capital flows. If developed-market rates stay high, the leu’s room to appreciate looks limited; if they ease, euro and gold holdings could gain more appeal as hedges against domestic inflation and currency slippage.
For Romanian savers, the most rational answer depends on the purpose of the money. Lei government bonds remain the most predictable tool for those who want income and can hold to maturity. Euro remains the cleaner hedge for future euro spending. Gold offers the strongest long-term insurance against inflation and policy surprise, but with higher volatility and no fixed return. And if the leu weakens further, as many analysts expect, the ranking could shift again — not because one asset is universally best, but because Romania’s inflation, fiscal risk and currency pressures are forcing households to think in portfolios rather than single bets.
| Entity | Gains | Losses |
|---|---|---|
| Gold holders | ▲Best recent lei return | ▼High volatility |
| Euro savers | ▲Currency protection | ▼Lower yield |
| Lei bond investors | ▲7.2% nominal income | ▼Inflation erosion risk |
| Cash in lei | ▲Liquidity | ▼Purchasing-power loss |