Siemens Energy shares are being underpinned by JPMorgan’s view that the surge in spending on AI data centers, semiconductors and broader power infrastructure still has room to run.
Siemens Energy gains on JPMorgan AI power outlook
The US bank reiterated its “Overweight” rating on Siemens Energy, saying its semiannual investment survey reinforced a constructive outlook for the industrial hardware and AI infrastructure complex. For investors, the call matters because Siemens Energy sits directly in one of the market’s clearest capital-spending themes: the race to build the electrical equipment, grid capacity and backup systems needed to power artificial intelligence.
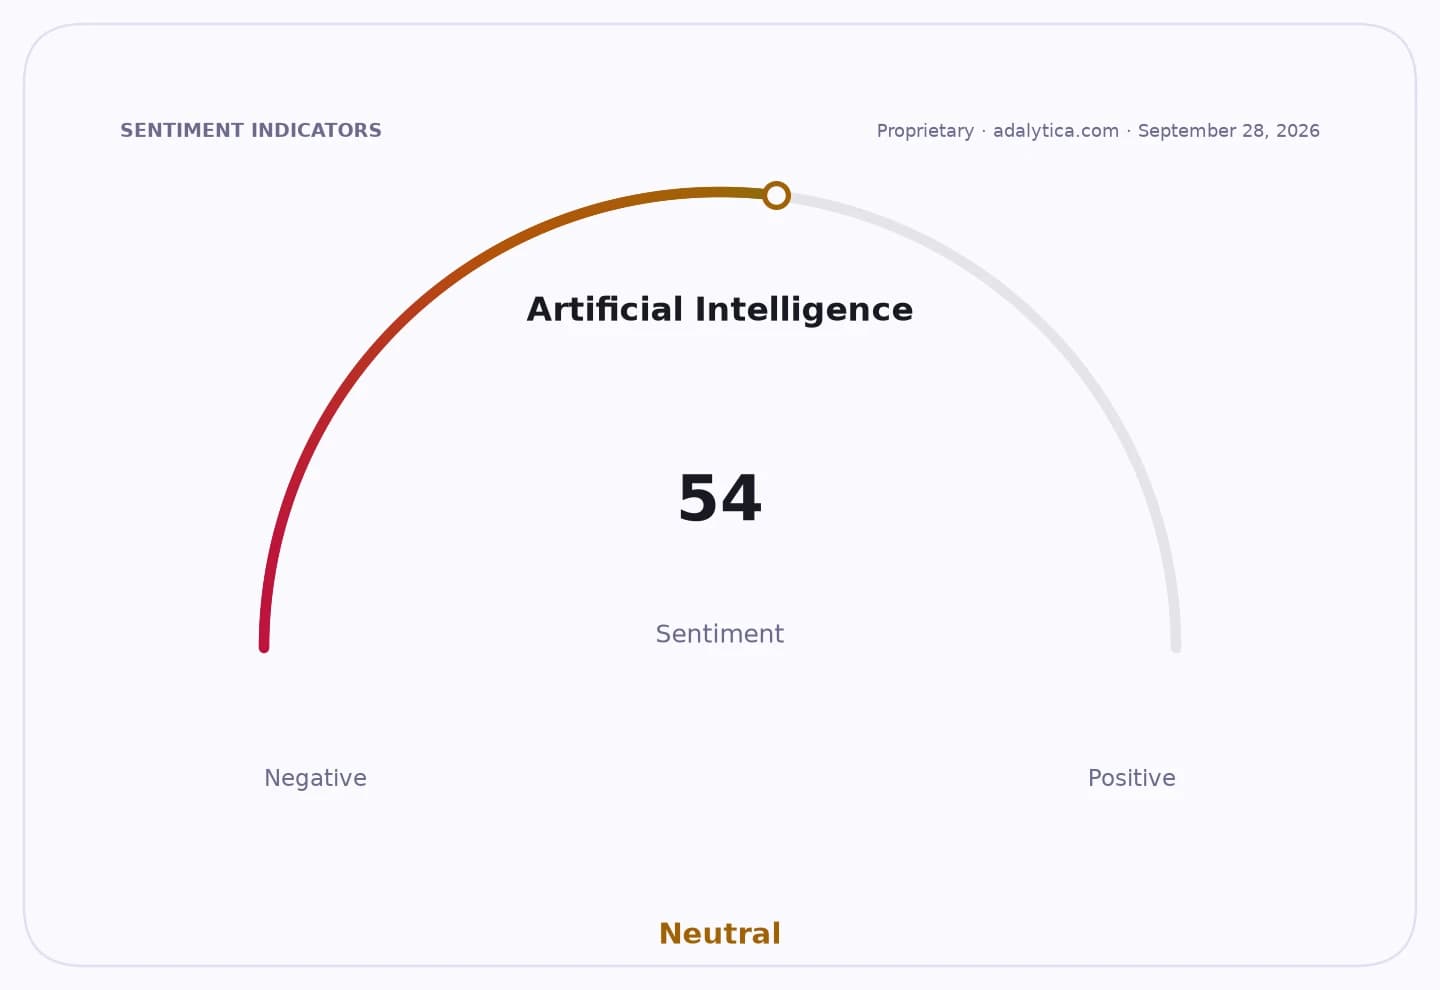
JPMorgan’s Phil Buller said the survey supported strong demand prospects not only for AI data centers and semiconductors, but also for a wider group of capital-goods names including Siemens, Legrand, Nexans, Atlas Copco, IMI and Oxford Instruments, as well as mining equipment suppliers. That matters economically because the AI buildout is increasingly becoming a physical infrastructure cycle, not just a software story. It is pulling through orders for transformers, switchgear, cables, turbines and other grid-linked equipment, keeping industrial pricing and order books firmer than many investors expected at the start of the year.
The market is already reflecting that optimism. Siemens Energy shares were up 0.3% at 144.94 euros in Xetra trade at the time of the note, and the stock has gained 20.9% so far in 2026. Even after that move, JPMorgan’s stance suggests it sees the rally as supported by fundamentals rather than just momentum. The shares have also been trading with relatively firm technical support, with recent price action holding above the 50-day moving average and the 200-day average, a sign that the market still views the stock as structurally stronger than it was earlier in the year.
For Siemens Energy, the bullish case rests on the idea that utilities, hyperscalers and industrial customers are still only in the early to middle stages of a multi-year buildout. That would keep demand high for grid equipment and power systems even if broader manufacturing growth remains uneven. The bear case is that expectations could become crowded if AI-related capex slows, project timing slips or margins are pressured by execution risk and supply-chain constraints. But JPMorgan’s call implies the bank sees the demand cycle as broad enough to offset those risks for now.
For investors, the message is that Siemens Energy remains a leveraged way to express the AI infrastructure trade without owning a pure technology name. The stock’s performance will likely continue to depend on whether order growth translates into sustained earnings upgrades, and whether the wider power-equipment complex keeps benefiting from data center spending, electrification and grid expansion. The next test will be whether that capital-spending momentum shows up in upcoming results and guidance across the sector.
| Entity | Gains | Losses |
|---|---|---|
| Siemens Energy | ▲Higher valuation support | ▼Short sellers |
| JPMorgan’s bullish thesis | ▲Confirmation from survey data | ▼Bearish investors |
| AI data center builders | ▲More equipment supply | ▼Customers facing higher costs |
| Grid and industrial suppliers | ▲Stronger order demand | ▼Cyclical slowdown bets |