Southeast Asia is pressing ahead with more than 100 gigawatts of gas-fired power capacity and 70 million tons a year of LNG import terminals even as Middle East conflict has sharpened supply and price risks, underscoring a costly bet on imported fuel for power security.
Southeast Asia Adds LNG Power Despite Supply Risks
That build-out, worth about $160 billion, matters because it locks in demand for LNG just as global gas markets remain vulnerable to disruption in the Strait of Hormuz and other chokepoints. For governments across emerging Asia, gas is still being used as a bridge fuel to replace coal and support growing electricity demand, but the strategy leaves utilities and consumers exposed to volatile seaborne prices.
Global Energy Monitor said the expansion assumes LNG will remain available and competitive and that domestic supplies can cover shortfalls when cargoes are interrupted. The think tank warned that continuing to expand import infrastructure risks deepening exposure to the same shocks the war in the Middle East has highlighted, especially in price-sensitive markets.
The investment pipeline has not been immune to the risks already. More than 35 GW of gas power capacity was shelved or cancelled in 2025, and 65 mtpa of LNG import capacity had been shelved or cancelled by September last year, suggesting some developers and policymakers are already pulling back from the most exposed projects.
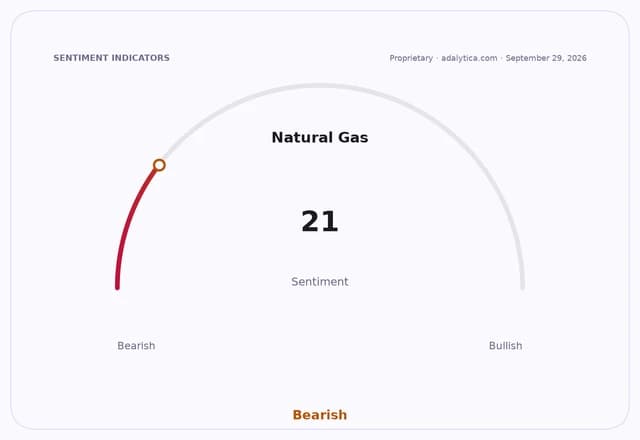
Thailand and Vietnam are rethinking their LNG strategies, while the Philippines has shelved or cancelled 11.2 GW of gas power capacity from the second half of 2025 through the first half of 2026, even though 13.8 GW remains in development, according to GEM. That split shows the region is still adding gas, but with greater caution as countries weigh energy security against the risk of imported fuel dependence.
The stakes are not only regional. Europe’s gas market has already shown how quickly shipping disruptions and geopolitical tensions can push prices higher, and Asian buyers face the same freight and supply pressures if conflict widens or LNG cargoes tighten further. For investors, that keeps LNG producers, shipowners and developers in focus while raising execution and demand risk for power companies and terminal builders tied to the Southeast Asia pipeline.
With LNG prices, Middle East tensions and project cancellations moving in opposite directions, the next catalyst is likely to come from how quickly Southeast Asian governments translate energy-security concerns into contract decisions, project deferrals or alternatives such as domestic gas and renewables.
| Entity | Gains | Losses |
|---|---|---|
| LNG exporters | ▲More long-term demand | ▼Higher policy scrutiny |
| Southeast Asian utilities | ▲New power capacity | ▼Exposure to price spikes |
| Domestic gas and renewables | ▲Potential policy support | ▼Slower fuel-switching |
| LNG terminal developers | ▲$160 billion pipeline | ▼Cancellation and delay risk |