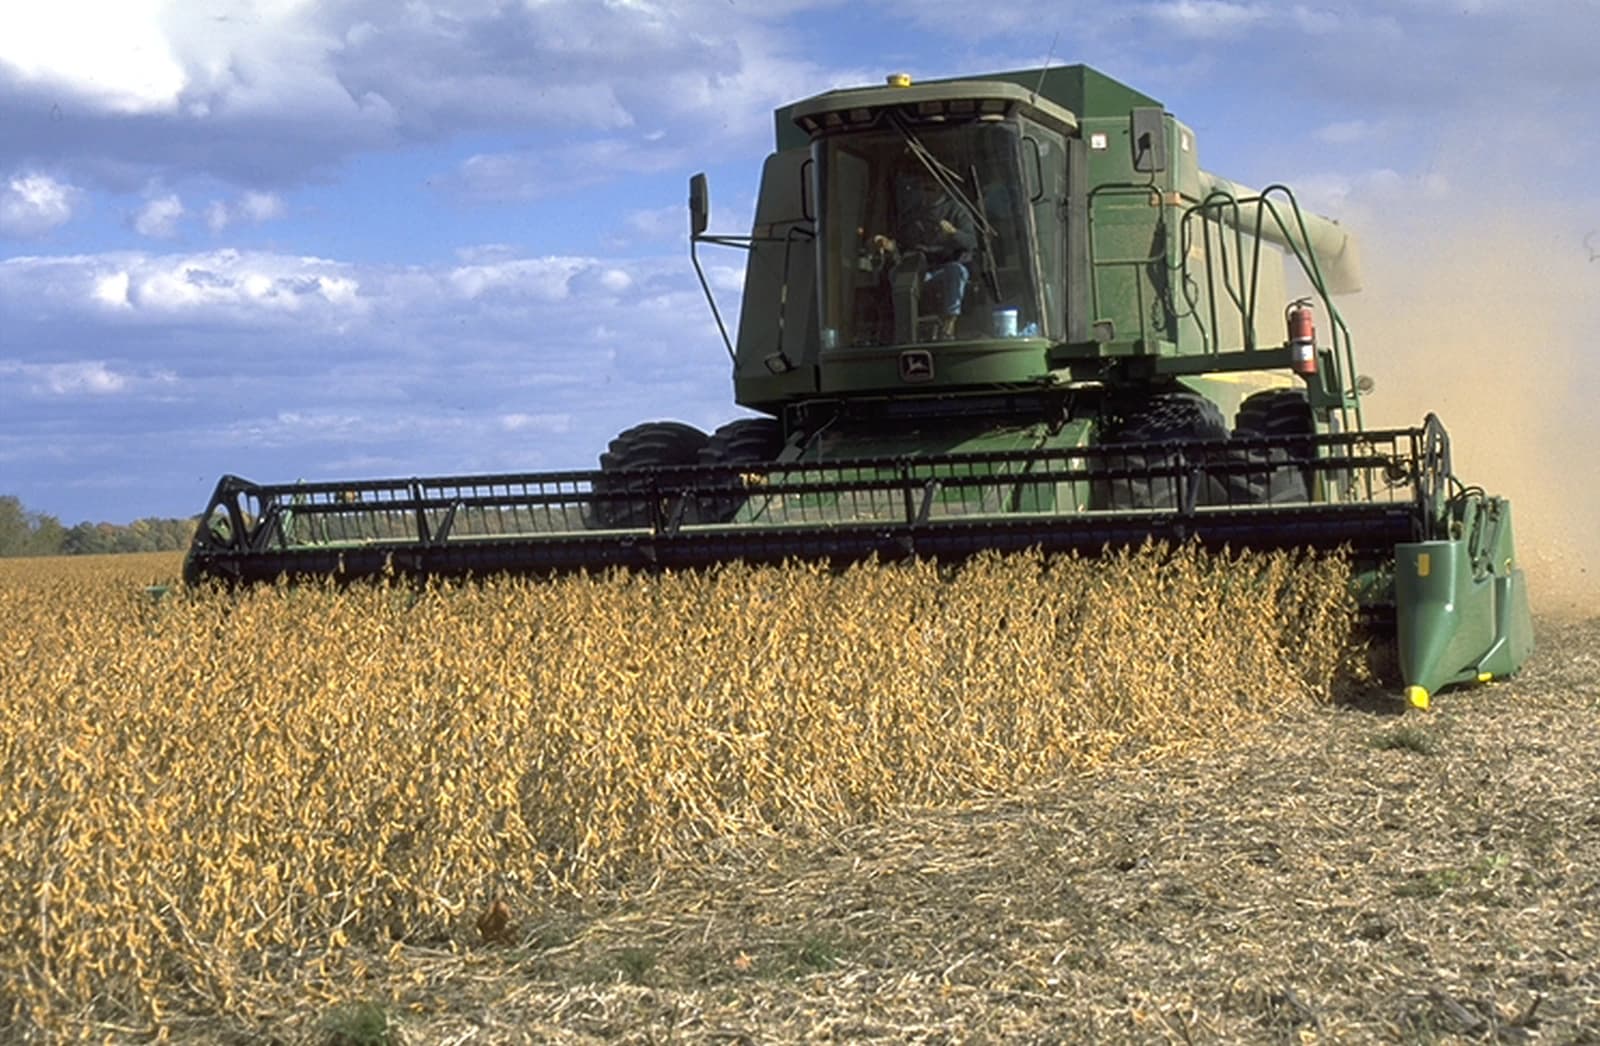
Chicago Board of Trade soybean futures fell to an 11-week low as a slump in crude oil dragged down soybean oil, undercutting one of the crop’s key demand engines and deepening bearish pressure across the oilseed complex.
Soybean Futures Fall as Crude Weakness Hits Oil
That matters because soybeans are not just a food and feed market; they are also an energy-linked trade. Soybean oil is a major feedstock for renewable diesel and biodiesel, so when crude weakens, the economics of alternative fuels deteriorate and the price support for soybeans erodes with it. In a market already wrestling with ample supply, weaker energy prices can quickly turn a routine pullback into a liquidation wave.
Sentiment Indicators
The move comes alongside a sharp retreat in U.S. crude benchmarks. West Texas Intermediate was forecast to slip to about $98.20 a barrel on Nov. 4 from $99.64 a day earlier, extending a decline from recent highs, while the USO oil ETF has fallen to $148.41 from $152.96 in mid-September. That drop has coincided with pressure across agricultural commodities, including the broader DBA basket, which has eased to $26.11 from $29.32 in September. For soybeans, the pain is more acute: SOYB closed at $25.32 on Nov. 6, down sharply from $28.14 in September and below both its 50-day and 200-day moving averages.
Investors should read this as more than a crop-specific move. It is a cross-asset signal that the market is repricing inflation-sensitive commodities lower, with energy’s weakness spilling into agriculture through biodiesel economics, freight costs and speculative positioning. The Chicago market is also flashing a technically damaged tape: SOYB’s RSI has collapsed to 13.9, a deeply oversold reading, while its MACD remains negative. That does not guarantee a bounce, but it does show how aggressively traders are cutting exposure.
The macro backdrop reinforces the bearish setup. Credit spreads have eased, with the U.S. high-yield option-adjusted spread around 3.48 percentage points on Nov. 5, suggesting the market is not yet pricing a broad credit shock. At the same time, the 10-year Treasury yield near 4.84% keeps financing conditions restrictive enough to cap risk appetite without forcing a flight into commodities. In that environment, soybeans need a strong fundamental catalyst — tighter supply, stronger Chinese buying or a rebound in veg-oil margins — to arrest the slide.
Our view is that the market is underestimating how tightly soybeans are tied to the energy cycle. If crude keeps softening, soybean oil can remain the weak link in the agricultural complex even if crop fundamentals stabilize. For investors, that makes soybeans vulnerable in the near term and suggests a more selective approach: stay cautious on broad grain exposure, but watch for a potential tradable bottom if energy finds a floor and technical selling exhausts itself.
| Entity | Gains | Losses |
|---|---|---|
| Crude oil bears | ▲Lower energy prices | ▼Soybean bulls |
| Soybean processors | ▲Cheaper input costs | ▼Farmers/long-only grain funds |
| Renewable diesel producers | ▲Potential margin relief if feedstock adjusts | ▼Soybean oil sellers |
| Broad commodity holders | ▲None | ▼Inflation-hedge allocations |