Selling an apartment and using part of the proceeds to pay off the remaining mortgage does not, by itself, forfeit Spain’s capital gains tax exemption on reinvestment in a primary residence — a nuance that can materially change after-tax returns for homeowners in a still-expensive housing market.
Spain home sale mortgage payoff tax exemption
The key point for investors and property owners is economic, not procedural: the amount used to cancel the outstanding loan is deducted from the reinvestment base, rather than counted twice. In the example cited by Spanish lawyer Alba Sánchez-Heredero, a home sold for 400,000 euros with 100,000 euros of mortgage debt left outstanding would require 300,000 euros of reinvestment to qualify for the full exemption. That makes the rule far more practical for households upgrading or downsizing, because it preserves liquidity while still protecting gains from tax.
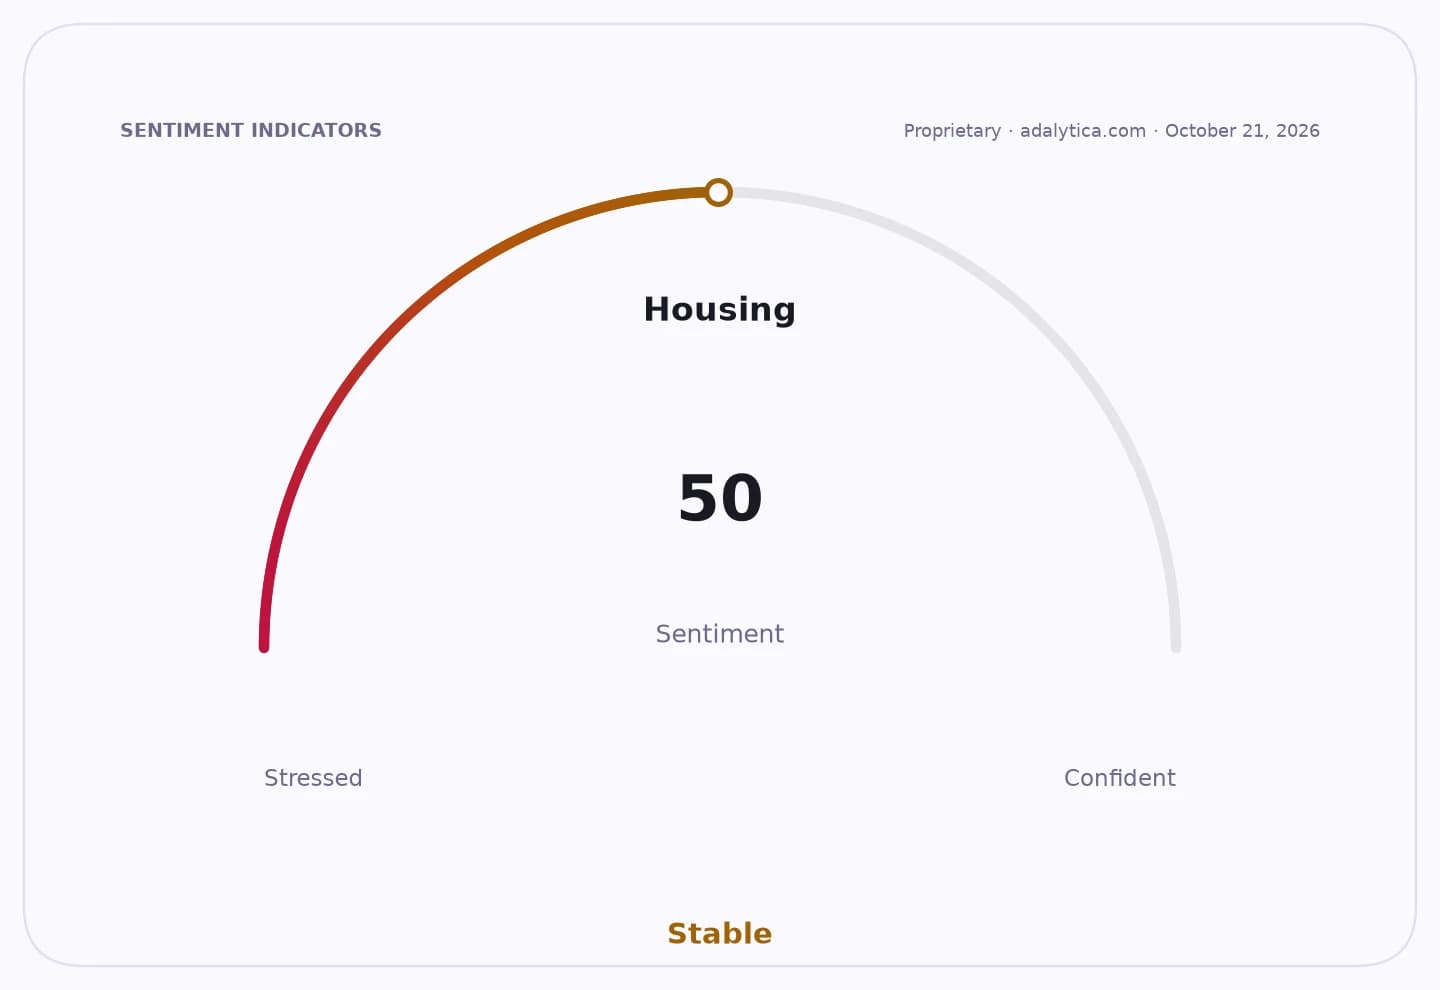
That matters in a market where housing affordability remains stretched and financing costs are still elevated. Spain’s home price index has climbed sharply over time and is still running above 330 on the latest data, underscoring how much equity many owners have built up. At the same time, U.S. housing starts are soft, with the latest reading at 1.275 million annualized, a reminder that higher rates continue to pressure residential activity across developed markets. Spain’s tax treatment therefore becomes part of the transaction calculus: it influences whether sellers move, how much capital they roll forward, and how much demand feeds into the next purchase.
The broader economic significance is that the rule supports housing turnover. If sellers feared that using sale proceeds to retire debt would trigger a tax penalty, they would be more likely to stay put, reducing supply in an already constrained market. By clarifying that only the net amount after mortgage payoff needs to be reinvested, the tax code encourages mobility and preserves the after-tax value of home equity. That is especially relevant when 10-year sovereign yields remain above 5%, keeping borrowing costs high and making financing discipline a bigger part of household decision-making.
For investors, the opportunity is in the second-order effects. A clearer, seller-friendly reinvestment rule tends to support transaction volumes, which benefits lenders, brokers, notaries, movers, and home improvement firms tied to turnover. It also reduces the chance of a forced sale discount, because owners can settle the mortgage out of proceeds without losing the exemption. In a market where equity extraction and balance-sheet management matter, that is a quiet but meaningful tailwind.
The takeaway is straightforward: the mortgage payoff is not the taxable event; the reinvestment test is. For homeowners planning a sale, the most attractive move is to model the exemption on the net amount after debt repayment, then reinvest strategically within the two-year window. For investors, the trade is in the ecosystem that profits when property owners move more freely.
| Entity | Gains | Losses |
|---|---|---|
| Home sellers | ▲Preserve tax exemption | ▼Risk tax only if under-reinvested |
| Mortgage holders | ▲Can retire debt tax-efficiently | ▼Lose lock-in effect |
| Real estate brokers/lenders | ▲More transaction flow | ▼Fewer stalled sales |
| Tax authorities | ▲Clearer compliance rules | ▼Less friction-based revenue |