Rising demand for sugar substitutes is putting stevia back in focus as a commercially attractive crop and ingredient, with the natural sweetener’s near-zero-calorie profile and extreme sweetness making it a lower-cost reformulation tool for food and beverage makers.
Stevia demand rises as sugar reformulation grows
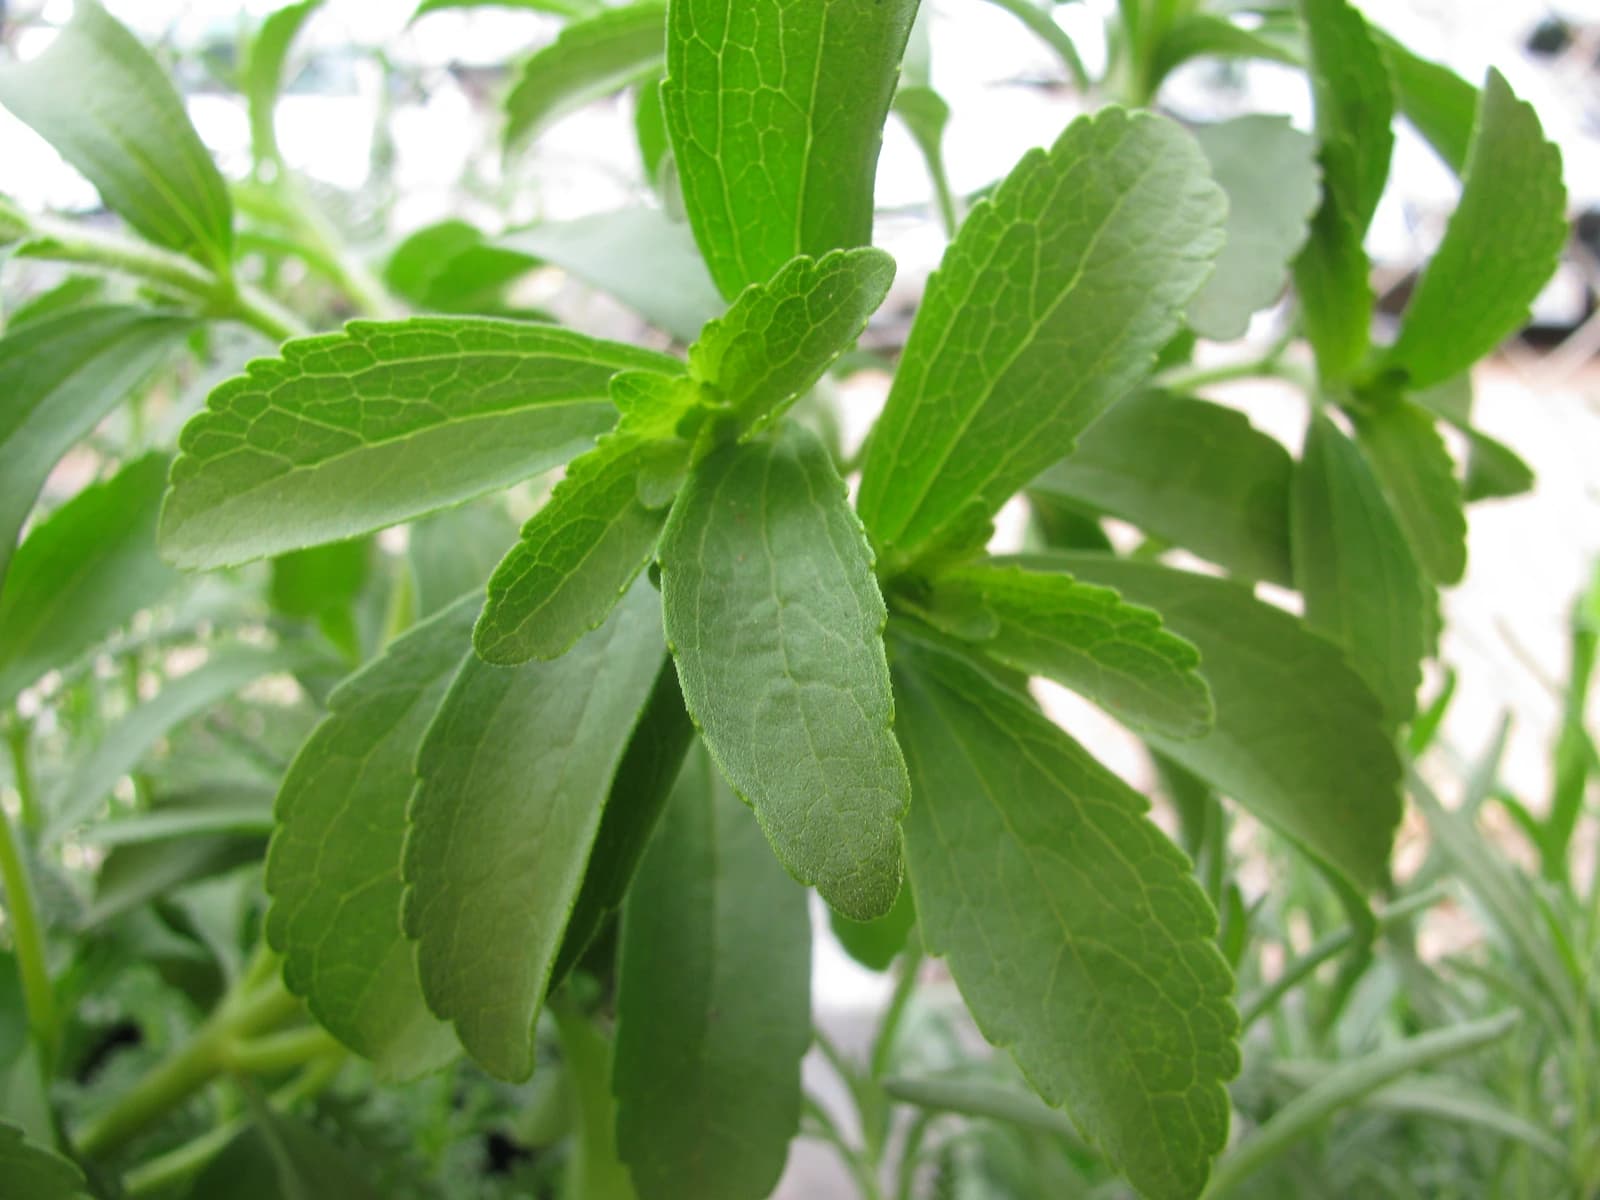
The economic case is straightforward: consumers are cutting sugar, regulators keep pressuring manufacturers to reduce calorie and added-sugar content, and brands need ingredients that preserve taste without lifting nutrition labels. Stevia fits that brief better than many alternatives because extracts can be 200 to 300 times sweeter than sugar while carrying little to no calories, giving manufacturers a high-intensity sweetening option in tiny volumes.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 16, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
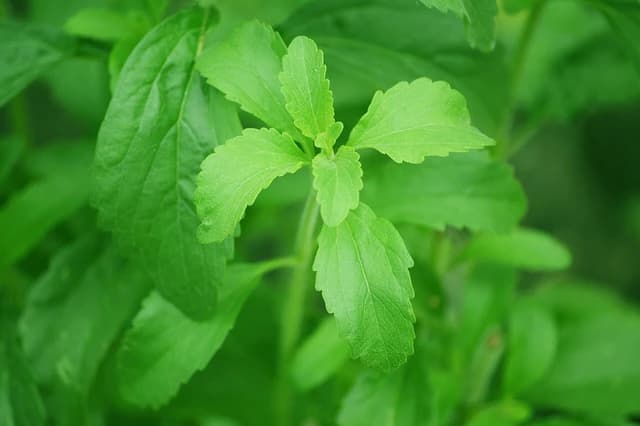
That matters for farmers as well as packaged-food companies. The crop is perennial, can be harvested multiple times a year under the right conditions, and can remain productive for three to five years, which lowers replanting frequency compared with many annual crops. For growers, the appeal is the possibility of recurring cash flow from the same planting base. For processors, it creates a feedstock with potential supply stability if agronomy and buyer contracts are well managed.
The business model, however, is more fragile than the marketing pitch suggests. The Hindi-language source cited potential net earnings of as much as 100,000 rupees to 125,000 rupees per acre a year, but that depends heavily on yields, drying quality, labor, irrigation and local offtake. In other words, the economics are only as good as the buyer network. Farmers are being told to verify demand nearby before scaling, a warning that underscores how thin the market can be outside established supply chains.
For investors, the story is not just about agriculture. It is about a structural shift in sweeteners and the companies positioned to capture it. Demand for natural, low-calorie ingredients can support suppliers of stevia-derived inputs, flavor systems and reformulation services, while also pressuring sugar-intensive categories to adapt. That shift can be positive for ingredient specialists and food companies with strong product-development pipelines, but it raises execution risk for growers and smaller processors that lack long-term contracts.
Shares of some sweetener-linked names have already reflected that volatility. SunOpta, which has exposure to food and beverage ingredients, closed at $10.04 on Oct. 16, up sharply from $6.22 on July 16, with a 50-day moving average of $7.54 and a 200-day average of $7.04. The stock’s RSI of 77.1 and its position near the upper end of its Bollinger Band range suggest the move has run hot in technical terms. Conagra Brands, by contrast, remains more subdued, closing at $14.47 on Oct. 16 versus a 200-day average of $15.09, indicating investors have yet to assign the same growth premium to a broader packaged-food name.
The broader market backdrop also looks mixed. Adalytica’s Consumer Spending Sentiment gauge is at 4.0, or “Extreme Fear,” which implies consumers are cautious even as they seek value and health-conscious swaps. That combination can favor low-calorie ingredients that help manufacturers defend volume without resorting to heavy sugar content, but it can also limit pricing power if buyers resist premium formulations.
The bull case for stevia is that it is one of the few sweetening ingredients that aligns with health trends, reformulation mandates and cost-efficient intensification of sweetness. The bear case is that supply remains fragmented, contract visibility is limited and economics can swing quickly with drying, quality and local buyer demand. For investors, the key question is whether stevia becomes a durable reformulation platform or stays a niche crop with sporadic profitability.
What to watch next is whether food makers increase procurement of stevia extracts, whether farmers can lock in recurring buyers, and whether listed names with sweetener exposure can turn consumer preference into margin expansion rather than just another short-lived trade.
| Entity | Gains | Losses |
|---|---|---|
| Stevia growers | ▲recurring harvests | ▼buyer concentration risk |
| Food & beverage makers | ▲sugar reduction tool | ▼reformulation costs |
| Ingredient suppliers | ▲higher demand | ▼raw-material volatility |
| Sugar producers | ▲— | ▼substitution pressure |