Student loan balances fell by $10 billion in the second quarter, a rare decline in a market that has swollen for years and a sign that the Biden administration’s forgiveness efforts are starting to show up in household debt data.
Student loan balances fell $10 billion in Q2
The drop matters because student debt has been one of the most stubborn liabilities on U.S. consumers’ balance sheets, weighing on borrowing power, homebuying and monthly cash flow. Any broad reduction in balances can free up spending, ease delinquency risk and improve the financial profiles of millions of borrowers.
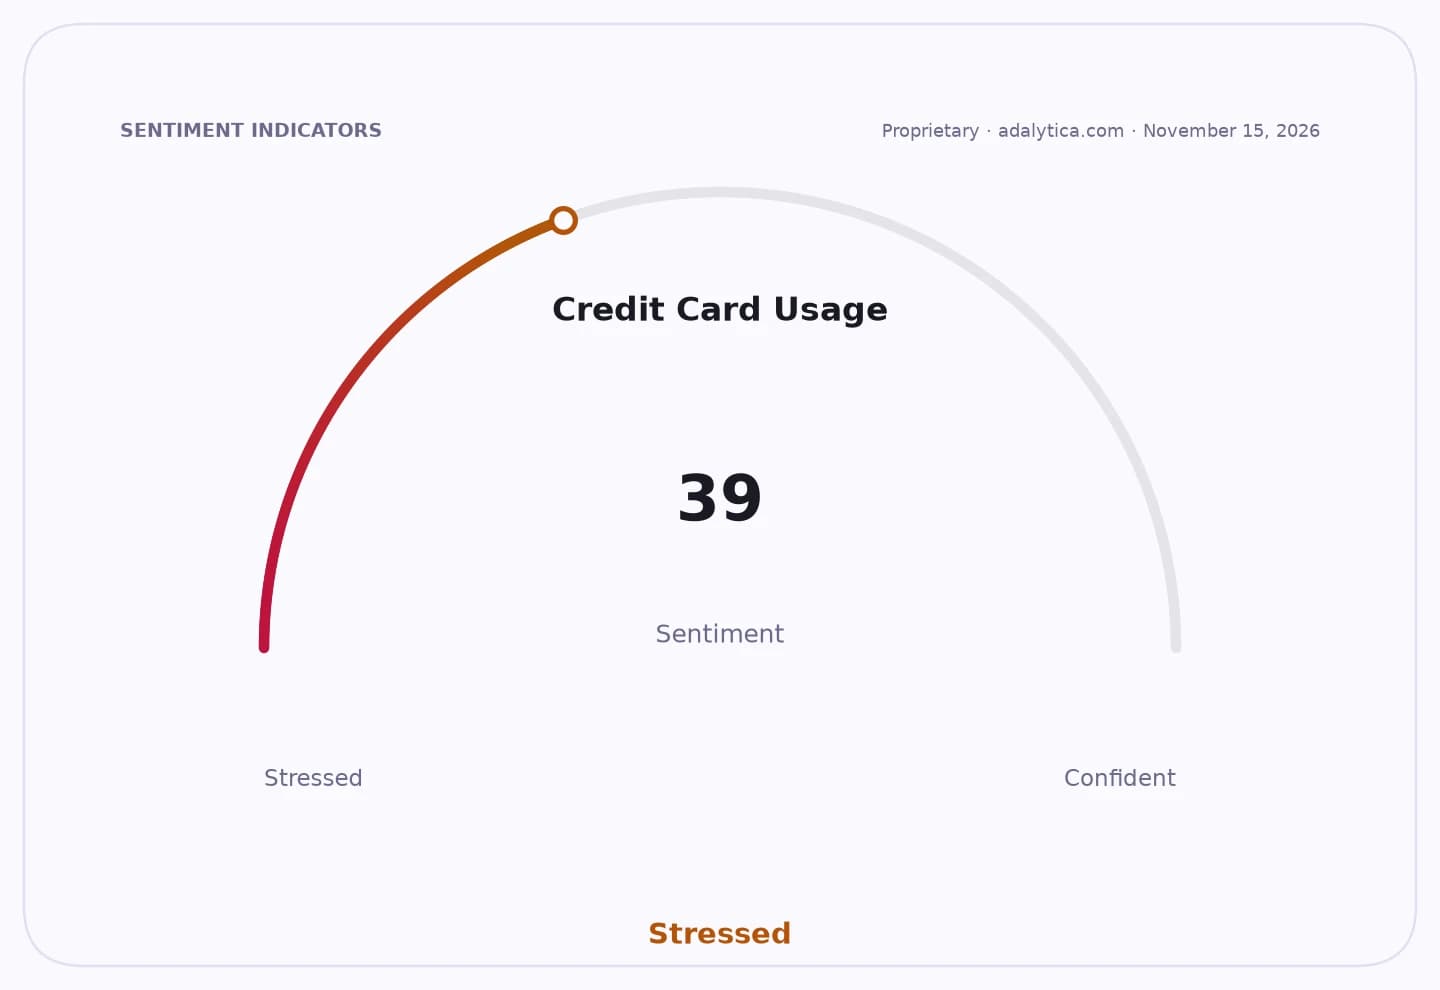
Sentiment Indicators
The change also has direct implications for lenders tied to the education finance market. SoFi Technologies, Navient and Sallie Mae all have exposure to student lending and refinancing, making policy-driven changes to repayment and forgiveness a key driver of loan demand, credit performance and earnings.
The New York Fed’s debt report showed that student loan balances moved lower even as mortgages, credit cards and auto loans rose, underscoring how unusually targeted the relief has been. The policy backdrop is likely to remain in focus as borrowers, servicers and investors adjust to the next phase of federal repayment and forgiveness changes.
For investors, the near-term question is whether the relief trend supports consumer credit quality enough to offset weaker refinancing volumes and potential pressure on lender margins. The next read on repayment behavior, delinquencies and loan originations will show whether the debt decline is a one-time policy effect or the start of a longer reset in student finance.
| Entity | Gains | Losses |
|---|---|---|
| Borrowers | ▲Lower balances; more cash flow | ▼Less debt relief uncertainty |
| SoFi, Navient, Sallie Mae | ▲Potential credit improvement | ▼Refinancing demand pressure |
| U.S. consumers | ▲Reduced debt burden | ▼Less room for selective spending |
| Private student lenders | ▲Better repayment prospects | ▼Smaller loan growth pool |