High-income savers can often come out ahead by moving surplus cash from a bank term deposit into superannuation, because the tax treatment can matter more than the headline interest rate.
Super vs term deposits after tax for savers
That is the central trade-off for anyone weighing where to park money after tax: term deposits offer certainty and liquidity, but super can turn the same dollars into a more efficient long-term vehicle if the marginal tax rate on earnings outside super is high enough.
Sentiment Indicators
The argument becomes sharper when bond markets are in focus. US Treasury bond prices have been volatile, with the iShares 20+ Year Treasury Bond ETF, TLT, closing at $81.84 on Oct. 30 after recovering from a low of $79.46 on Oct. 19. The fund’s 50-day moving average sits at $80.27 and its 200-day average at $83.23, while RSI readings above 76 and a positive MACD point to a strong short-term rebound that may not yet be fully confirmed.
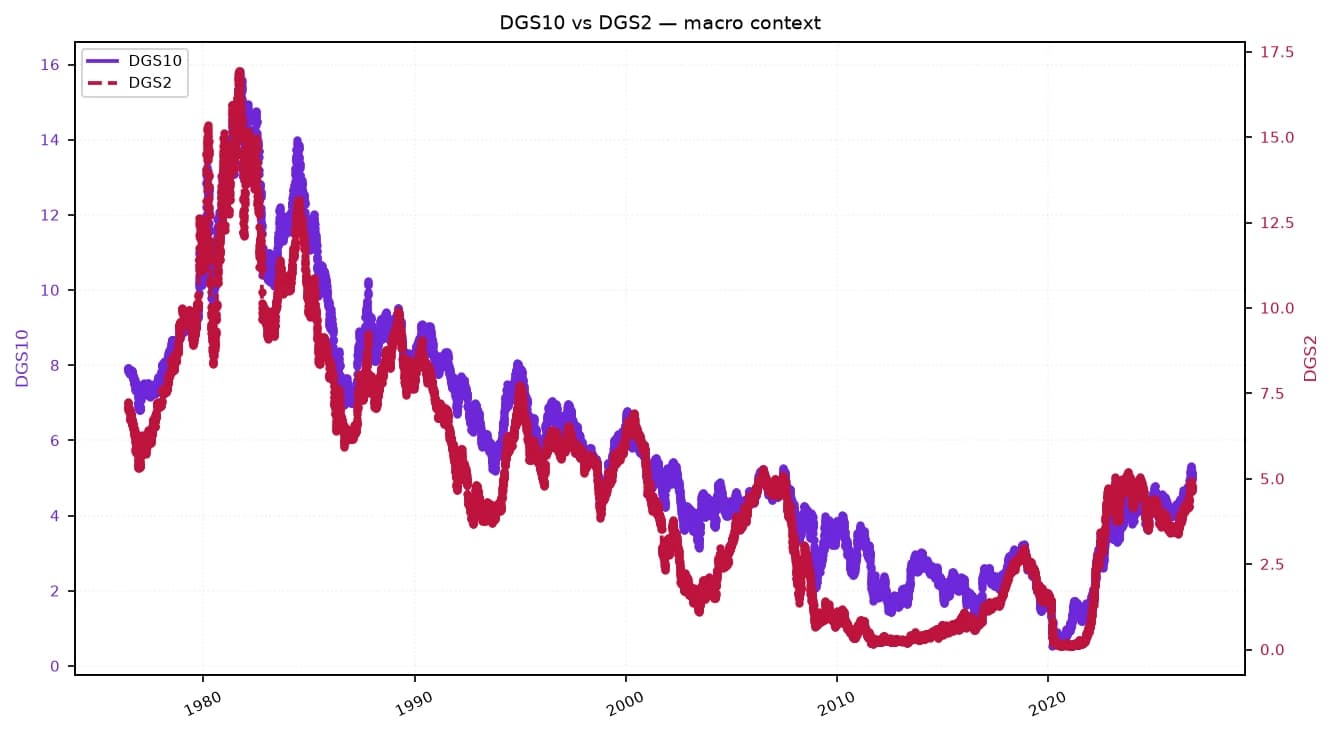
That matters because fixed-income returns feed directly into the sort of cash and conservative-income decisions savers make. When bond yields move, bank deposit rates and term-deposit pricing usually follow, but the after-tax return still depends on where the money sits. For higher-rate taxpayers, super’s concessional tax framework can lift the net outcome even if the pre-tax yield is similar.
Adalytica’s US Treasury bonds trade signals show extreme greed in the bond trade, while the US dollar snapshot shows rising awareness and neutral sentiment. For investors, that combination suggests markets are still heavily focused on rate expectations and the income trade, both of which can influence how attractive defensive cash allocations look versus retirement savings structures.
The practical implication is simple: savers should compare the after-tax return on a bank deposit with the concessional tax rate inside super, then weigh that against access to funds and contribution limits. The move is most compelling for people on high marginal tax rates who do not need immediate access to the cash.
The next catalyst is the path for rates and inflation, which will determine term-deposit pricing, bond yields and the relative appeal of locking money away in super versus keeping it liquid in the bank.
| Entity | Gains | Losses |
|---|---|---|
| High marginal-rate savers | ▲Higher after-tax returns in super | ▼Some liquidity and flexibility |
| Banks and term-deposit savers | ▲Stable deposit funding | ▼Cash outflows to super |
| Super funds | ▲More inflows and assets under management | ▼Competing bank products |
| Conservative income investors | ▲Tax-efficient compounding | ▼Short-term access to cash |