Thailand’s central bank is trying to frame the next phase of digital finance around two priorities that matter most to markets and policymakers: extracting productivity gains from artificial intelligence while hardening the payment system against fast-moving fraud.
Thailand Central Bank Pushes AI and Payment Security
Governor Vitai Ratanakorn used a speech at the IMF-World Bank annual meetings to argue that central banks can no longer treat innovation and stability as separate goals, pointing to rising public debt, geopolitical strain and deeper dependence on interconnected technology as risks that demand cross-border coordination. The message is especially relevant for payments firms, banks and regulators because the same technologies that are making transactions faster are also lowering the cost of cybercrime, account takeover and cross-border fraud.
The central bank’s case study is PromptPay, Thailand’s real-time payment rail launched a decade ago. More than 83 million people are now registered, and transaction value reached 54 trillion baht in 2025, more than twice Thailand’s gross domestic product. That scale underscores how quickly digital rails can become core financial infrastructure, widening access for rural users and small merchants while also concentrating operational and security risk in a system that now touches most of the economy.
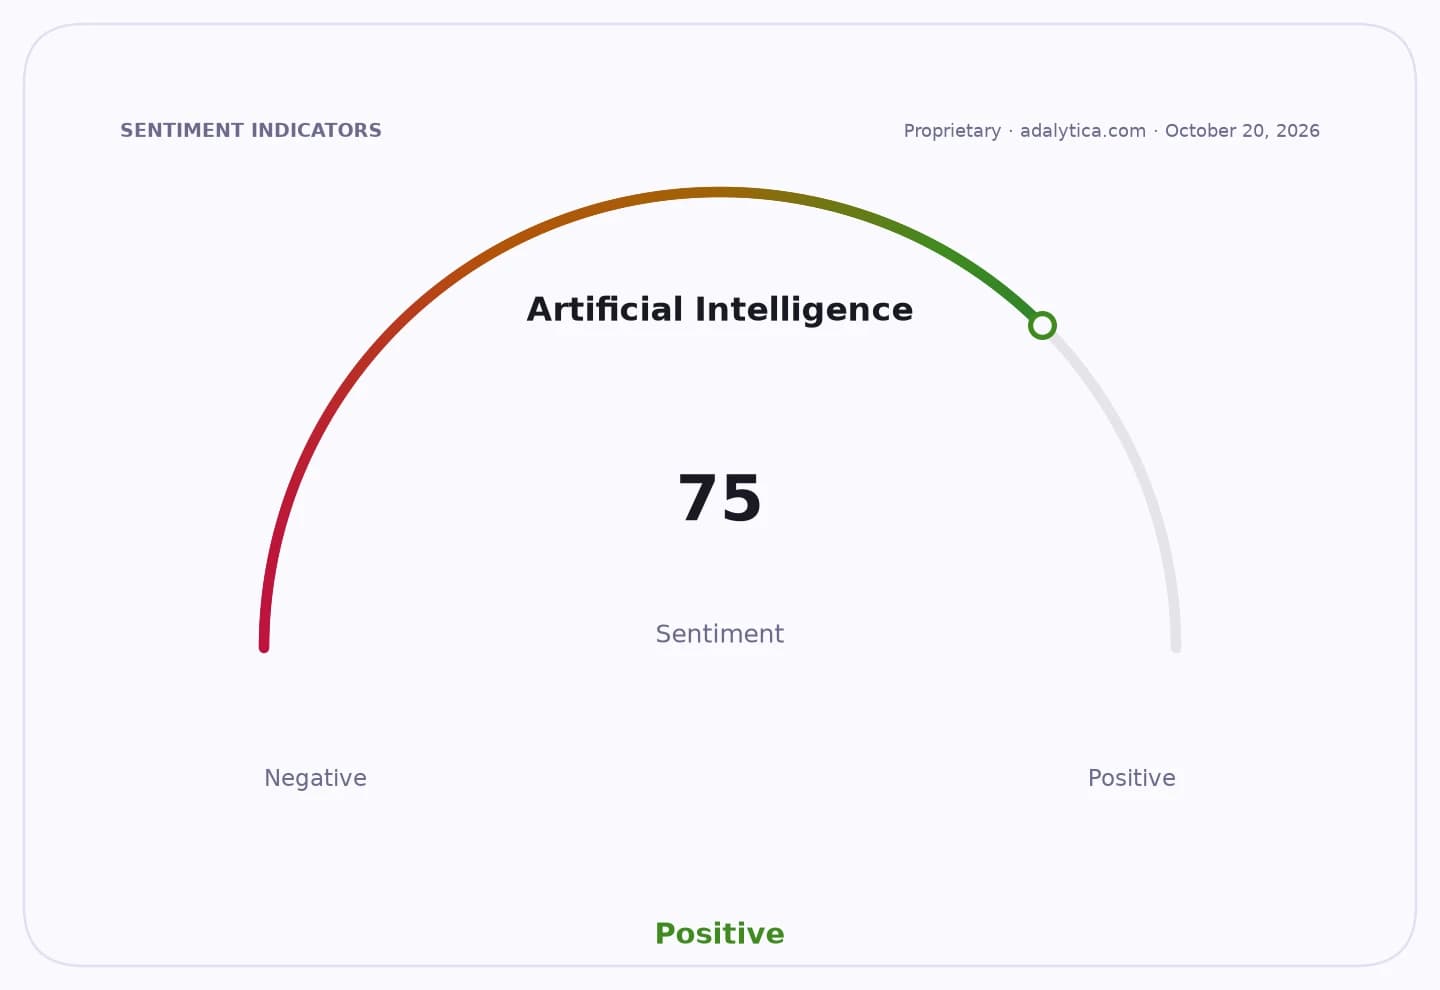
Vitai said AI could raise productivity, improve decision-making and help lenders assess small businesses and borrowers with limited credit histories, while tokenization could make cross-border payments more automated and efficient. For investors, that points to a larger opportunity set in digital finance, from payment processors and core banking software to identity verification and fraud prevention tools. It also supports the bull case for firms that can embed AI into underwriting, compliance and payment routing without sacrificing reliability.
The bear case is that adoption may outpace safeguards. Thailand’s central bank warned that fraud, cyberattacks and system outages can spread across multiple institutions and countries at once, and that AI and tokenization create new types of financial-system risk. That concern is increasingly shared by global banks and payments groups, which have disclosed in regulatory filings that fraud attempts, synthetic identities and cybersecurity threats remain persistent operating hazards.
To contain those risks, the Bank of Thailand is promoting a “Responsible Innovation Framework” built on sound technology, sound governance and sound economics, and is working with the IMF and World Bank on the Bangkok Blueprint for Force Resilient Financial Services. The blueprint lays out 12 considerations across five pillars — prevention, detection, response, information sharing and accountability — meant to help countries adapt a common template to local conditions.
For investors, the practical takeaway is that the next wave of digital finance will be judged not just by speed and adoption, but by resilience. That should favor payments and infrastructure providers that can prove lower fraud losses, stronger controls and clearer governance, while putting pressure on operators that scale usage faster than their security and compliance systems can keep up.
| Entity | Gains | Losses |
|---|---|---|
| Thai consumers and small merchants | ▲cheaper digital access | ▼higher fraud exposure |
| Banks and payments firms with strong controls | ▲trust and transaction growth | ▼remediation costs for weak systems |
| Fraudsters and cybercriminals | ▲none | ▼tougher enforcement and data sharing |
| AI-enabled lenders and payment processors | ▲efficiency and underwriting gains | ▼tighter oversight and compliance burden |