The most economically important development is the looming end of TOKİ’s 25% cash-settlement discount, which could accelerate a wave of early repayments and title transfers for roughly 228,000 homeowners and business buyers before the Oct. 19 deadline.
TOKİ cash-settlement discount ends Oct. 19
For households carrying TOKİ debt, the campaign is not just an administrative deadline. It offers a material reduction in the cost of ownership at a time when mortgage affordability and household balance-sheet stress remain sensitive across property markets. Buyers who can clear their entire balance get a net 25% discount on the outstanding debt, while those unable to close fully can still qualify for a proportional reduction by paying at least 25% of what remains. That makes the program a direct incentive to deleverage, lift collateral quality and bring title deeds into the hands of owners faster.
The policy also matters for Turkey’s housing system because TOKİ sits at the intersection of social policy, property ownership and credit access. The campaign applies only to buyers whose installments began no later than end-June 2025, whose current-month payments are up to date, and who have no arrears in past installments or property taxes. Those with 12 months or less remaining are excluded. In practice, that means the scheme targets a specific pool of long-dated borrowers most likely to benefit from a reduced payoff rather than a refinancing workaround.
The deadline could also have short-term effects on bank traffic and cash flows as applicants must file through the bank used for the original sale. Buyers who want to settle the debt and receive the deed can also use mortgage financing from intermediary banks, underscoring how the state-backed housing program still channels activity through the banking system. Where condominium ownership has already been established, title delivery can proceed once local property valuation and valid DASK earthquake insurance documents are provided.
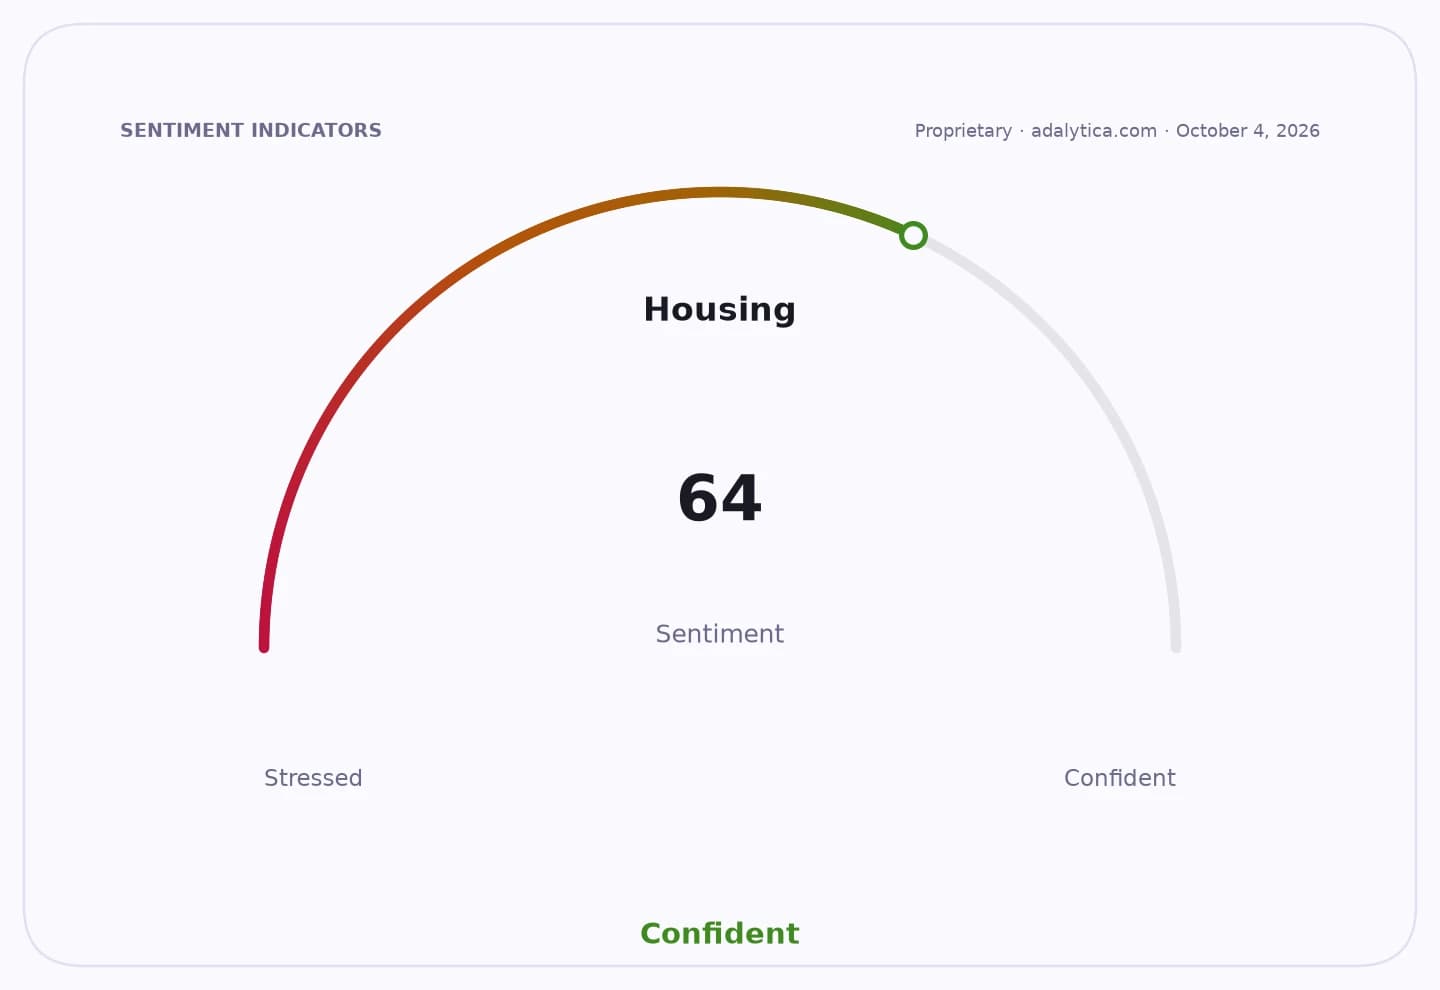
For investors, the wider relevance is less about TOKİ as a direct market instrument than about what the rush says on housing demand, liquidity pressure and households’ willingness to commit cash when a discount is available. The Adalytica household debt stress gauge shows elevated pressure, suggesting the discount may be landing in a market where owners are highly sensitive to any chance to reduce liabilities. That creates a bull case for faster repayments and cleaner balance sheets. The bear case is that only households with sufficient liquidity will be able to take advantage, leaving more strained borrowers behind.
The key date is Oct. 19. After that, the 25% discount will no longer apply to debt closures or partial payments, and the campaign’s immediate effect on deed transfers and borrower deleveraging will start to fade.
| Entity | Gains | Losses |
|---|---|---|
| TOKİ buyers with cash | ▲Lower payoff cost | ▼Missed deadline risk |
| TOKİ | ▲Faster collections | ▼Reduced debt balance |
| Banks handling payments | ▲Fee flow, traffic | ▼Administrative workload |
| Cash-strapped borrowers | ▲Partial discount option | ▼Less access to full benefit |