TSMC options traders are clustering around the $500 strike ahead of Thursday’s earnings, a sign that the chip giant’s next move may be as much about expectations as fundamentals.
TSMC Options Cluster Around $500 Before Earnings
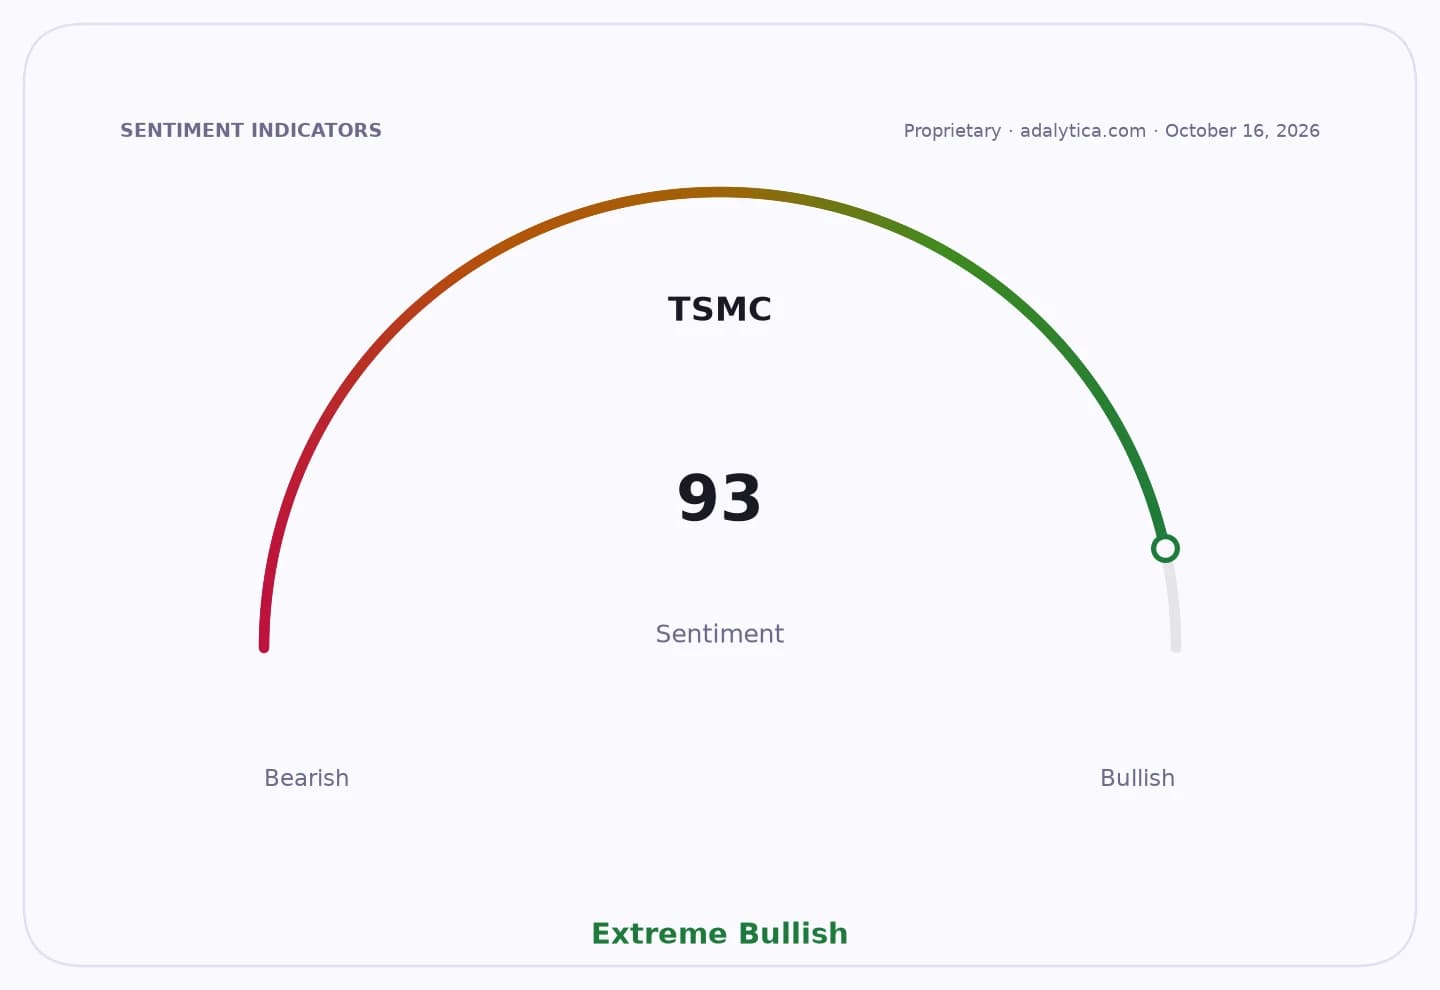
The market is pricing in a nearly 4% post-results swing, or about $16.60 a share, which tells you investors are not treating this as a routine quarterly release. When one of the world’s most important semiconductor companies becomes the center of heavy options positioning, it usually means the market is trying to handicap not just earnings, but the durability of the artificial intelligence boom that has powered TSMC higher.
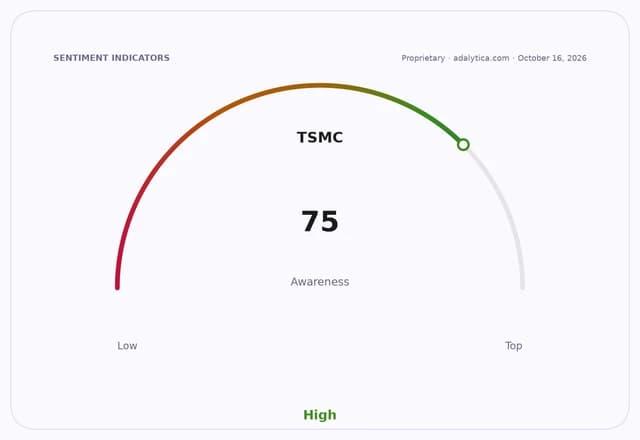
That matters because TSMC sits at the heart of the global AI supply chain. The company is the key manufacturer behind the processors that have fueled demand across data centers, cloud infrastructure and advanced computing. Its results therefore carry weight well beyond Taiwan or the chip sector. If TSMC confirms that AI demand is still running hot, that can reinforce the case for capital spending across the semiconductor ecosystem and support suppliers, equipment makers and AI infrastructure names. If growth looks even slightly less certain, the reaction could be outsized, given how much optimism is already embedded in the stock.
The options setup suggests traders see the $500 level as a major magnet. A large call wall at that strike often acts like a ceiling in the near term, as positioning there reflects a concentration of upside bets and hedging flows. With TSMC trading around $429 in Wednesday afternoon action after a 3.6% drop, the stock was already sitting below its recent highs but still well above its 50-day and 200-day moving averages, underscoring how much of the long-term AI story remains intact even as short-term momentum cools.
Technical readings also show a stock that has lost some of its near-term heat. TSMC’s RSI has slipped from overbought territory into the high 30s, while the shares have retreated from their recent peak. That does not change the company’s fundamental standing, but it does raise the stakes for earnings: a beat may be needed simply to restore confidence, while any hint of slower growth could invite more profit-taking from investors who have already enjoyed a powerful run.
For long-term investors, the bigger question is not whether TSMC moves 4% after one report. It is whether the company can keep translating AI demand into years of free-cash-flow growth and maintain its manufacturing edge against rivals and geopolitical noise. So far, the evidence has been overwhelmingly favorable, with the company delivering a sixth straight quarter of record profits and a 69% jump in third-quarter earnings. That kind of performance is exactly why TSMC remains one of the most important stocks in the global market.
Still, the caution in the outlook matters. A business as dominant as TSMC does not need to disappoint by much to trigger volatility when expectations are this high. For investors thinking in years, not days, that may be less a warning than a reminder: the best companies can still have bumpy quarters, and the right response is usually to watch the business, not the ticker, and let the compounding do the work.
| Entity | Gains | Losses |
|---|---|---|
| TSMC longs | ▲AI growth story, strong earnings | ▼Near-term volatility |
| TSMC call buyers | ▲Upside if earnings surprise | ▼Premium if stock stalls |
| Short-term traders | ▲Volatility opportunity | ▼Whipsaw risk |
| Semiconductor rivals | ▲Spillover AI demand if TSMC confirms strength | ▼Pressure if TSMC dominates again |