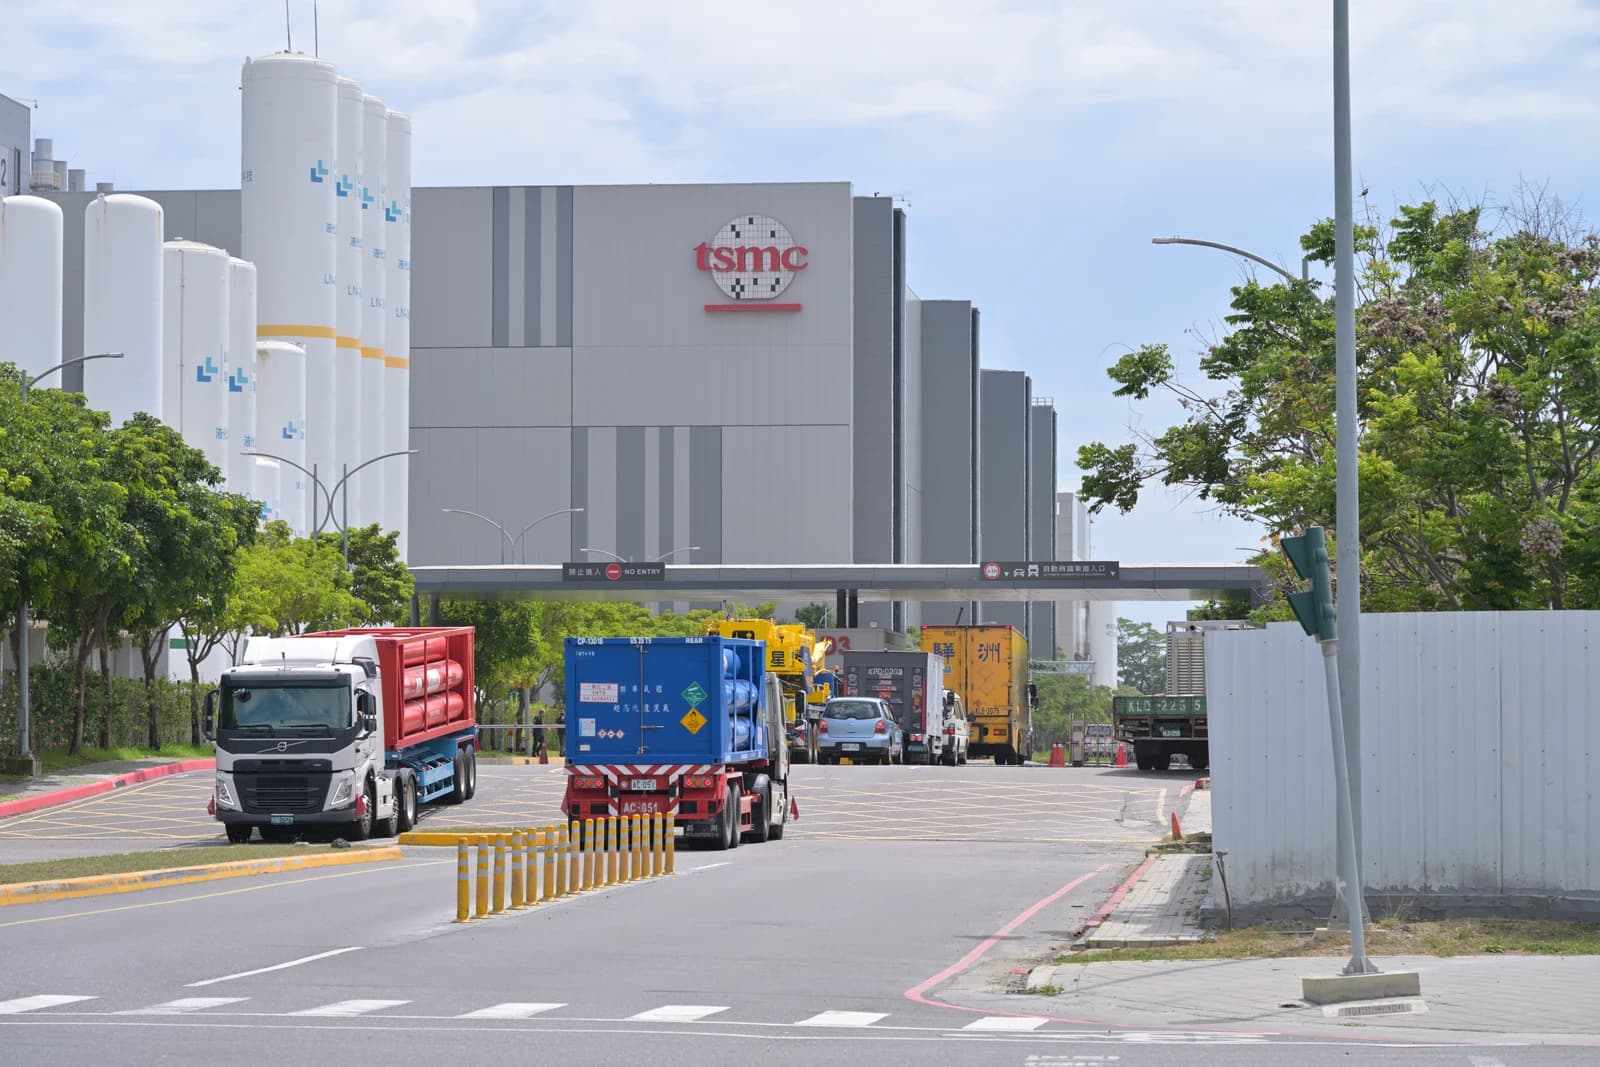
Taiwan Semiconductor Manufacturing Co. just proved that the AI boom is still turning into real profits, not just hype. The world’s most important chipmaker reported a record third-quarter net profit of NT$763.1 billion, up 68.7% from a year earlier and ahead of analyst expectations, underscoring how demand for advanced AI hardware is still expanding fast enough to lift the whole semiconductor chain.
TSMC reports record profit on AI chip demand
That matters because TSMC is the factory behind many of the chips driving the artificial intelligence buildout, including processors used in Nvidia’s data centers. When TSMC prints a new profit record, it is usually a sign that hyperscale cloud customers, chip designers and AI infrastructure buyers are still ordering aggressively. For investors, that makes TSMC one of the clearest long-term ways to own the AI spending cycle without betting on a single chip brand.
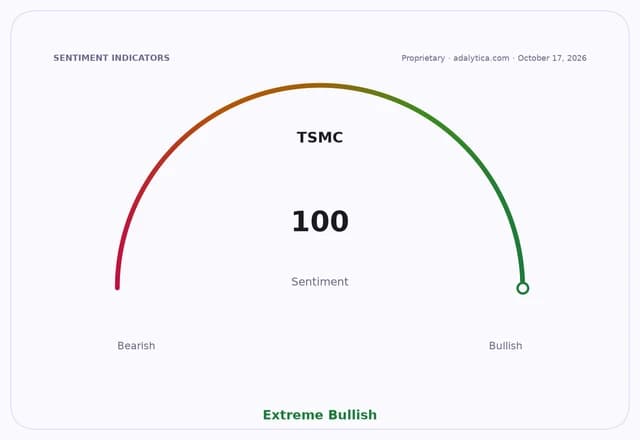
Revenue in the July-to-September period rose 50.9% to NT$1.5 trillion, also beating expectations. It was the sixth straight quarter of record net profit for the company, a streak that points to unusually durable demand rather than a one-quarter surge. TSMC also topped its previous quarterly high of NT$706.6 billion, set just a quarter earlier, showing that the company is still moving up the earnings curve even after years of rapid growth.
The market had already been bracing for a strong result, but TSMC shares slipped 2.2% before the report and stayed under pressure afterward, a reminder that lofty expectations can still leave room for short-term disappointment. Even so, the longer-term picture remains constructive. TSMC’s dominance in leading-edge manufacturing gives it pricing power, scale and a critical position in the supply chain, which is exactly the kind of moat long-term investors should want in a capital-intensive industry.
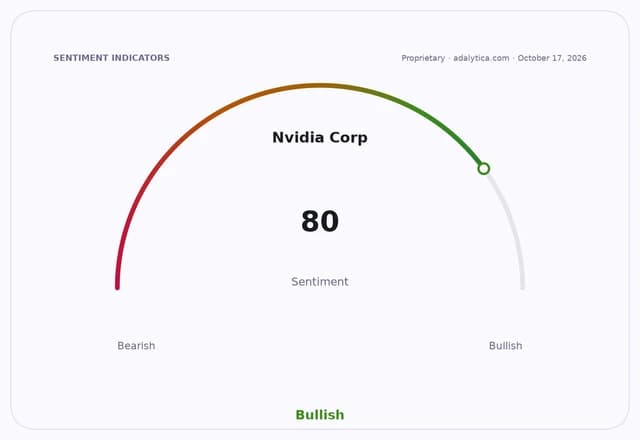
The bigger takeaway is that AI spending is still flowing through to the companies that actually make the picks and shovels. If that demand holds, TSMC should remain a key beneficiary of cloud expansion, next-generation chips and rising semiconductor complexity. For investors building wealth over years, not weeks, TSMC remains a name worth watching closely and keeping on the long-term radar.
| Entity | Gains | Losses |
|---|---|---|
| TSMC | ▲Record profit and revenue growth | ▼Higher expectations |
| AI chip customers | ▲More supply capacity | ▼Less bargaining power |
| Nvidia | ▲Continued foundry support | ▼Dependence on TSMC capacity |
| Short-term traders | ▲Volatility to trade | ▼Momentum after earnings may fade |