A majority of Thailand’s salaried workers are living on a financial knife edge, a warning sign for household consumption, credit quality and employer-sponsored benefits as economic uncertainty and AI-driven job disruption reshape the labor market.
TTB flags debt stress among Thai salaried workers
TTB said 82% of salaried employees surveyed carry debt, while 54% have no emergency savings for at least six months of expenses and 65% are paying only minimum instalments. The bank also said 80% remain underinsured, pointing to a broad gap between income and true financial resilience that extends well beyond the monthly paycheck.
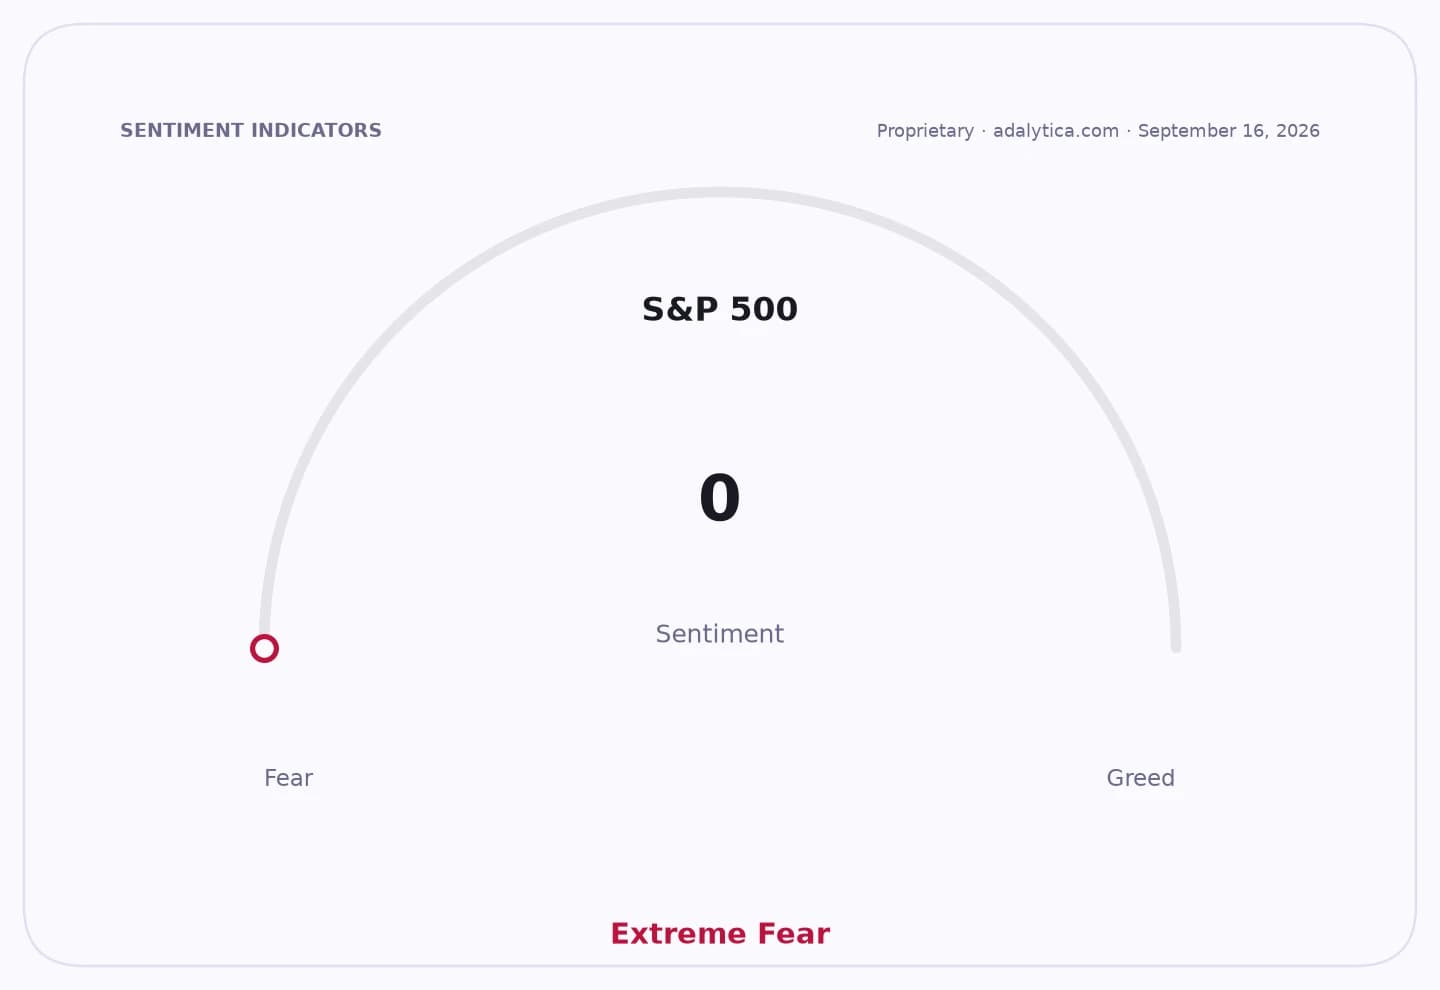
Sentiment IndicatorsⓘProprietary · adalytica.com · September 10, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The figures matter because Thai households are a key support for domestic demand. When workers are highly leveraged and have no cushion, they are less able to absorb higher living costs, interest rates or income shocks, and more likely to cut discretionary spending. That weakens the outlook for retailers, consumer lenders and service businesses already operating in a slower-growth environment.
For banks, the message is more nuanced. High debt burdens can support loan demand, but they also increase refinancing risk and raise the probability of delinquency if the labor market softens. Minimum-payment behavior suggests many borrowers are not reducing principal meaningfully, which can trap households in prolonged debt cycles and leave lenders exposed to repayment stress if cash flows tighten.
TTB’s response is to push financial well-being products through corporate clients, positioning itself as a provider of workplace benefits rather than only a lender. The bank said it has already run financial health checks for more than 144,000 customers and provided basic coverage to more than 2.3 million holders of its fee-free deposit account, while it now wants to help more workers reach their first 1 million baht in savings and investments.
That strategy reflects a broader shift in banking: growth increasingly depends not just on issuing credit, but on capturing salary-linked customers with savings, insurance and wealth products. For employers, better financial wellness can help reduce staff stress and turnover. For workers, it may be the difference between debt rollover and building a buffer.
The bigger risk is that the structural pressures behind the survey are not temporary. Inflation, uneven growth and the changing labor market are making it harder for households to build savings just as they need more protection. If wage gains lag expenses, the strain on consumer balance sheets could persist, keeping pressure on domestic demand and forcing lenders to compete harder for safer, more affluent customers.
| Entity | Gains | Losses |
|---|---|---|
| TTB | ▲More corporate clients | ▼Higher household distress |
| Thai salaried workers | ▲Access to financial tools | ▼Debt burden, no cash buffer |
| Banks | ▲Fee-based cross-selling | ▼Rising credit risk |
| Employers / HR teams | ▲More stable workforce | ▼Higher pressure to fund benefits |