More than 2.3 million UK households are set to remortgage next year on worse terms just as the Bank of England prepares to raise interest rates again, threatening to deepen pressure on borrowers already squeezed by inflation, energy bills and slower growth.
UK households face higher remortgage costs
The immediate economic significance is straightforward: another round of higher borrowing costs would lift monthly payments for households rolling off fixed-rate deals and could tighten the housing market further. The Bank’s nine-member monetary policy committee is widely expected to lift the base rate to 4% from 3.75% this week, after UK inflation rose to 3.5% in September, with money markets pricing as many as four quarter-point increases over the next 12 months.
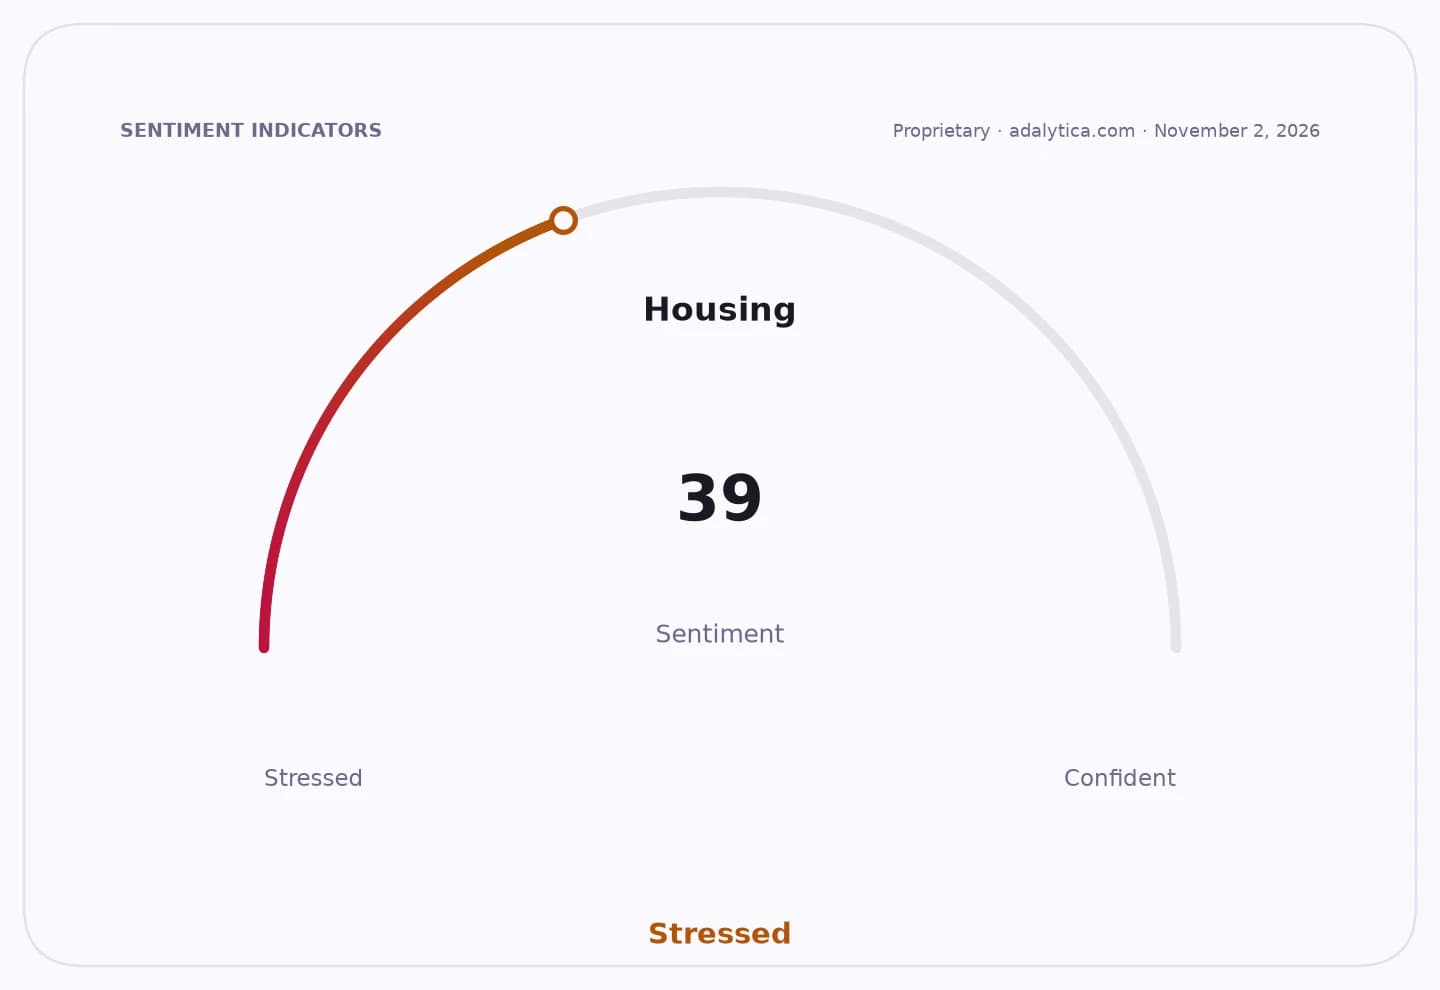
Sentiment Indicators
That would hit a large chunk of the mortgage market at once. UK Finance says 700,000 borrowers are due to switch to new rates in the second half of this year, while a further 2.3 million households will come off fixed deals in 2027. With swap rates already elevated, fixed mortgage pricing has risen even before any fresh move from the central bank.
The squeeze is already showing up in lending data. Mortgage approvals fell to a near three-year low in September as higher borrowing costs deterred buyers, adding to signs that the housing market is weakening under the weight of dearer credit. The Office for Budget Responsibility has also warned that household disposable incomes will fall 0.6% next year, a sharp reversal from its March forecast for a 0.6% rise.
For investors, the story matters beyond Britain’s homeowners. Banks and mortgage lenders face a more difficult balance between lending volumes and credit quality, while insurers and consumer-focused retailers may see weaker demand if households cut spending to absorb higher repayments. Sterling and UK rate markets are also in focus, with the pound trading near recent levels as traders weigh how far the Bank will go.
The backdrop is worsening rather than easing. Energy prices remain a major inflation driver, with Ofgem’s price cap expected to rise by more than £400 in January, and the Bank of England is watching for wage pass-through that could embed inflation. The central bank will publish updated growth and inflation forecasts alongside its decision this week, which will help determine whether the remortgage shock is a short-term adjustment or the start of a longer squeeze on UK consumers.
| Entity | Gains | Losses |
|---|---|---|
| Bank of England | ▲More room to fight inflation | ▼Borrowers and mortgage demand |
| UK banks/lenders | ▲Higher loan margins on new deals | ▼Volumes and affordability-driven demand |
| UK homeowners | ▲None | ▼Higher monthly repayments |
| UK housing market | ▲None | ▼Fewer approvals, weaker activity |