America’s coal industry is getting a rare second act under President Donald Trump, and investors are already seeing the effect in the stocks of the biggest publicly traded miners.
U.S. Coal Miners Gain Under Trump Policy Support
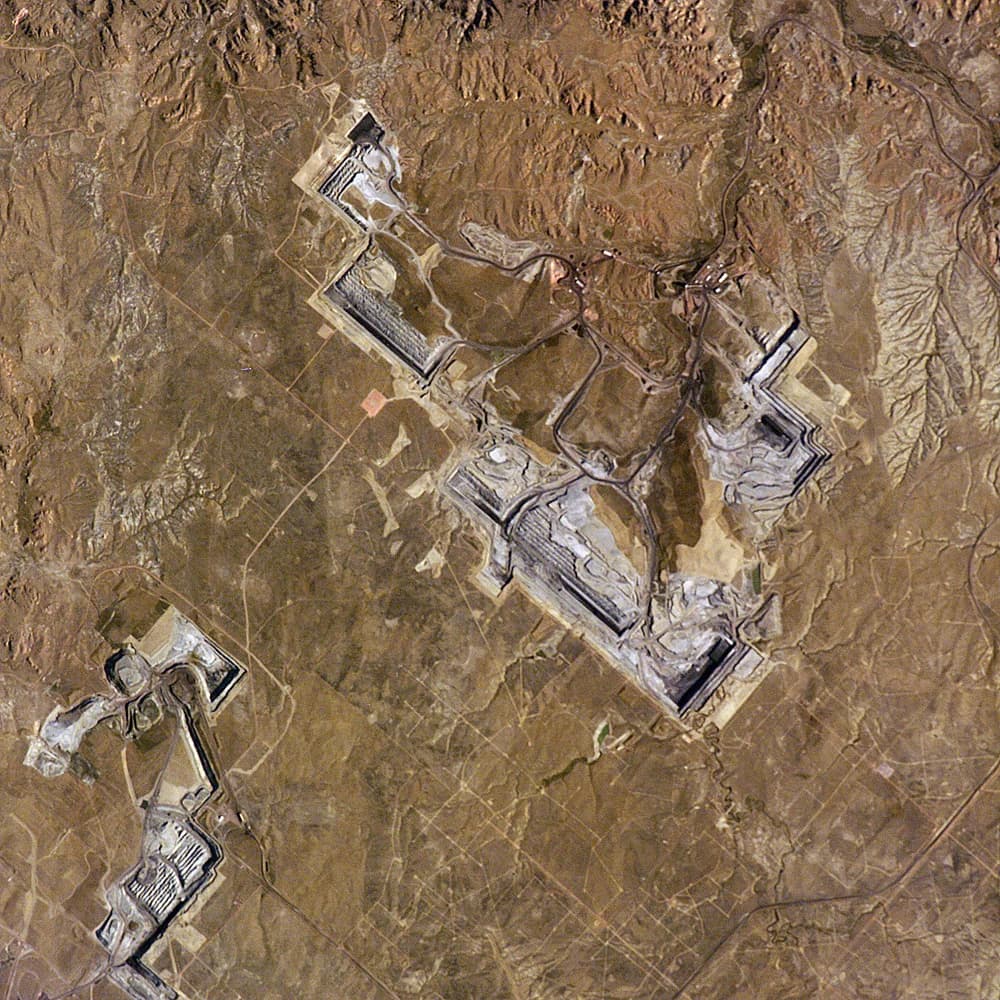
That matters because coal remains deeply tied to U.S. electricity supply, export flows and commodity prices, even as the long-term structural decline in the fuel is hard to ignore. Policy can’t make coal the growth engine it once was, but it can absolutely change cash generation, mine approvals, permitting risk and the life span of existing assets — and that is enough to move markets.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 15, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
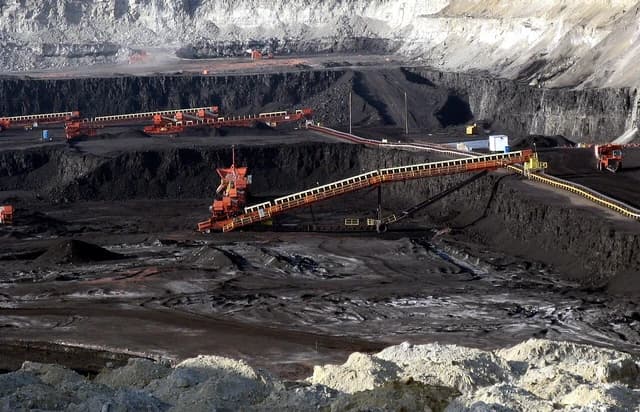
The broad economic backdrop helps explain why the trade still has legs. U.S. industrial production is projected to edge higher again, with the latest reading at 103.07 and a forecast of 103.25, a sign that the economy is still running well enough to keep power demand and heavy-industry fuel needs relevant. At the same time, U.S. crude prices have been volatile, and coal is still part of the energy-security conversation when oil and gas markets get tight. For policymakers focused on domestic supply, coal offers something the energy transition often struggles to guarantee: dispatchable power and a large existing infrastructure base.
That policy support is colliding with a market that has not fully bought the idea of a lasting coal revival. Peabody Energy, the best-known pure-play U.S. coal name, has fallen to about $23.46 from a March high near $39.25, and its technical picture has weakened, with the shares below both the 50-day and 200-day moving averages and an RSI reading near 29, typically a sign of oversold conditions rather than durable strength. Alliance Resource Partners has held up better, with the partnership trading around $24.87 and still slightly above its 200-day moving average, while Arch Resources has slipped to roughly $174.51 from above $240 earlier in the year. In other words, the rally that followed Washington’s friendlier tone has met the reality of a market that still expects coal demand to erode over time.
For long-term investors, that tension is the whole story. Trump’s White House can extend the cash-producing life of coal assets by easing regulation, speeding permits and signaling political support for domestic mining. That is good news for miners with disciplined capital spending, strong contracts and low-cost reserves. It is less helpful for companies that need a broad and durable rebound in coal prices to justify aggressive growth. The SEC disclosures from ARLP and AMR still emphasize the usual risks: softer coal prices, customer inventory swings, environmental regulation and permit delays. Those are not footnotes. They are the business model.
The broader global picture is even more nuanced. Australia is boosting coal output despite climate commitments, because Asian demand and higher prices still matter. That tells you coal is not vanishing overnight; it is becoming a more geopolitical commodity, shaped by energy security as much as decarbonization. For investors, the lesson is simple: policy can create tradable rallies, but the best returns in this sector usually come from buying strength in businesses with real cash flow, not from betting that coal’s long-term decline has been magically reversed.
If you own coal stocks, the Trump effect may still support near-term earnings and dividends. If you do not, this is a sector worth watching — but only as a small, disciplined slice of a diversified portfolio built for the next decade, not the next headline.
| Entity | Gains | Losses |
|---|---|---|
| U.S. coal miners | ▲Easier permits, longer asset life | ▼Structural decline remains |
| BTU, ARLP, AMR shareholders | ▲Potential cash flow lift | ▼Price volatility and policy risk |
| Trump administration | ▲Energy-security win, political support | ▼Climate criticism |
| Utilities and coal buyers | ▲Short-term supply optionality | ▼Higher fuel and compliance uncertainty |