The US dollar is trying to defend the 101.80 area ahead of Federal Reserve minutes that could reset expectations for the timing of the next policy move, with traders still seeing little urgency from policymakers to raise rates again.
US Dollar Defends 101.80 Ahead of Fed Minutes
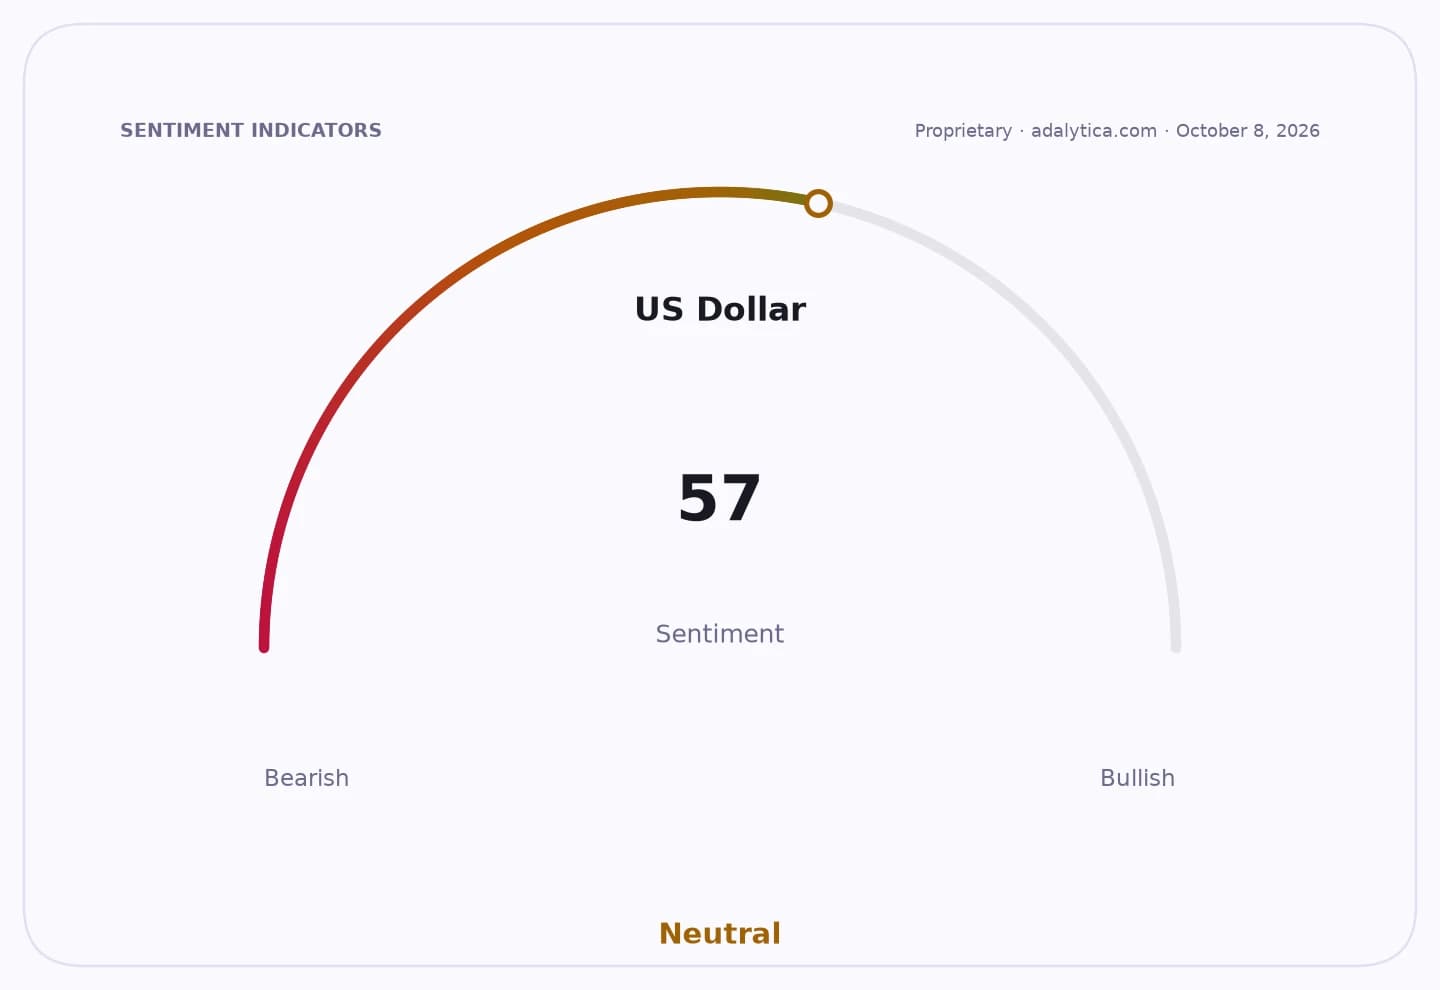
That matters because the dollar’s near-term direction is being driven less by economic data than by the path of Fed communication. If the minutes reinforce the view that officials are comfortable pausing, Treasury yields could drift lower and the greenback may struggle to extend its recent rebound. If the transcript sounds firmer on inflation risks, the dollar could attract fresh safe-haven demand and push through resistance.
The dollar index-backed UUP ETF has been edging higher, closing at 29.04 on Oct. 7 after a 28.90 finish the previous session. Technically, the fund remains above its 50-day moving average of 28.29 and its 200-day average of 27.77, a sign the broader trend has not broken down. But momentum is stretched: the RSI reading of 79.5 points to overbought conditions, while the ETF is trading near the upper end of its Bollinger Band range. That leaves the market vulnerable to a pullback if the Fed minutes disappoint dollar bulls.
Macro signals are mixed. The 10-year US Treasury yield is around 5.29%, near the upper end of recent moves, which would normally support the dollar by widening the rate advantage over peers. But Fed funds expectations still point to 3.726% next month, implying investors do not see a tightening cycle that is strong enough to produce a sustained leg higher in yields. In other words, the market is leaning on carry, but not on a fresh policy shock.
Commodity and cross-asset flows also matter. Oil prices have recovered on storm-related supply concerns, which can add to inflation anxiety and temporarily support the dollar. At the same time, bond-market positioning looks defensive: Adalytica’s US Treasury bonds trade signals show sentiment at 22, or “Fear,” while awareness remains elevated, suggesting investors are still hedging duration risk rather than embracing a clear macro trend. That combination argues for choppy trading rather than a one-way move.
For investors, the key question is whether 101.80 in the dollar index becomes a floor or a false bottom. A hold above that zone would keep the recent rebound intact and favour dollar longs versus lower-yielding currencies. A break lower would suggest the Fed minutes were not hawkish enough to sustain the rally, opening the door to profit-taking in the dollar and relief in gold, equities and emerging-market assets that are sensitive to US rate pressure.
| Entity | Gains | Losses |
|---|---|---|
| US dollar bulls | ▲A hawkish FOMC read | ▼Momentum if support breaks |
| Dollar bears | ▲A dovish pause signal | ▼If yields stay elevated |
| US Treasuries | ▲Softer Fed language | ▼If inflation risks reprice |
| Risk assets | ▲Easier financial conditions | ▼If the dollar extends higher |